


Platform Launch Might Change The Case For Investing In Insulet Stock (PODD)
- Insulet reported the full U.S. market release of Omnipod Discover, a web-based data platform that provides Omnipod 5 users, caregivers and clinicians with shared, visual diabetes insights and personalized weekly reports on glucose and insulin delivery.
- The company linked Omnipod Discover to real world improvements in time in range for some users and highlighted adoption by more than 15,000 Omnipod 5 users and over 1,800 healthcare professionals before nationwide rollout.
- We will now look at how Insulet's investment narrative is shaped by Omnipod Discover's data driven support for Omnipod 5 users.
Look beyond Insulet and Omnipod. Discover and compare these stocks with a curated group of healthcare AI players using the 33 healthcare AI stocks as a starting list.
Insulet Investment Narrative Recap
To own Insulet, you need to believe the Omnipod franchise keeps adding users and that retention, especially in type 2 diabetes, becomes more predictable. The full rollout of Omnipod Discover looks incremental for that story in the near term. It may help engagement, but the key short term catalyst is still how quickly type 2 utilization stabilizes after the guidance reset.
The biggest operational risk remains weaker retention and pricing in the U.S. type 2 group, along with any lingering impact from past product recalls. Omnipod Discover’s reported uplift in time in range for a portion of users supports Insulet’s focus on data driven tools, but on its own it does not remove those retention and quality execution questions.
Among recent developments, Omnipod 5 upgrades and the Omnipod 6 pivotal data sit closest to the same theme as Omnipod Discover. The firm is leaning into algorithms and automation, then layering software support like Discover on top. For you as a shareholder, the interest is less about any single feature and more about whether that ecosystem keeps people on pods longer.
Real world outcomes presented with Omnipod 6, such as higher time in range and fewer boluses, together with Omnipod Discover’s reported improvements for some users, show a consistent focus on glycemic performance. If that package helps Insulet address type 2 churn, supports international adoption and maintains high recurring pod margins, it reinforces the existing catalysts and makes the current retention issues the key execution swing factor.
Insulet's narrative projects US$4.5b revenue and US$675.9 million earnings by 2029. That lines up with analysts assuming 13.7% yearly revenue growth and implies an earnings increase of about US$300.6 million from US$375.3 million today.
Discover why Insulet's fair value indicates an 18% potential upside to its current price that could narrow quickly.
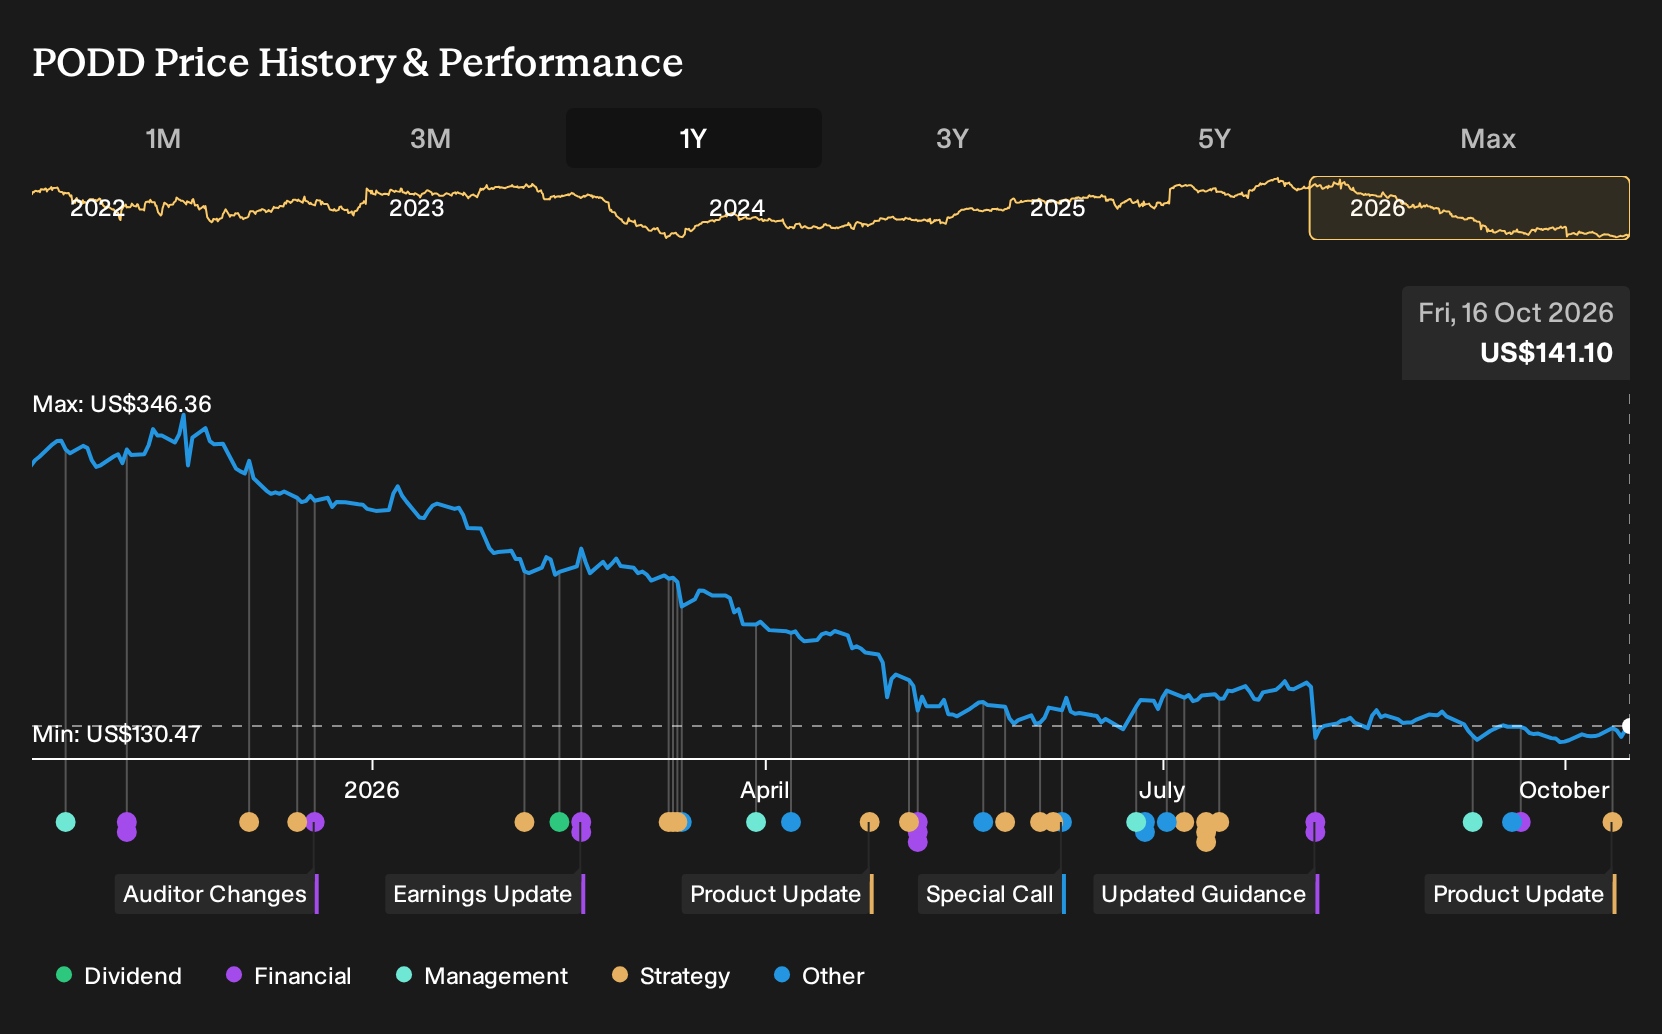
Exploring Other Perspectives
One alternate view on Insulet focuses on slower type 2 diabetes adoption. The most cautious analysts already baked in only 10.1% yearly revenue growth and earnings of about US$682.2 million by 2029 before this Omnipod Discover news. That is a stricter bar than consensus, so you should expect opinions to shift as new data lands and consider both narratives side by side.
Explore 4 other Insulet fair value estimates, including one that suggests as much as 15% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Insulet research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Insulet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insulet's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insulet?
Once you have formed a view on Insulet, it often helps to compare it with other opportunities that fit different risk and return profiles. The Simply Wall St Screener lets you filter for fundamentals that match your own rules rather than relying on broad market narratives.
- If you want potential mispricing with quality in mind, start by scanning a focused list of 33 high quality undervalued stocks that combine stronger fundamentals with appealing valuations.
- If balance sheet strength is your priority, consider running through a list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial resilience with underlying fundamental support.
- If you are hunting for ideas that the crowd may have overlooked, use a curated set of 20 high quality undiscovered gems as a source of fresh watchlist candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com