


How Contracted Sales Results Will Impact Yuexiu Property Stock Investors
- Yuexiu Property reported unaudited contracted sales for September 2026 of about RMB 6,810 million with 157,400 sq.m. of GFA, while year to date contracted sales reached roughly RMB 68,018 million on 2,186,600 sq.m. of GFA.
- The mix of a marginal 0.1% year on year rise in September sales value, a 14.8% year to date sales value decline, and a 6.7% year to date GFA increase suggests pressure on average selling prices and product mix.
- Next, attention turns to how Yuexiu Property's softer year to date contracted sales value may influence the broader investment narrative around the stock.
Stress test your view on Yuexiu Property against other real estate plays by scanning our hand picked list of solid balance sheet and fundamentals (204 results) that may better withstand softer contracted sales trends.
What Is Yuexiu Property's Investment Narrative?
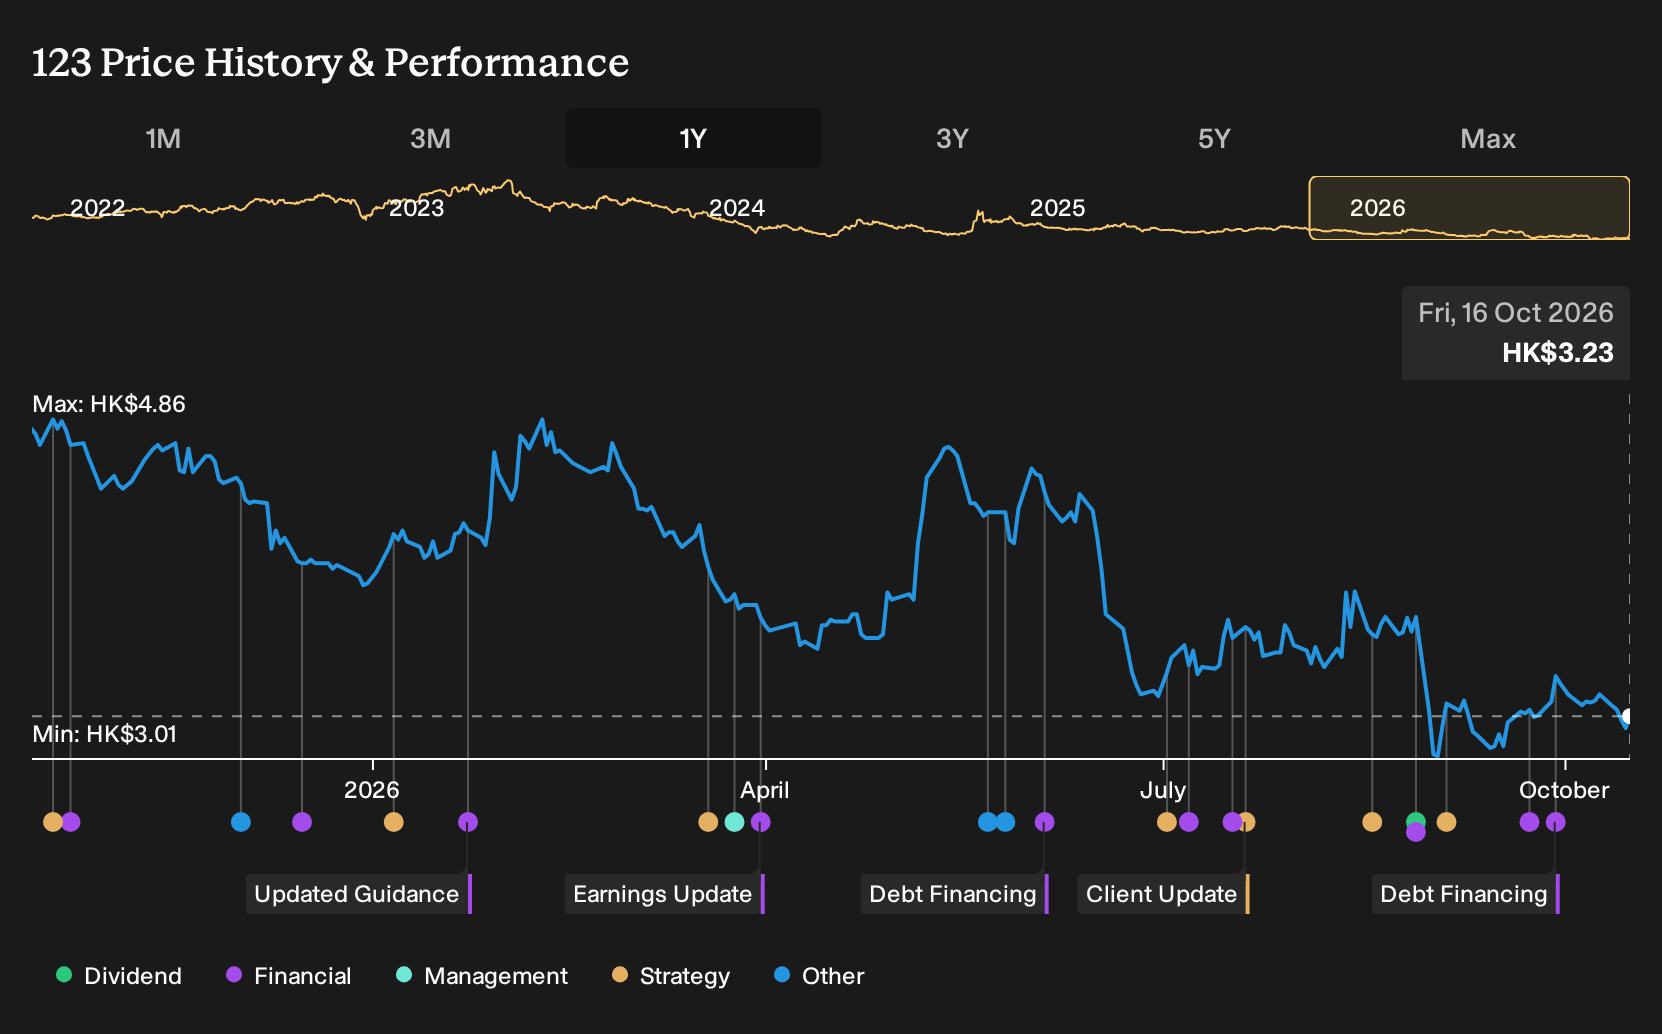
The big question with Yuexiu Property is whether you are comfortable owning a capital intensive developer where contracted sales volumes and pricing power drive almost everything. September’s print fits into that story in a slightly uncomfortable way. The value of monthly sales barely moved year on year while GFA shrank sharply, and year-to-date figures show softer contracted value but higher area sold. That combination hints at pressure on average selling prices just as the share price has already declined 19.7% year to date and 31.4% over 12 months.
In the short term, that matters for two things you probably care about. First, weaker ticket sizes can make it harder for Yuexiu Property to translate forecast earnings improvement into actual cash generation, which is important when interest costs are not well covered by earnings and the group relies entirely on higher risk funding. Second, a business that is still loss making, with revenue already reported lower in the last year, has less room for project delays or further demand softness before balance sheet concerns start to dominate the discussion.
Even so, the more interesting question for anyone looking at Yuexiu Property now is whether the discount and the forecast profit recovery really compensate for the fact that ...
There's only one way to know the right time to buy, sell or hold Yuexiu Property. Head to Simply Wall St's company report for the latest analysis of Yuexiu Property's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yuexiu Property research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yuexiu Property. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yuexiu Property's overall financial health at a glance.
Looking For More Investment Ideas Beyond Yuexiu Property?
If this update on Yuexiu Property has raised more questions than answers, balance the picture by lining it up against other companies with very different risk and return profiles on the Simply Wall St Screener.
- For investors who want potential mispricing and quality in the same place, check out 191 high quality undervalued stocks that already pass a high bar on fundamentals.
- If capital preservation comes first for you, start with 233 resilient stocks with low risk scores that score well on financial health and volatility measures.
- When you want sturdier finances behind your investment thesis, compare Yuexiu Property with our curated list of solid balance sheet and fundamentals (204 results) that may offer stronger balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com