


Soft Quarterly Results Might Change The Case For Investing In Old Republic International Stock (ORI)
- Old Republic International recently reported softer quarterly figures, with long term revenue, net premiums earned and EPS each growing at low single digit annual rates.
- These sluggish fundamentals point to pressure on underwriting profitability and operating leverage, which can make Old Republic International more reliant on tight cost control and disciplined capital use.
- We will now see how Old Republic International's weaker long term revenue and EPS trends could influence the investment narrative already in place.
Balance out Old Republic International's sluggish profile by scanning a curated 33 high quality undervalued stocks that pair steadier fundamentals with more compelling growth potential.
Old Republic International Investment Narrative Recap
To stay invested in Old Republic International, you need to believe that slower premium growth and weak long term EPS expansion can still support acceptable returns on capital, while technology and specialty build outs eventually ease pressure on underwriting results. The recent share pullback after softer quarterly figures mainly reinforces that the near term story is about cost discipline and underwriting control.
The key short term swing factor remains whether Specialty Insurance can stop the margin compression created by reserve strengthening and higher expense ratios. The biggest risk is that heavier technology and expansion spending fail to produce clear productivity gains, leaving group profitability stuck at a lower level while capital returns continue.
The most relevant development tied to this setback is the ongoing ramp in Specialty Insurance, where pretax operating income previously softened and the combined ratio moved higher due to reserve strengthening and new unit expenses. That history matters because it shows how quickly underwriting friction can translate into weaker group earnings when growth is modest.
Against that backdrop, the build out of new specialty platforms, the ECM farm and agriculture integration, and technology projects form the main operational catalysts investors are watching. If those businesses scale without further reserve issues and the cost base settles, Old Republic International could see its margin profile stabilize even if top line expansion remains muted.
Old Republic International is described by analysts as potentially reaching about $11.0b in revenue and $674.8m in earnings by 2029, based on an assumed 4.1% yearly revenue growth rate and a change from current earnings of about $1.1b, which would represent an earnings decline of roughly $425m over that period.
Uncover how Old Republic International's fair value indicates a 10% potential upside to its current price before the market closes the gap.
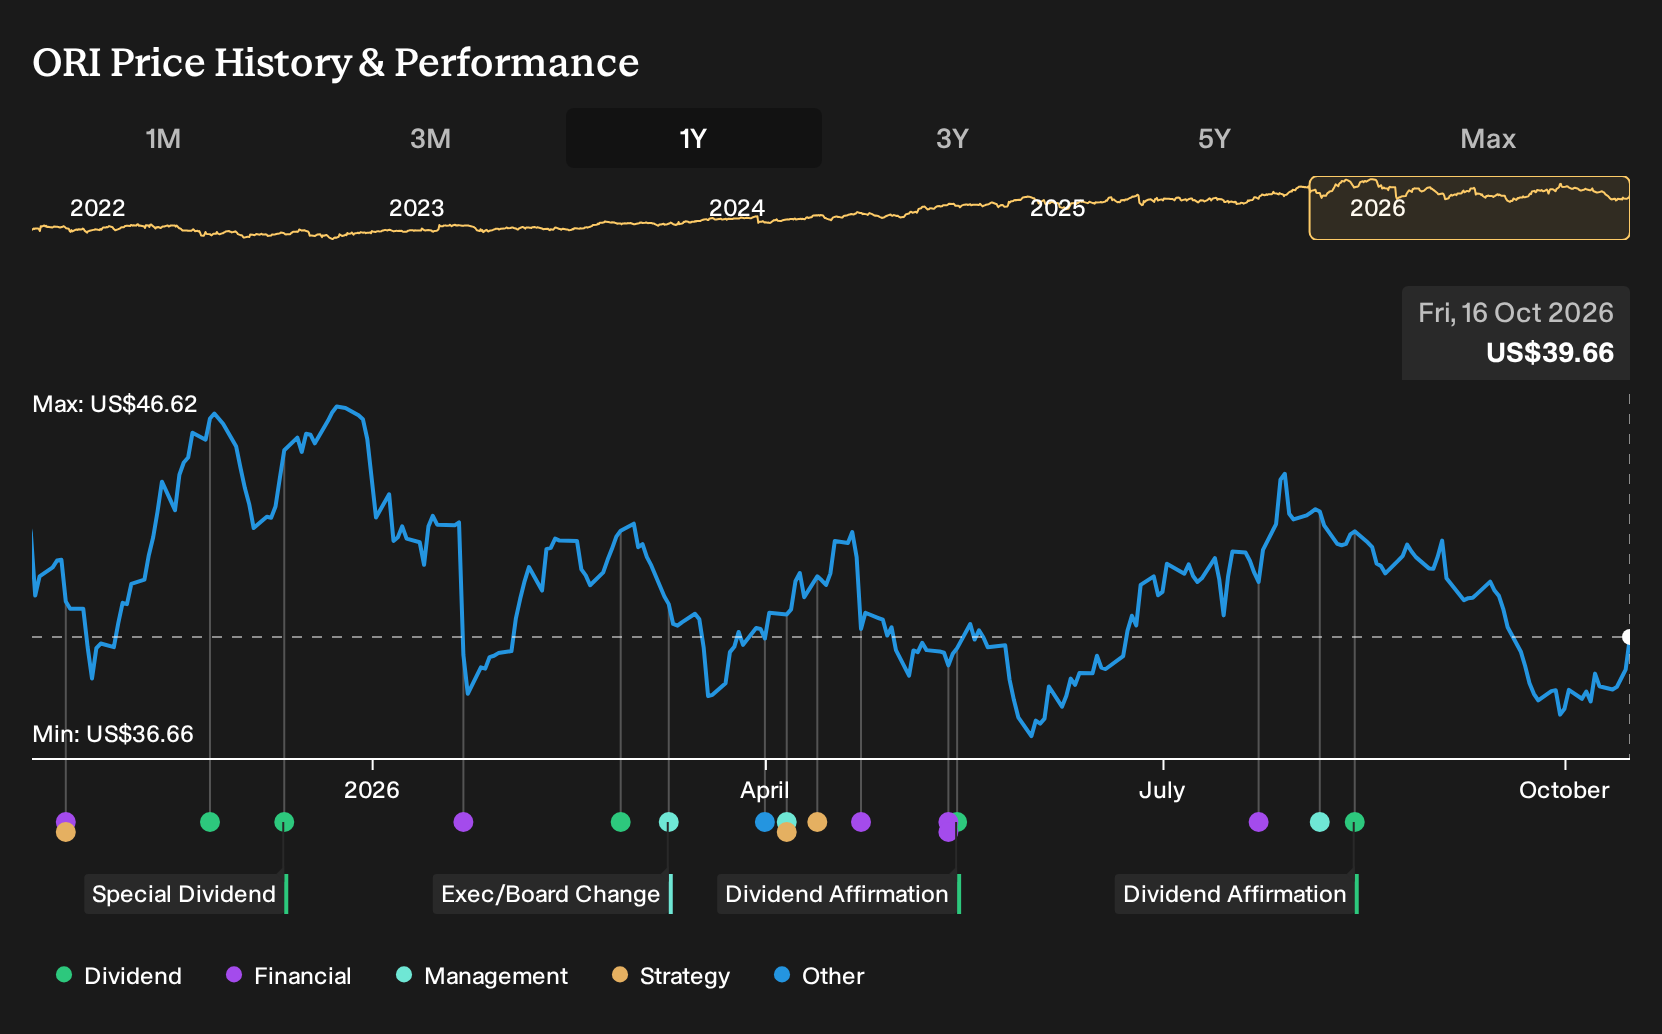
Exploring Other Perspectives
The Simply Wall St Community only offers two fair value views for Old Republic International, yet they still span a wide US$43.5 to about US$72.4 range. That spread sits alongside softer Specialty Insurance profitability and higher technology spending, which together keep future earnings power and valuation outcomes very open to debate, so you should examine several viewpoints.
Explore another Old Republic International fair value estimate, including one that suggests it could be worth just $43.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Old Republic International research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Old Republic International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Republic International's overall financial health at a glance.
Looking for more Old Republic International investment ideas?
If Old Republic International is only one piece of your watchlist, it can help to line it up against other companies with different risk, income, and balance sheet profiles using the Simply Wall St Screener.
- Prefer resilience and fewer surprises in tougher markets? Start with a 32 resilient stocks with low risk scores that tend to show steadier fundamental profiles.
- Want income to do more of the work for you? Consider a 8 dividend fortresses that focus on higher yields with supporting cash flows.
- Care most about financial strength and staying power? Use a list of solid balance sheet and fundamentals (25 results) that combine stronger balance sheets with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com