


BRP (TSX:DOO) Stock Looks Expensive Even After A 29% Slide
BRP has had a tough run over the past few years, which naturally pushes investors to ask whether the current share price properly lines up with what the business is earning. The question now is whether the recent valuation the market is putting on BRP stock is actually supported by its earnings power.
- Over the past 5 years the share price has fallen 28.8%, which puts the focus squarely on whether the current valuation still reflects the earnings that BRP is producing today.
- Ski-Doo's recent Snow Goer Snowmobile of the Year award highlights product strength that can influence expectations for future profitability and the durability of BRP's earnings stream.
- Your read on BRP is one view; the desks covering it have another. See what analysts think BRP's shares could be worth.
The issue now is whether BRP's current price is justified by its earnings when set against the Fair Ratio benchmark.
If you want a wider starting point as you assess BRP's earnings story, compare it with companies in the 5 high quality undervalued stocks.
Has BRP Run Too Far on Earnings?
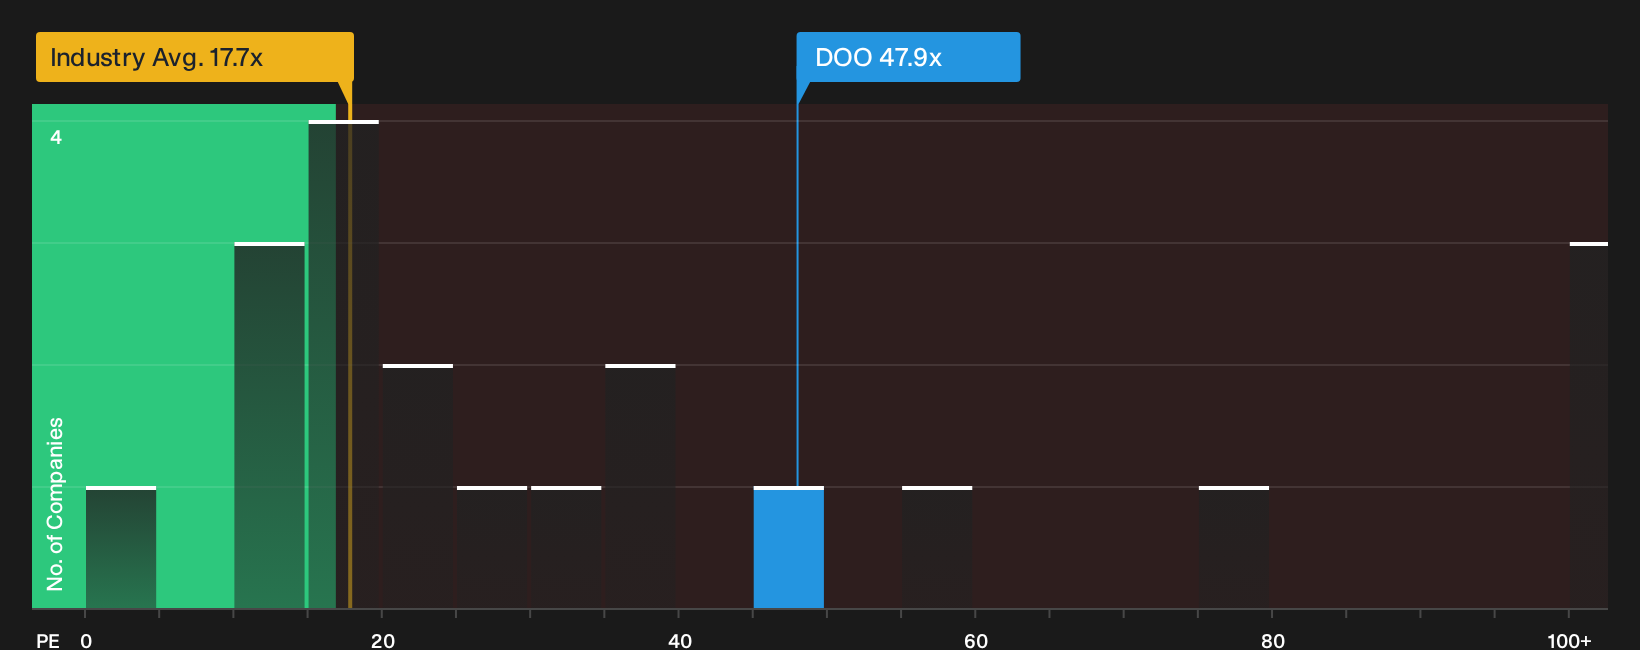
The P/E ratio suits BRP because earnings still anchor how investors frame the value of its mature recreational brands. Despite the recent Ski-Doo award lifting the story around product quality, the stock trades on a P/E of 47.9x, which is above the Leisure industry average of 17.7x and also above the peer group at 37.6x. That already signals investors are paying a richer price for each dollar of profit than is typical in the sector.
The Fair Ratio represents the multiple you might expect given BRP's own mix of growth prospects, margins, size and risk. The current P/E sits above that level, so on this framework the shares screen as overvalued relative to their earnings power. For an investor, that means the market is already baking in a lot of optimism around BRP's profit trajectory, leaving less room for disappointment than in cheaper Leisure stocks. Explore the numbers behind BRP's P/E valuation.
The BRP Narrative: What Would Justify Today's Price?
For BRP, Simply Wall St Narratives pick up where the valuation puzzle leaves off by spelling out which expectations for growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Rather than relying on a single multiple or model output, each scenario lays out the key drivers behind its fair value view so you can compare those assumptions with actual results as they are reported.
One of the top community narratives on BRP: 24% undervalued
"The rapid expansion of BRP's electric vehicle lineup, including products such as the Outlander electric ATV and electric motorcycle, continues to frame an opportunity..."
Discover why this Narrative puts BRP at 24% undervalued.
One more piece of the BRP puzzle before you decide
Price multiples tell you what the market is willing to pay today, but professional coverage also sketches out where they expect BRP's earnings profile to sit a few years from now. Explore where analysts expect BRP to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com