


Could EMA Review Alter The Investment Case For Hansoh Pharma Stock (SEHK:3692)?
- Hansoh Pharmaceutical Group reported that it resubmitted the EU marketing authorization application for Aumolertinib on 29 September 2026, and that the EMA validated the filing on 7 October 2026, starting a centralized review for two advanced non small cell lung cancer indications in EGFR mutated patients.
- The EMA validation moves Aumolertinib one step further toward potential EU commercialization. This development could reshape Hansoh Pharmaceutical Group's geographic mix, regulatory workload, and cost structure if the therapy eventually enters the European market.
- The next area of focus is how Hansoh Pharmaceutical Group's investment narrative is affected by the EMA's validation of Aumolertinib's EU application.
Scan how Hansoh Pharmaceutical Group fits into the broader healthcare opportunity by comparing it with hand picked 127 healthcare AI stocks benefiting from advances in targeted therapies and data driven drug development.
What Is Hansoh Pharmaceutical Group's Investment Narrative?
To own Hansoh Pharmaceutical Group, you need to believe in a China based drug maker that already has meaningful oncology exposure, strong reported profitability and a growing pipeline that can travel. The EMA validation of Aumolertinib pushes that international story along, but the operational crunch still lives in execution, pricing power in core Mainland China revenue of CN¥15,898.772m, and how efficiently management can scale outside its home market without letting costs run ahead of demand.
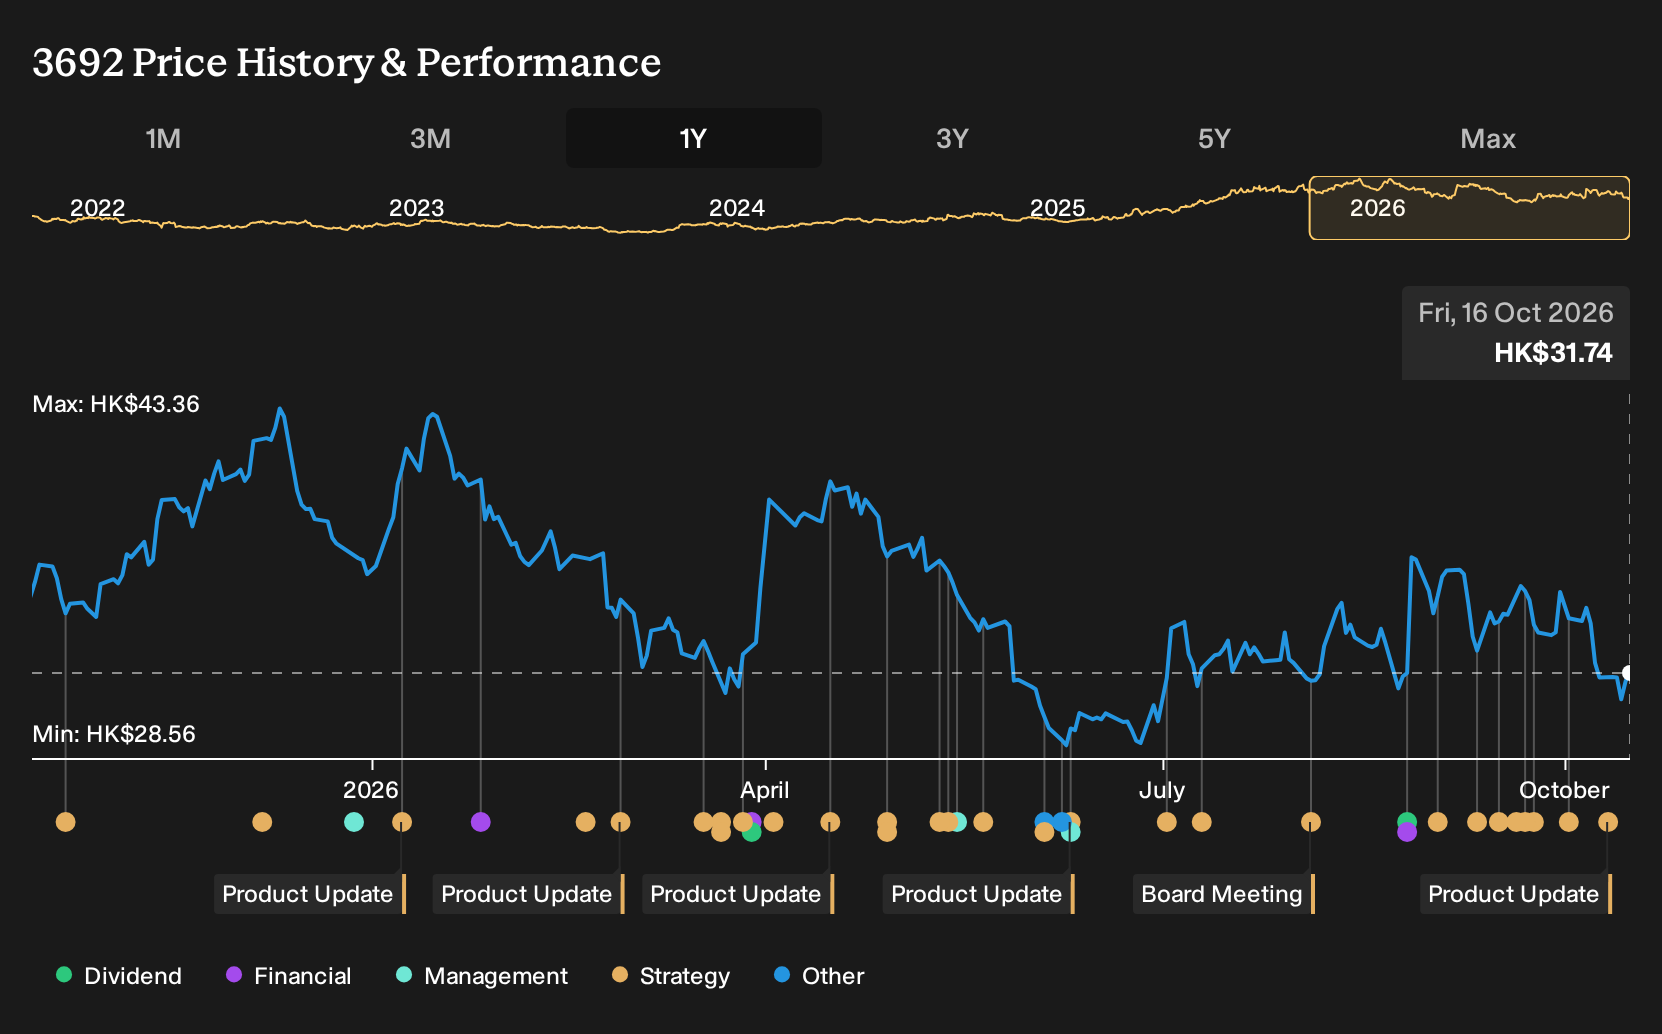
In the short term, the EU review becomes a fresh catalyst layered on top of existing earnings momentum, including 39.7% profit growth over the past year and a 42% net margin. The share price is down 12.9% year to date, yet analysts see upside and the stock trades 37.2% below one estimate of fair value, while carrying a P/E of 24.6x that is above sector and peer averages. The bigger question is whether those headline margins hold up once you factor in the high level of non cash earnings and the capital needed to support an ex China oncology franchise.
That said, there is a structural issue buried in the quality of those earnings that only really comes into focus when you look at ...
There's only one way to know the right time to buy, sell or hold Hansoh Pharmaceutical Group. Head to Simply Wall St's company report for the latest analysis of Hansoh Pharmaceutical Group's Fair Value.
Exploring Other Perspectives
Fair value estimates for Hansoh Pharmaceutical Group from 2 members of the Simply Wall St Community cluster tightly between CN¥47.82 and CN¥50.57, which already reflects a narrow spread of opinions. Those views pre date the EMA review news, so you now need to weigh fresh regulatory momentum against earlier assumptions and explore several alternative viewpoints.
Explore another Hansoh Pharmaceutical Group fair value estimate, including one that suggests it could be worth just HK$47.82!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hansoh Pharmaceutical Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hansoh Pharmaceutical Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hansoh Pharmaceutical Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hansoh Pharmaceutical Group?
If Hansoh Pharmaceutical Group has sharpened your focus on quality, it can help to scan a wider field of opportunities and see how other businesses stack up on income, value and balance sheet strength using the Simply Wall St Screener.
- For investors who want strong cash generation at a discount, start with a set of companies screened as 191 high quality undervalued stocks that may warrant a closer look.
- If income is your priority, you could review a curated group of potential income payers through a focused list of 214 dividend fortresses that meet a higher yield threshold.
- For those who care most about resilience, consider starting your research with a 233 resilient stocks with low risk scores that filters for businesses with more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com