


United Rentals (URI) Has The Market Watching, But What Is Behind It?
United Rentals (URI) is back in focus after fresh projections pointed to quarterly earnings of $13.75 per share on revenue of $4.67b, with analysts lifting their consensus profit forecast over the past month.
Recent trading has been choppy. United Rentals’ share price slipped 1.7% on the day and is down 2.5% over the past week, yet it still carries a 21.8% year to date share price gain and a five year total shareholder return of 190.4%, which may suggest longer term momentum even as short term sentiment cools around the latest earnings expectations.
Look beyond United Rentals and explore other industrial companies that analysts currently view as potential value opportunities with the 33 high quality undervalued stocks.
The share price has cooled after a strong year to date run, and analysts are leaning more positive on near term earnings. Does that setup still reward new United Rentals buyers at today’s valuation?
Most Popular Narrative: 19% Undervalued
Against a last close of $1,029.64, the most widely followed narrative for United Rentals points to a fair value of about $1,269.33, using an 8.68% discount rate and long term cash flow assumptions to bridge that gap.
The current valuation implies the share price does not fully reflect the combination of double digit rental revenue growth, historically high time utilization, and a balance sheet that management positions for both growth and ongoing capital returns. This narrative views the shares as undervalued and maintains a positive stance on the stock.
See why 14 investors see United Rentals as 19% undervalued.
Result: Fair Value of $1,269.33 (UNDERVALUED)
Still, if large megaprojects slow or ancillary and re-rent revenue continues to pressure margins, the bullish United Rentals narrative could unwind quickly.
Find out about the key risks to this United Rentals narrative.
Another View: What The Market Multiple Says About United Rentals
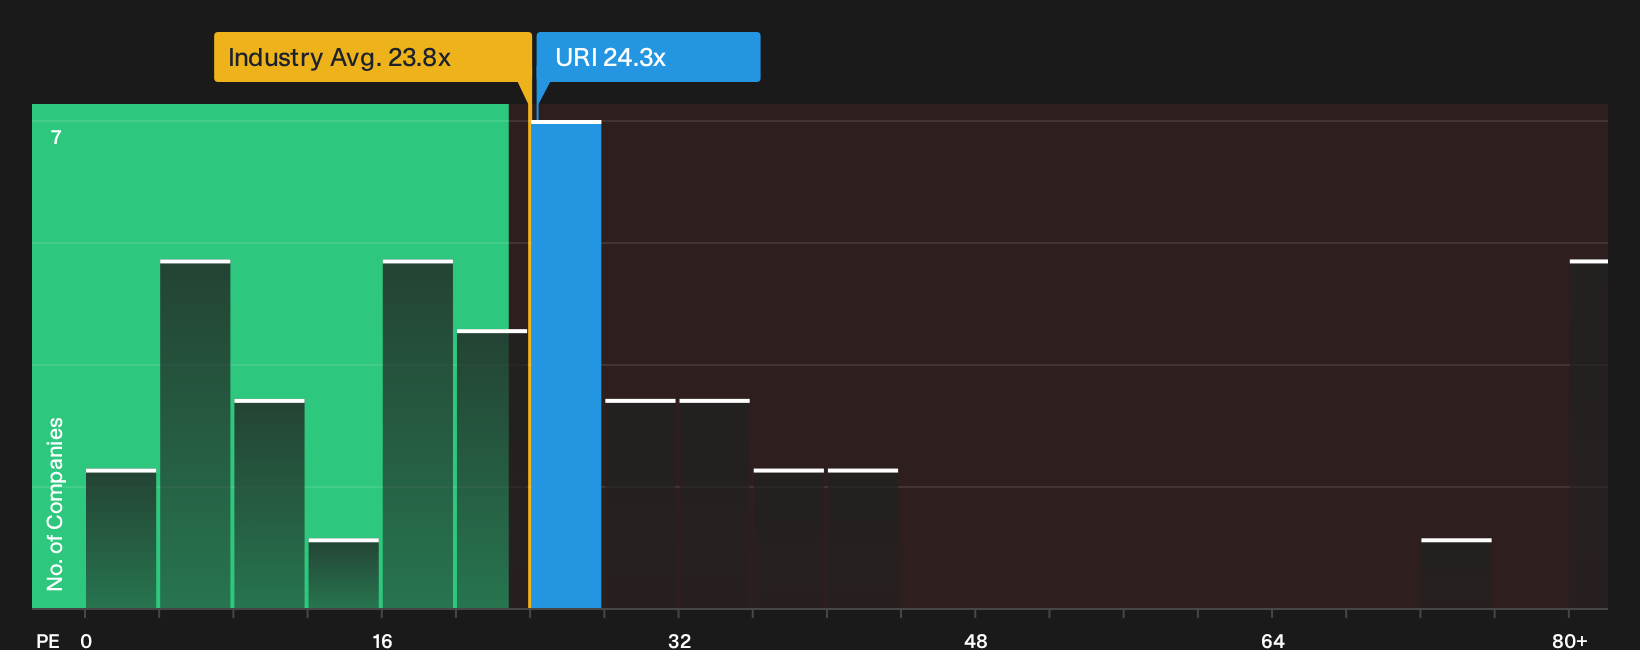
On the current numbers, United Rentals trades on a P/E of 24.3x, which is slightly higher than the US Trade Distributors industry at 24.2x, yet below its peer average of 29.9x and the fair ratio estimate of 30.8x that the market could move toward.
That mix of a small premium to the sector and a discount to both peers and the fair ratio points to some valuation risk if growth underwhelms, but also room for upside if earnings land closer to the more optimistic narrative. Which side of that trade-off you consider more realistic will depend on your own thesis.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around United Rentals is split, with enthusiasm about potential upside sitting alongside clear concern about downside risk. Move fast and check the data that matters most to you. To see both sides set out in one place and pressure test your own stance, review the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond United Rentals?
If United Rentals has sharpened your appetite for opportunities, do not stop here. Use the Simply Wall St Screener to quickly surface focused ideas that match your investing style.
- Target potential mispricings by scanning for companies that combine quality metrics with attractive valuations through the 33 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked opportunities by zeroing in on 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com