


Did Raised Outlook Just Shift Yaskawa Electric Stock Investment Narrative?
- YASKAWA Electric raised its full year revenue guidance to ¥600,000 million and slightly adjusted profit targets after reporting half year sales of ¥285,598 million and net income of ¥18,988 million for the period ended 31 August 2026.
- The company paired higher top line guidance with only modest changes to profit expectations, which suggests potential cost pressures or heavier investment needs behind the upgraded outlook.
- Next, the focus turns to how YASKAWA Electric's higher full year revenue guidance may influence the broader investment narrative around the stock.
What Is YASKAWA Electric's Investment Narrative?
To stay in YASKAWA Electric, you need to believe in a long runway for industrial automation, stable demand for servo motors and robots across autos, electronics and food, and a business that can keep funding heavy equipment and plant needs without eroding returns. The guidance tweak fits that story only partially. Management is pointing to higher full year sales of ¥600,000 million, yet operating profit guidance is now ¥57,500 million, slightly below the earlier target. That mix keeps the spotlight on execution, pricing discipline and cost control rather than a clean profitability upgrade.
In the near term, the key swing factors are whether YASKAWA Electric can convert its order book into higher margin shipments and whether robotics and motion control hold pricing in a competitive field. Half year revenue of ¥285,598 million and profit attributable to owners of parent of ¥18,988 million show a business with scale, but net margin compression to 6.3% from 10.7% means any extra growth can come with lower profitability if costs keep biting. The share price has been volatile over the past three months and the stock trades on a P/E of 31.6x, so even with analysts expecting earnings growth and a higher target price, sentiment is likely to hinge on how fast margins stabilise.
Even so, there is a less comfortable angle to YASKAWA Electric that starts with how it is funded and...
There's only one way to know the right time to buy, sell or hold YASKAWA Electric. Head to Simply Wall St's company report for the latest analysis of YASKAWA Electric's Fair Value.
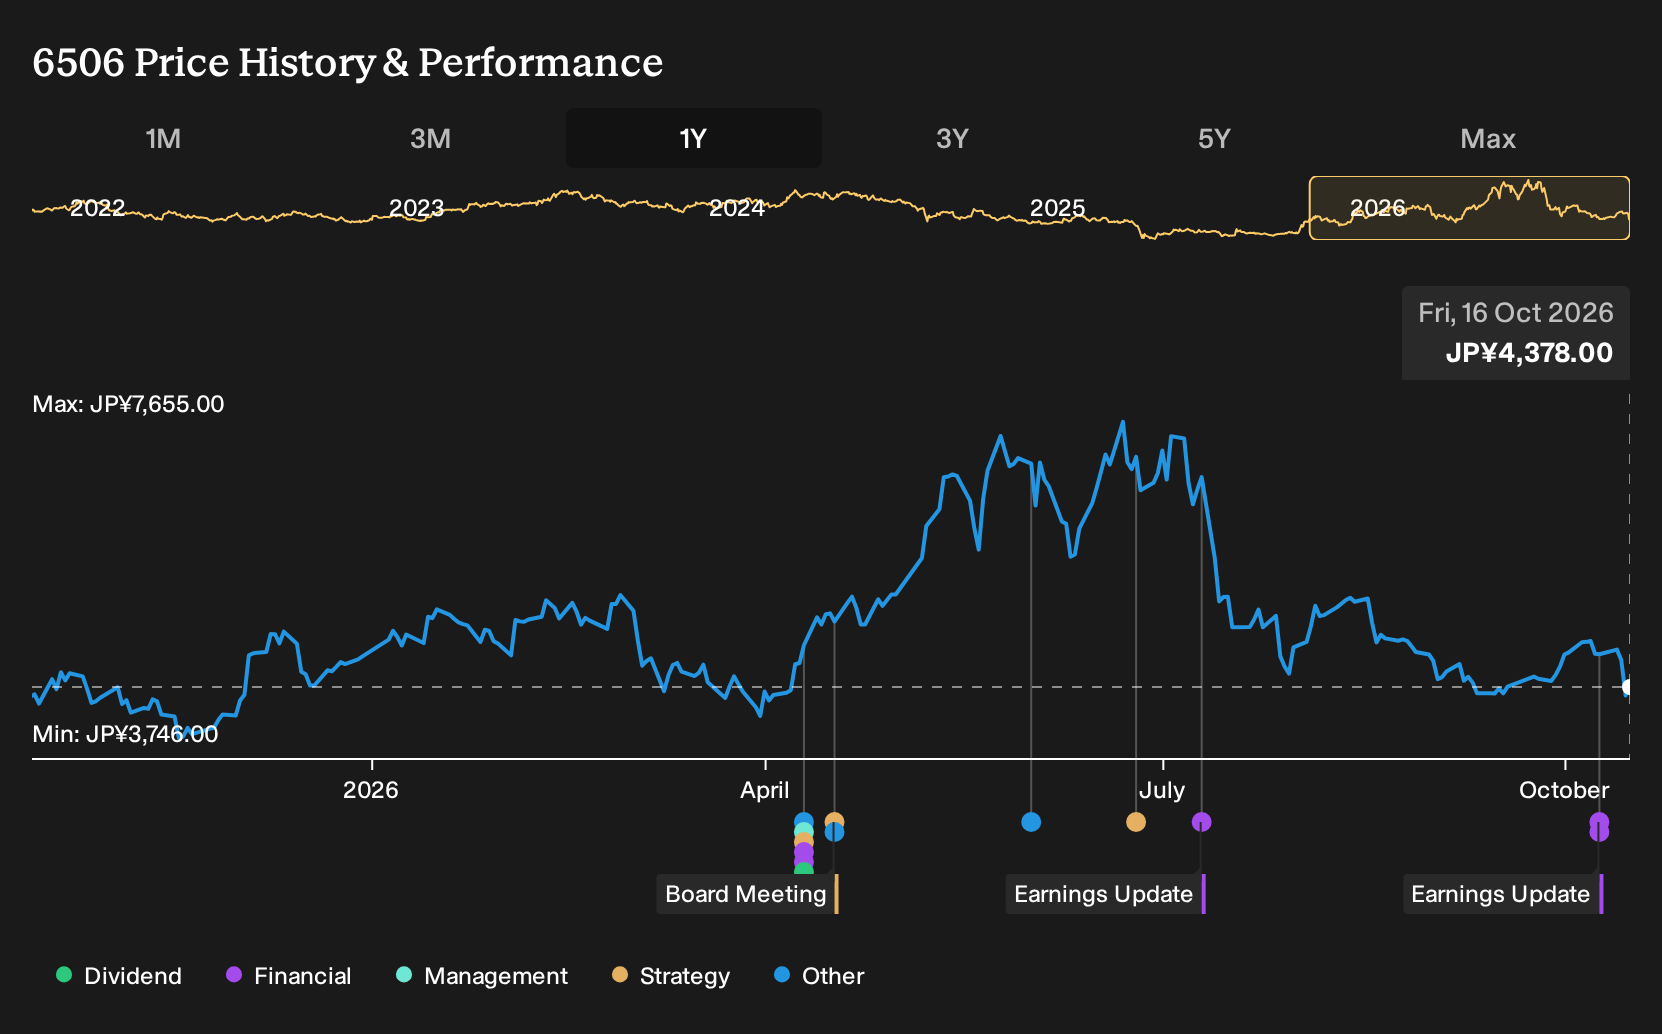
Exploring Other Perspectives
Fair value views on YASKAWA Electric from 2 private investors in the Simply Wall St Community stretch from ¥2,832 to ¥6,231, so opinions already span more than a 2x band even before the latest guidance revision. Use that spread as a prompt to scan how others weigh margin pressure against potential robotics demand.
Explore another YASKAWA Electric fair value estimate, including one that suggests as much as 42% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your YASKAWA Electric research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for YASKAWA Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate YASKAWA Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond YASKAWA Electric?
If YASKAWA Electric has sharpened your focus on where capital-intensive automation can lead, use that momentum to survey a wider field of opportunities with the Simply Wall St Screener. You can filter for balance sheet strength, income potential or underappreciated quality and build your own watchlist around the themes that matter most to you.
- If capital preservation sits high on your list, start with a 22 resilient stocks with low risk scores that pairs financial resilience with measured volatility.
- Income focused investors can zero in on reliability by scanning a curated set of 29 dividend fortresses that aim to combine yield strength with staying power.
- For those hunting for mispriced quality, broaden your radar with a hand-picked collection of 73 high quality undiscovered gems that may not yet be widely followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com