


Learn Why The Bull Case For Choice Hotels International Stock Could Change Following 600th Extended Stay Opening
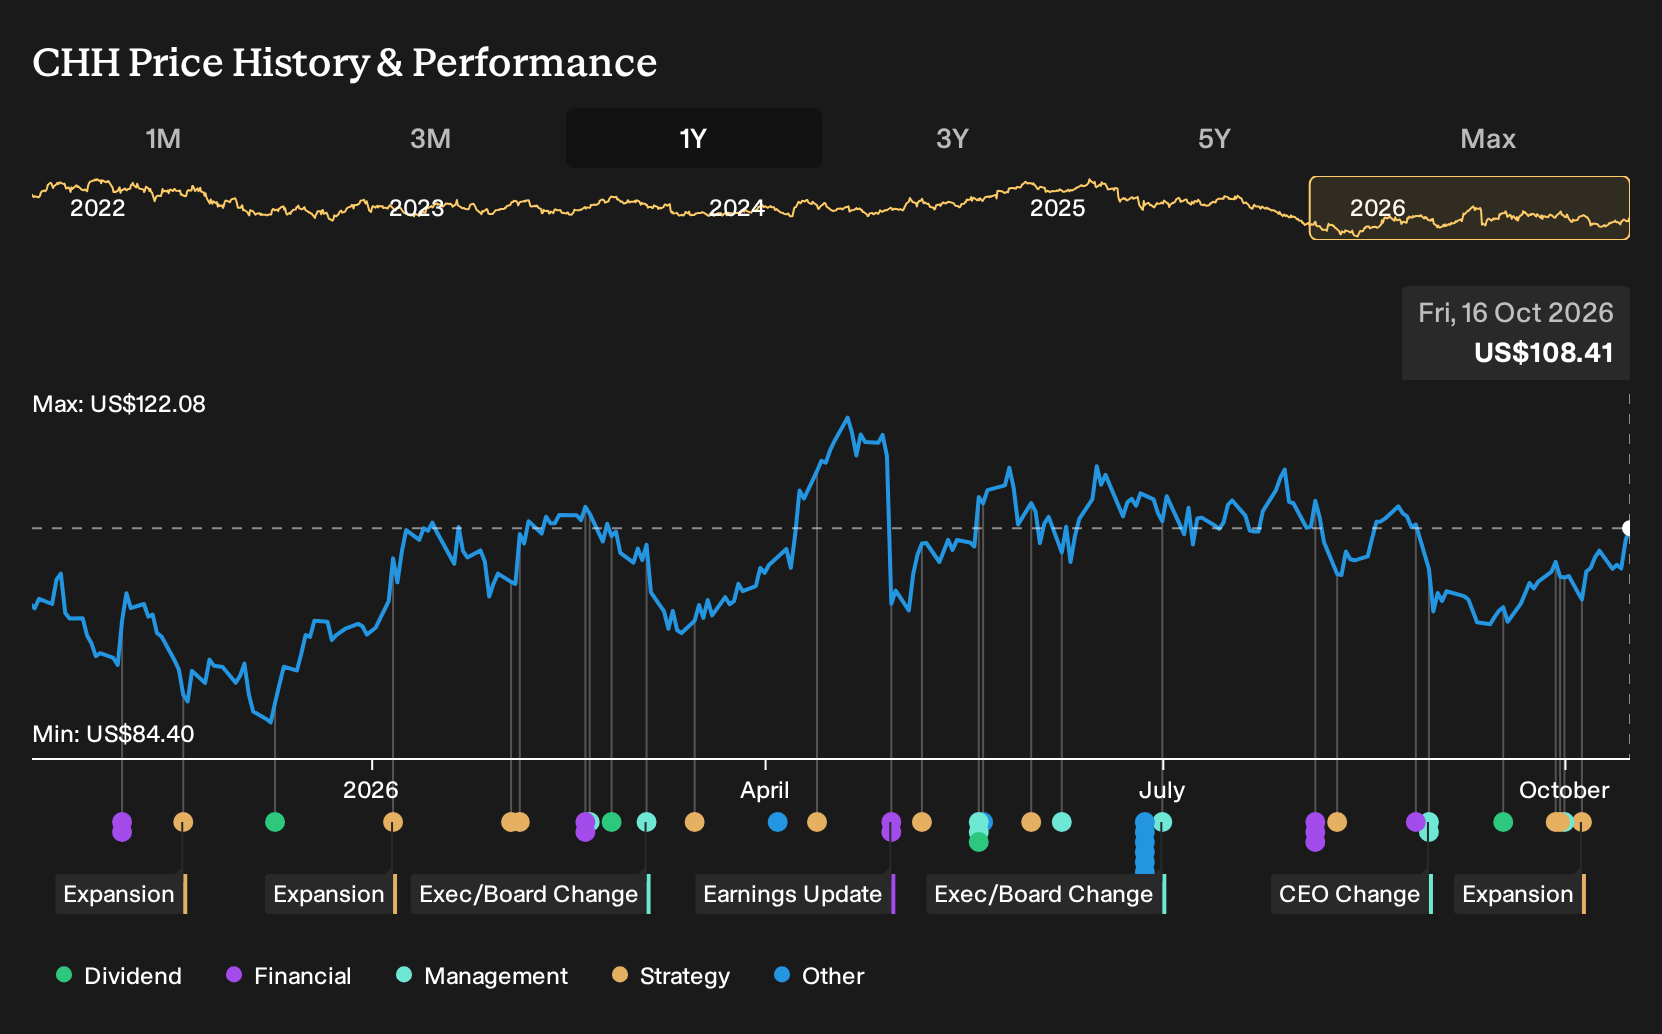
- Choice Hotels International has passed 600 extended stay hotels with the Everhome Suites Denver Airport, adding to a portfolio focused on economy and midscale guests and backed by a pipeline of nearly 30,000 rooms.
- This milestone in October 2026 highlights how Choice Hotels International is leaning into extended stay, where segment rooms have delivered 12 straight quarters of double digit growth and midscale properties are a growing focus.
- We will now look at how Choice Hotels International's 600th extended stay opening interacts with and potentially reshapes its investment narrative.
Choice Hotels International Investment Narrative Recap
To own Choice Hotels International, you need to believe its focus on franchised, value oriented brands and extended stay can keep supporting fee based revenue, even while U.S. RevPAR trails benchmarks and funding costs and taxes weigh on earnings. The 600th extended stay opening reinforces that core bet rather than changing it.
The most important near term swing factor remains whether Choice Hotels International can translate its extended stay scale and technology tools into better franchisee performance without stretching its balance sheet further. Debt coverage and returns on the asset light shift still look like the key risk that could blunt that upside.
The 600th extended stay hotel opening lines up tightly with the catalyst around mix shift into extended stay and midscale, which already represents more than 40% of the U.S. pipeline and has delivered 12 straight quarters of double digit room growth. This Denver property shows that pipeline converting into operating units.
That matters for the thesis because more rooms on franchise contracts can support royalty fee revenue, adjusted EBITDA and cash generation if occupancy holds up. The faster this extended stay footprint scales against the backdrop of higher interest expense and a trimmed EPS outlook, the more it can offset pressure from funding costs and moderate free cash flow margins.
Choice Hotels International's narrative projects US$1.9b revenue and US$404.4 million earnings by 2029. This implies 22.9% yearly revenue growth and about US$77.6 million earnings increase from US$326.8 million today.
Uncover why Choice Hotels International's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame extended stay as the big catalyst for Choice Hotels International. Before this 600th hotel opened, the bullish group was already modeling revenue growing about 31.5% a year and earnings of roughly US$392.0 million by 2029. You can see how this milestone might push those upbeat forecasts even further or prompt others to reassess the upside.
Explore another Choice Hotels International fair value estimate, including one that suggests as much as 6% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Choice Hotels International research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Choice Hotels International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Choice Hotels International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Choice Hotels International?
If the Choice Hotels International story has you thinking about where recurring demand, balance sheet strength and income potential intersect, the Simply Wall St Screener can help you scan for stocks that fit your own checklist in minutes.
- Prefer rock solid finances over drama? Start with a list of solid balance sheet and fundamentals (25 results) to narrow in on businesses built to handle pressure.
- Want resilient performance with limited downside? Use a 32 resilient stocks with low risk scores that filters for companies with more stable risk profiles.
- Hunting for future leaders before the crowd catches on? Work through a 20 high quality undiscovered gems that highlights under-followed stocks with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com