


Earnings Optimism Altering The Investment Case For Sony Stock
- Sony Group recently introduced the ECM-AX10 smartphone microphone, certified for Eclipsa Audio and priced at US$249.99 / C$349.99, offering ambisonics, binaural and stereo recording modes through a lightweight USB-C setup.
- The ECM-AX10, paired with Sony’s Spatial Audio Video Tool app, keeps the entire spatial audio video workflow on a smartphone, which deepens the group’s push into creator focused, higher value digital tools.
- We will now examine how Sony Group’s push into smartphone based spatial audio creation through the ECM-AX10 could influence its investment narrative.
Scan for other audio and creator focused plays showing similar momentum by exploring our hand picked 73 high quality undiscovered gems.
Sony Group Investment Narrative Recap
Sony Group appeals to shareholders who support a shift toward higher margin digital ecosystems, content IP and creator tools, with hardware acting more as an enabler rather than the main profit pool. The ECM-AX10 fits that story but is small in the context of group earnings, so the near term share driver remains execution in PlayStation, music, pictures and image sensors.
The biggest immediate swing factor is whether Sony Group can keep lifting profitability while TV, smartphone and other hardware markets face structural pressure. Geopolitics and trade rules still threaten component costs and margins. Legal exposure around digital ownership and AI training also hangs over the medium term earnings profile.
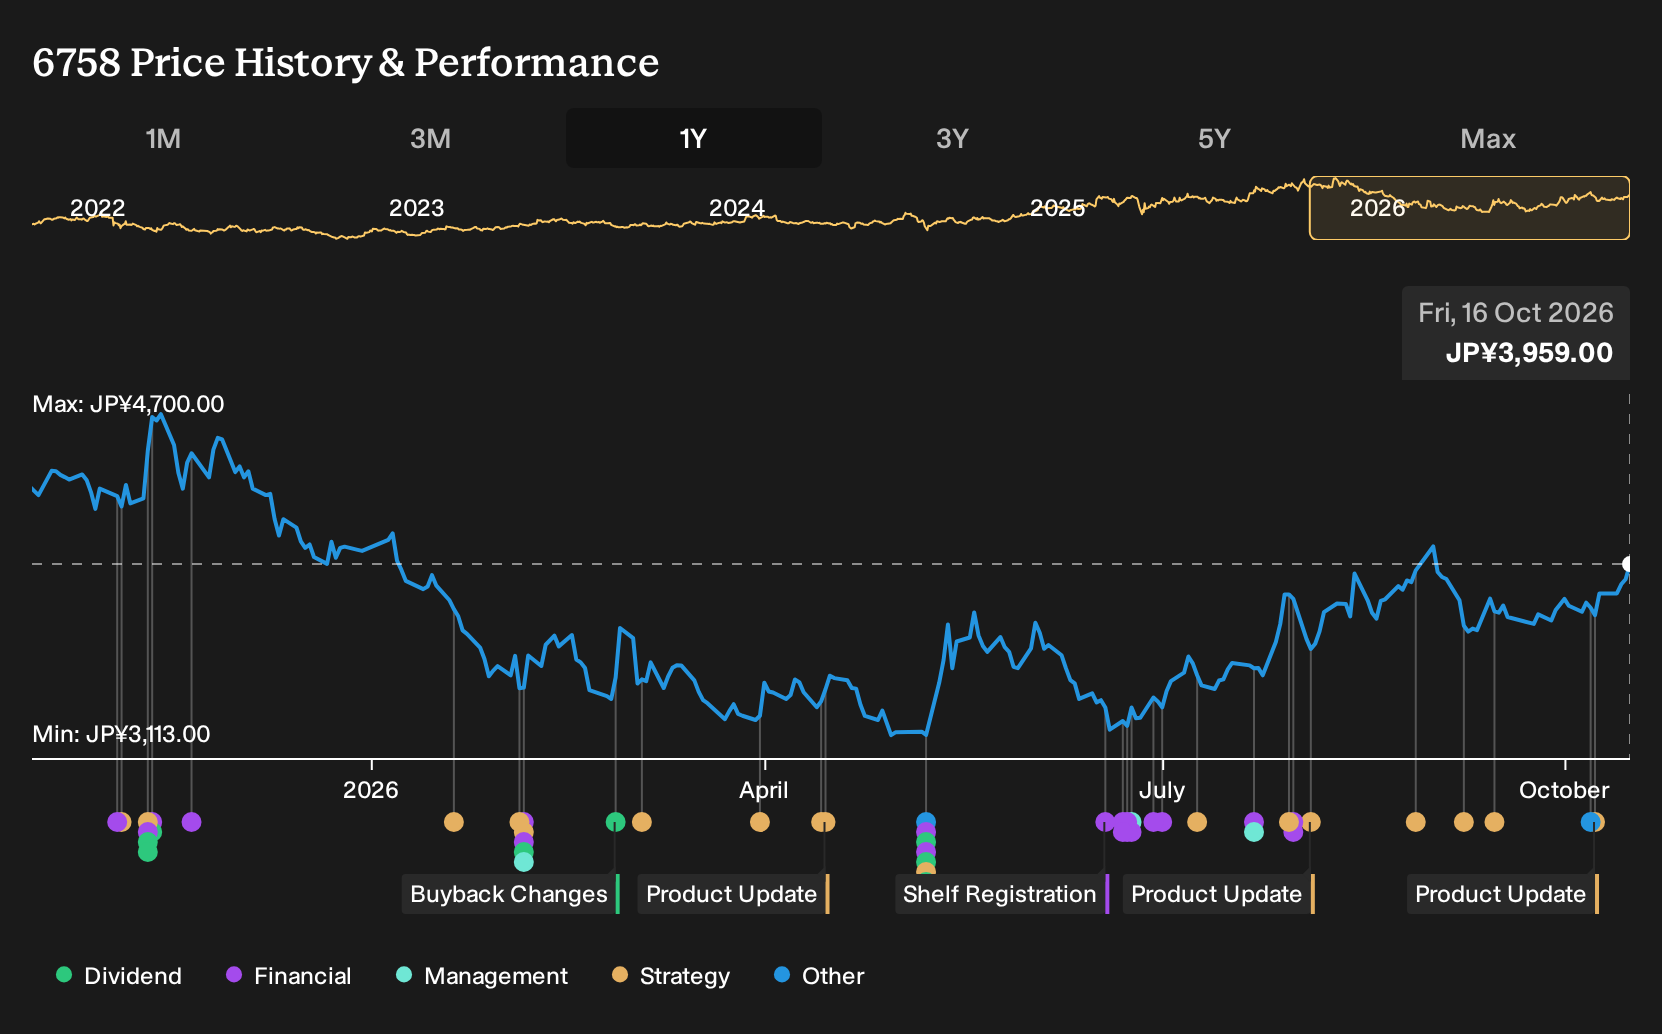
The fresh share buyback update is more relevant to catalysts than the ECM-AX10 itself. Sony Group repurchased 74,473,700 shares for approximately ¥263.4b, equal to 1.26% of the company. That reduces the share count at the margin and can make any future profit growth translate more directly into earnings per share.
For you as an investor, that capital return sits alongside a business that, according to analyst estimates, is expected to grow earnings at 7.5% a year, even as revenue expansion is more modest. The buyback does not address core risks around hardware headwinds or legal issues, but it gives management one more lever as Sony Group expands further into digital services, creator centric devices and content driven cash flows.
What The Sony Group Forecasts Assume
Sony Group's narrative projects ¥13,805.5b revenue and ¥1,454.9b earnings by 2029. This implies 2.8% yearly revenue growth and an earnings increase of about ¥340.9b from ¥1,114.0b today.
Uncover why Sony Group's fair value indicates a 22% potential upside to its current price before the gap to market expectations narrows.
Exploring Other Perspectives
Some of the most optimistic analysts anchor their Sony Group view on a different catalyst entirely. They focus on higher end image sensor demand, with prior forecasts pointing to ¥14,495.8b in revenue and ¥1,672.6b in earnings by 2029. The ECM-AX10 sits right in that creator tool story, so those narratives may shift as this product finds its footing.
Explore 2 other Sony Group fair value estimates, including one that suggests potential upside of up to 22% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sony Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sony Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sony Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sony Group?
Once you have a handle on Sony Group, it can be useful to compare its profile with other opportunities that share some of the same strengths but have very different risk and return trade offs.
- If you want potential growth with a strict focus on balance sheet strength, filter for companies that pass tough debt and liquidity checks using our list of solid balance sheet and fundamentals (21 results).
- For investors who care most about paying a fair price for quality, narrow the market down to companies trading below their estimated worth through the 14 high quality undervalued stocks.
- If your priority is steadier income, concentrate on businesses that offer higher yields and have more robust payout profiles by scanning our 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com