


Methanex (TSX:MX) Wins Top Buy Upgrades, Is The Stock Still Cheap?
Recent analyst upgrades have put Methanex (TSX:MX) back in focus after earnings estimates moved higher and valuation ratios like Forward P/E and P/B began to screen as inexpensive compared with sector peers.
Recent upgrades and valuation commentary are arriving after a strong run in Methanex shares, with the stock now at CA$91.92 following a 19.8% 90-day share price return and a 64.2% year-to-date share price gain, reflecting building momentum and a 95.8% total shareholder return over the past year.
Spot potential value setups beyond Methanex by scanning our hand picked list of 5 high quality undervalued stocks, which currently combines inexpensive valuation with stronger quality signals.The share price has sprinted ahead, yet fair value estimates still sit well above CA$91.92. Is Methanex now stretched, or has the rerating only partially closed the gap?
Most Popular Narrative: 1% Overvalued
The most followed narrative on Methanex pegs fair value at CA$91.07, almost identical to the latest CA$91.92 close. This leaves very little implied margin either way and puts the focus squarely on how future execution and cash generation line up with these assumptions.
Methanex expects methanol demand to grow in 2025, driven by traditional chemical and energy applications, which could boost revenues. Increased production at key facilities, such as Geismar and Chile, along with improved operational efficiency, positions the company to capitalize on favorable pricing, potentially enhancing net margins and earnings.
See why 15 investors see Methanex as 1% overvalued.
Result: Fair Value of CA$91.07 (OVERVALUED)
Still, the story can break if contracted gas supplies in regions like Chile or New Zealand tighten again, or if OCI integration drags on margins and cash generation.
Find out about the key risks to this Methanex narrative.
Another View: Methanex Through The SWS DCF Lens
The earlier consensus narrative sees Methanex as roughly fairly priced around CA$91.07. The SWS DCF model points in the opposite direction. On those cash flow assumptions, fair value lands at CA$173.10, which puts the current CA$91.92 quote at a steep discount and raises the question of whether the crowd is underestimating long term cash generation.
Look into how the SWS DCF model arrives at its fair value.
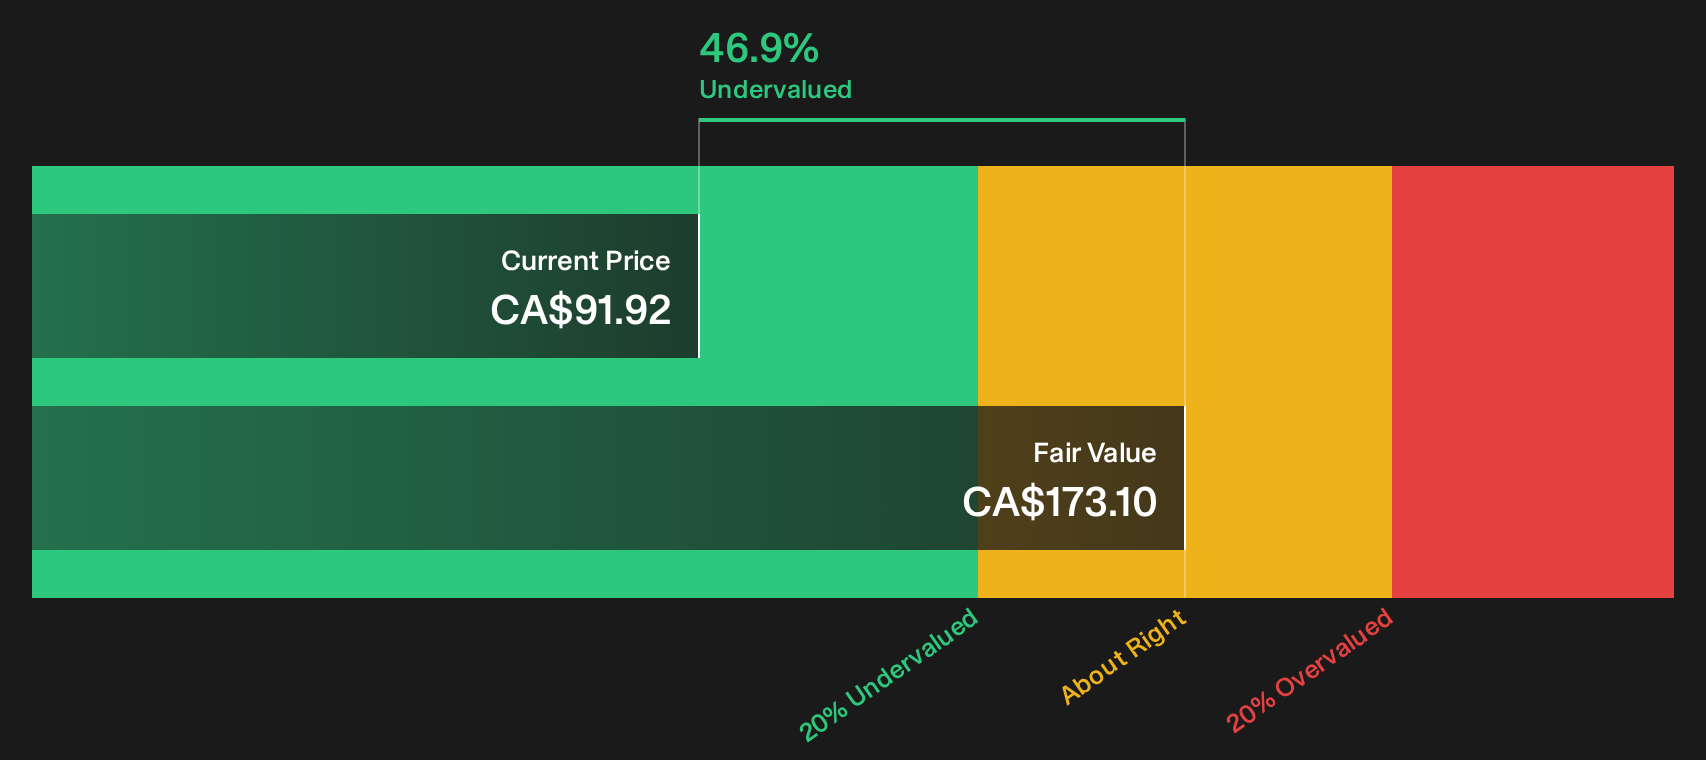
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Methanex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Methanex leave you torn, use that tension as a prompt to move quickly and check the underlying numbers yourself. To see how current opportunities balance against the main issues on investors' minds, review the 2 key rewards and 4 important warning signs.
Looking for more Methanex sized investment ideas?
If Methanex has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more ways to put cash to work intelligently.
- Target resilient balance sheets and steady fundamentals by running a focused search built around our list of solid balance sheet and fundamentals (8 results).
- Hunt for quality at sensible prices by filtering opportunities using the 5 high quality undervalued stocks that blend stronger finances with appealing valuations.
- Spot fresh opportunities before they hit the spotlight by scanning the 10 high quality undiscovered gems that already show strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com