


Calumet (CLMT) Redeems $150 Million Of Notes On A Valuation View Above Fair Value
Calumet (CLMT) just moved to retire $150 million of its 9.75% Senior Notes due 2028, as part of a broader push since July 2026 to cut debt and trim interest costs.
Debt reduction now sits alongside a powerful run in Calumet’s equity, with the share price at $57.75 after a 90-day share price return of 34.84% and a 1-year total shareholder return of 217.48%, suggesting momentum has been strong over both shorter and longer horizons.
Scan beyond Calumet and look for other refiners and fuel marketers showing strong momentum and balance sheet improvements by reviewing the curated 33 high quality undervalued stocks.
Calumet now trades above the average analyst target, yet screens at a steep intrinsic discount. Is the market being fairly cautious about its debt track record and losses, or is it mispricing the recent cleanup move?
Most Popular Narrative: 8% Overvalued
Against a fair value of $53.40 at a 7.25% discount rate, Calumet at $57.75 is priced above the most followed narrative, which hinges on renewables expansion and margin improvement.
The MaxSAF 150 project is on track to start up in the first half of 2026, enabling Calumet to produce 120-150 million annual gallons of sustainable aviation fuel (SAF) at relatively low capital costs. This is expected to capture premiums of $1-$2/gallon over renewable diesel and tap into surging mandated and voluntary SAF demand globally. This is likely to drive a material step-up in revenues and EBITDA margin expansion once operational.
See why 5 investors see Calumet as 8% overvalued.
Result: Fair Value of $53.40 (OVERVALUED)
Still, the story around Calumet can shift quickly if regulatory support for renewables weakens, or if high debt and legal scrutiny start to constrain flexibility.
Find out about the key risks to this Calumet narrative.
Another View: What Multiples Say About Calumet
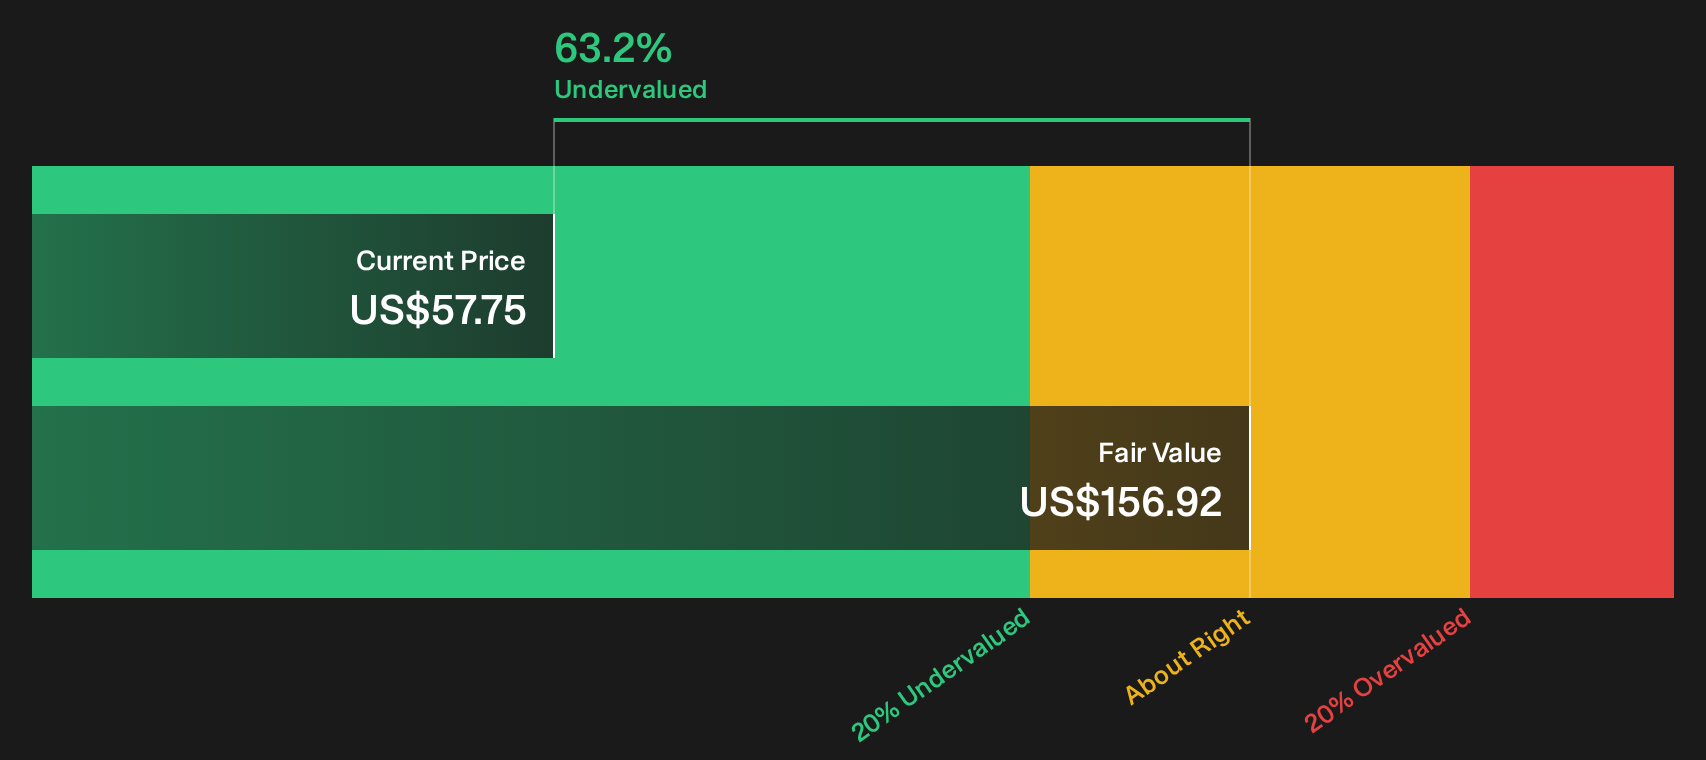
The Simply Wall St intrinsic value model flags Calumet as materially undervalued, with the shares trading 63.2% below an estimate of future cash flow value at $156.92 per unit price. That sits awkwardly next to the 8% overvaluation narrative. Which lens do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Calumet so far, or a clear setup hiding in plain sight? Use the full picture of risks and upsides to sharpen your own stance with 3 key rewards and 1 important warning sign.
Looking for more Calumet-sized opportunities?
If Calumet has your attention, do not stop with a single ticker. Broaden your watchlist with fresh ideas sourced directly from Simply Wall St screeners tailored to different priorities.
Use these focused lists to pressure test your thinking, compare risk profiles, and spot opportunities you might otherwise miss while the market looks elsewhere.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that filters for financial strength upfront.
- Hunt for potential mispricings by working through the 20 high quality undiscovered gems before the crowd pays attention to the same opportunities.
- Dial down volatility in your portfolio by focusing on the 32 resilient stocks with low risk scores that screens for stocks with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com