


How Investors May Respond To Starbucks (SBUX) Dividend Raise
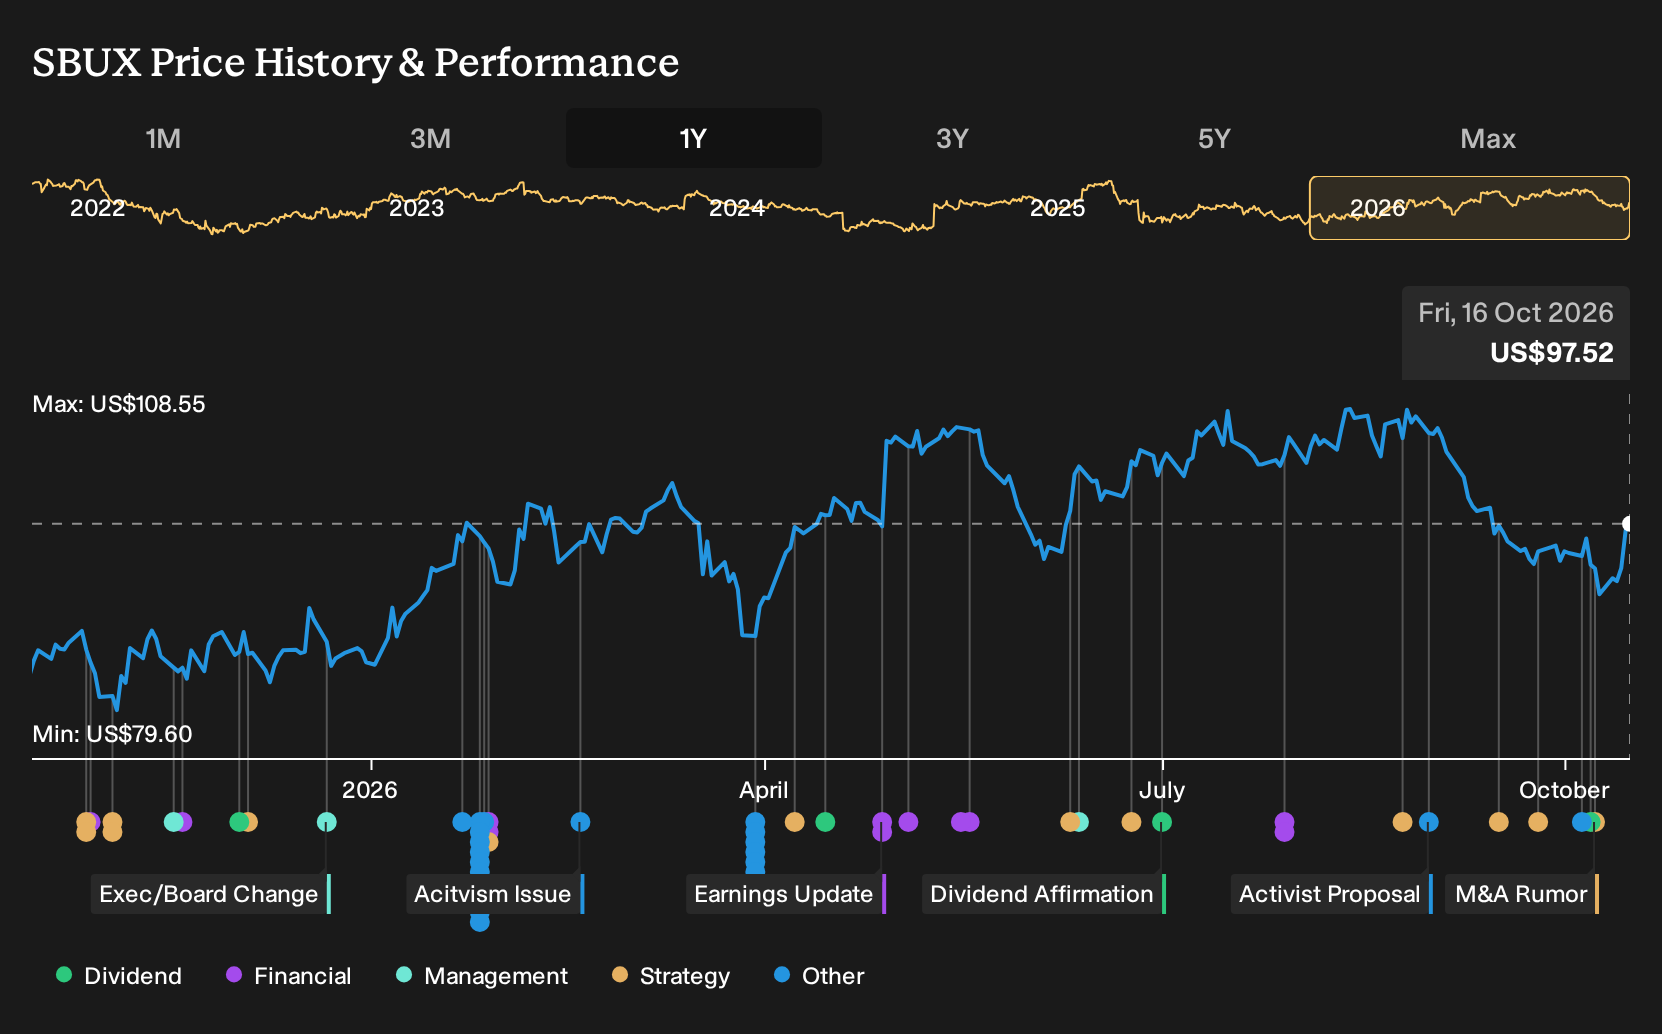
- Starbucks raised its quarterly dividend to $0.63 per share in October 2026, reported Q3 2026 comparable store sales growth of 7.9%, and GAAP earnings per share that were 86% higher than a year earlier. At the same time, the company was linked to rumors about a potential Chipotle takeover and faced a fresh class action over sugar free drinks.
- The new $2.52 annualized dividend equates to an estimated payout ratio near 97% of Starbucks 2026 earnings guidance midpoint. This highlights how much of the company’s current cash generation is being directed back to shareholders rather than reserved for reinvestment flexibility.
- We will look at how Starbucks dividend increase and high payout ratio reshape the investment narrative built around margin improvement.
Scan how Starbucks’ mix of high payouts, legal questions and M&A rumors compares with other mature consumer stocks by reviewing our curated 32 resilient stocks with low risk scores for diversification ideas.
Starbucks Investment Narrative Recap
To own Starbucks, you need to believe the Back to Starbucks plan can lift margins from today’s levels and support earnings growth without overstretching the balance sheet. The most important short term catalyst is execution on store remodels, cost savings and labor productivity. The Chipotle rumor does not change that core operational debate in a meaningful way.
The biggest near term risk sits in rising complexity, from unionisation pressures to new legal actions like the sugar free lawsuit that could add costs or distract management. Any large deal on top of this, if it ever materialised, would simply amplify those execution and integration risks.
The dividend increase to an annualised US$2.52 per share is the cleanest data point to work with here. With an estimated payout ratio near 97% of Starbucks 2026 earnings guidance midpoint, the business is choosing to return most current cash flows rather than retain a larger buffer for flexibility.
That decision matters for catalysts. High payouts leave less room to absorb legal settlements, fund aggressive store uplift, or support any sizeable acquisition from internal cash. For you as a shareholder, the trade off is clear. Progress on the Back to Starbucks initiatives has to come mainly from better operations, not from writing ever bigger cheques.
What Starbucks’ Analyst Assumptions Really Imply
Analysts are effectively telling you that Starbucks needs both steadier revenue growth and a much stronger earnings engine to support today’s narrative. The forecasts tie directly back to the Back to Starbucks plan, because higher productivity and better store level economics are what have to drive those future profit margins.
On the top line, the consensus view builds in 3.7% yearly revenue expansion over the next three years. That is not an explosive growth story. It is a measured pace that leaves most of the heavy lifting to margin improvement rather than raw sales volume.
Earnings expectations are more demanding. The analyst set points call for profit to move from US$2.0b today to US$4.7b by 2029. That is roughly a 2.4x step up in earnings, with a wide spread between the most bullish estimate of US$6.3b and the most cautious at US$4.2b, which signals genuine disagreement about how far the Back to Starbucks plan can go.
That profile also assumes Starbucks pushes its net margin higher as cost savings and operational fixes feed through. The projections map out an increase in profit margin from 5.2% today to 11.0% in three years. For you as an investor, the key question is whether the combination of remodeling, labor changes and technology upgrades can realistically bridge that gap without adding fresh risk to the story.
Starbucks' narrative projects US$42.8b revenue and US$4.7b earnings by 2029. This requires 3.7% yearly revenue growth and roughly a 2.4x earnings increase from current earnings of US$2.0b.
Uncover how Starbucks' fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view zooms in on Starbucks’ remodel and restructuring bill as the key risk. The most cautious analysts were already assuming about US$42.5b of revenue and US$4.9b of earnings by 2029 before this dividend move and Chipotle rumor surfaced. That is a tighter, more skeptical story. Use it as a reminder that forecasts can shift and that your own judgment matters too.
Explore 3 other Starbucks fair value estimates, including one that suggests it could be worth just $99.67.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Starbucks research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Starbucks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Starbucks' overall financial health at a glance.
Looking For More Ideas Beyond Starbucks?
If you want to put Starbucks in context and build a broader watchlist, the Simply Wall St Screener can help you compare it with other businesses that share similar qualities or offer a different balance of growth, income, and resilience.
- For investors who care most about stability and capital preservation, scan a curated 32 resilient stocks with low risk scores that keep risk scores on the lower side.
- If you prefer companies with stronger cushions on the balance sheet, check out a list of solid balance sheet and fundamentals (25 results) that already clear fundamental checks.
- Income focused investors can review a hand picked 8 dividend fortresses that combine higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com