


Will Stronger Earnings Expectations Change Popular's (BPOP) Narrative
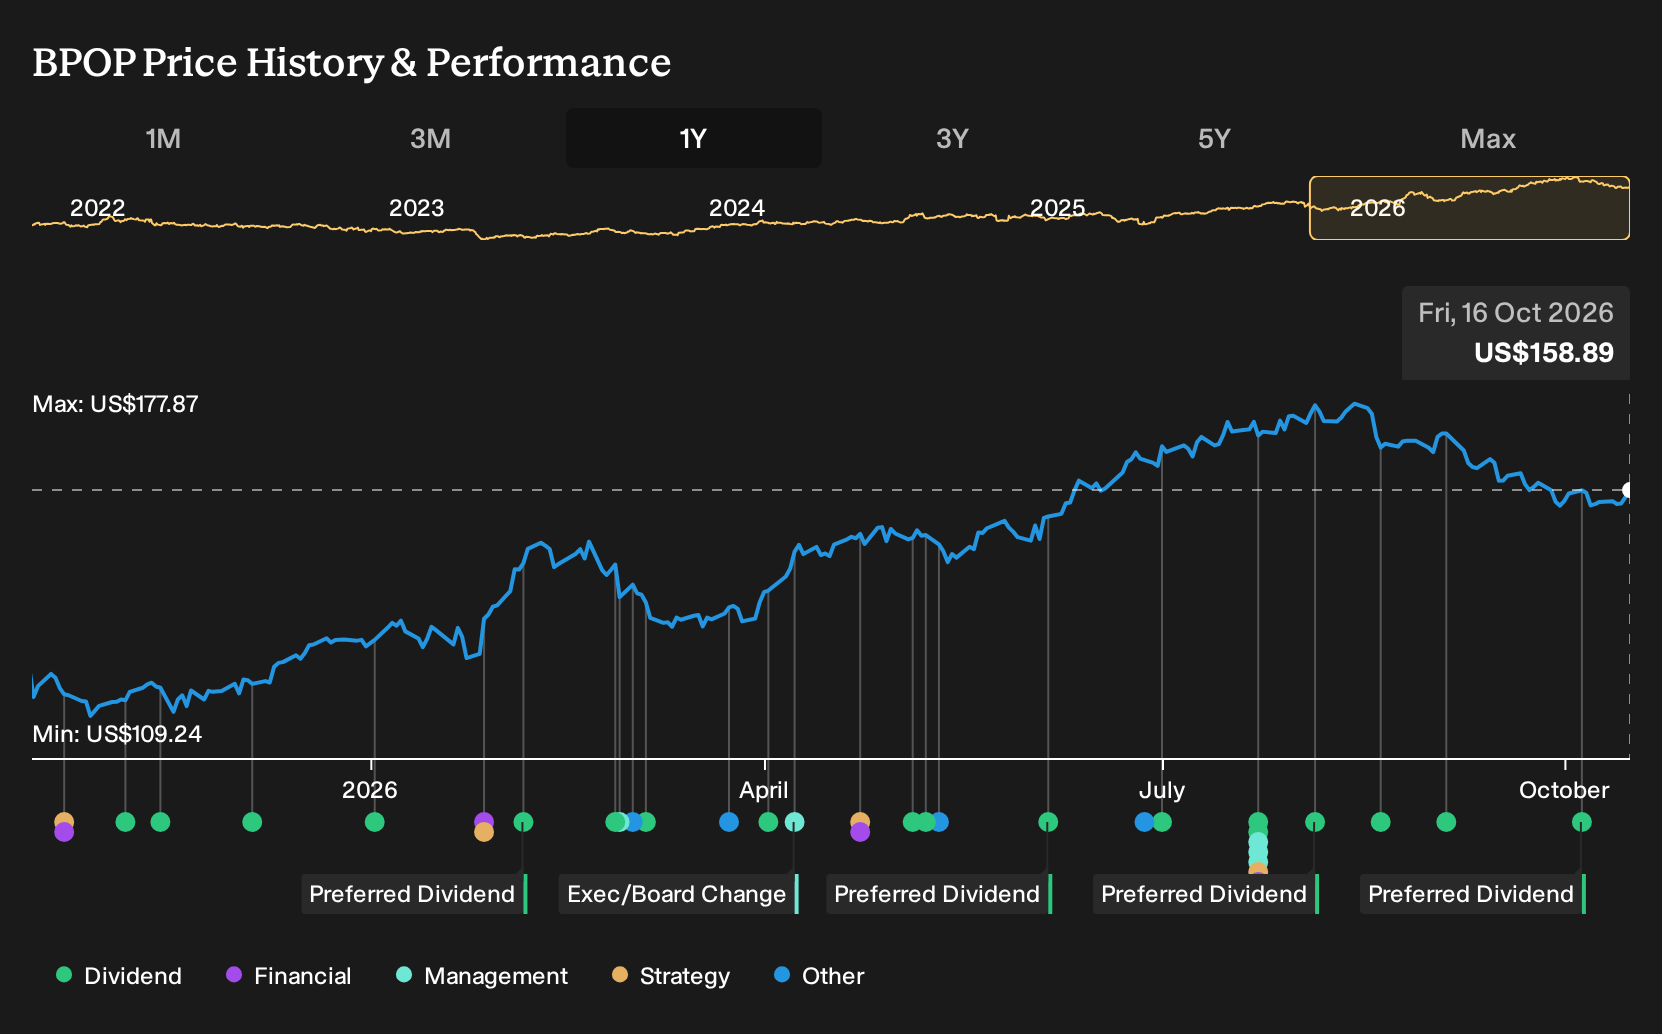
- Popular, Inc. announced monthly cash payments on its preferred instruments, including a US$0.132813 dividend on its 6.375% Non-Cumulative Monthly Income Preferred Stock, Series A, and a US$0.127604 distribution on its 6.125% Cumulative Monthly Income Trust Preferred Securities, both paid on November 2, 2026, to holders of record on October 15, 2026.
- These preferred distributions sit alongside a common equity profile that features an above-industry dividend yield and a multiyear pattern of dividend increases. Together, these elements illustrate how Popular uses its capital position to appeal to income-focused investors while analysts evaluate earnings and revenue for the September 2026 quarter.
- Attention now turns to how Popular's dividend yield and track record could influence the investment narrative that investors rely on.
Scan beyond Popular and compare its income profile with hand-picked 8 dividend fortresses that also focus on consistent cash returns to shareholders.
Popular Investment Narrative Recap
To own Popular, you need to be comfortable with a bank that leans heavily on Puerto Rico for deposits and lending, while trying to squeeze more earnings from digital platforms, AI driven efficiency and a refocused U.S. operation. The preferred dividend news does not materially change that near term story. The key near term swing factor is how September quarter credit quality and loan demand look against that backdrop.
The biggest current risk sits in that same geographic concentration. Any setback in the local economy, tourism or large commercial credits could pressure profitability, even with efficiency programs pointing to future savings. Income investors get support from the dividend profile, but capital preservation still depends on execution in Puerto Rico and the mainland business.
The fresh piece of news that matters most here is the confirmation of monthly cash dividends on Popular’s preferred securities. Those payouts, alongside a higher than industry dividend yield on the common stock, indicate that capital levels currently allow for steady cash returns while management invests in digital infrastructure and efficiency projects.
For you as a shareholder, the relevance is practical. Reliable preferred and common dividends can make it easier to wait for catalysts such as cost savings from AI programs, branch upgrades and treasury platforms to work through earnings. The trade off is that concentration in Puerto Rico, modest expected revenue growth and any bump in credit losses could test how long that balance between investment, risk and shareholder distributions holds.
Popular Earnings And Valuation Setup
Popular's narrative projects US$3.9b revenue and US$1.1b earnings by 2029. Analysts are factoring in 8.8% yearly revenue growth and an earnings increase of about US$132m from US$967.7m today to reach that 2029 consensus level.
Uncover how Popular's fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$196.7 to about US$377, which shows how far apart retail opinions on Popular can be. Those views brush past key issues like Puerto Rico concentration risk and local economic resilience. Use that gap to pressure-test your own thesis against several competing viewpoints.
Explore another Popular fair value estimate, including one that suggests as much as 137% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Popular research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Popular. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Popular's overall financial health at a glance.
Looking For More Ideas Beyond Popular?
If Popular has sharpened your thinking on income and valuation, use that momentum to scan a wider field of opportunities. The Simply Wall St Screener lets you quickly filter for the mix of quality, income and resilience that fits your own playbook.
- If you want potential mispricing combined with resilient fundamentals, start by reviewing our 33 high quality undervalued stocks that pass both quality and valuation checks.
- If capital preservation matters most to you, focus on our 32 resilient stocks with low risk scores that aim for steadier balance sheets and milder volatility through the cycle.
- If you prefer to fish where fewer investors are looking, scan through our 20 high quality undiscovered gems with strong underlying metrics but lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com