


Production Update Might Change The Case For Investing In Parex Resources Stock
- Parex Resources reported average production of 84,500 boe/d for September 2026 and 83,259 boe/d for the third quarter, and reiterated its production targets for the second half and full year 2026.
- The production figures sit within the reiterated guidance ranges, which gives investors a clearer read on current operating consistency and future output planning.
- The focus now turns to how Parex Resources' reiterated 2026 production guidance shapes the broader investment narrative around the business.
Scan beyond Parex Resources and compare its production profile with a hand-picked list of solid balance sheet and fundamentals (8 results) that also report consistent output and disciplined capital management.
What Is Parex Resources' Investment Narrative?
The big idea investors have to buy into with Parex Resources is straightforward. You need to believe the producer can keep turning its Colombian oil and gas acreage into reliable barrels, while staying disciplined on spending and cash returns. The latest production update, with September and third quarter volumes slotting inside reiterated 2026 guidance, points to execution that is tracking to plan rather than resetting it. In the short term, that keeps the conversation centered on well performance, decline management, and how capital is allocated across the Llanos, Magdalena, and Putumayo blocks rather than on any sudden operational surprise.
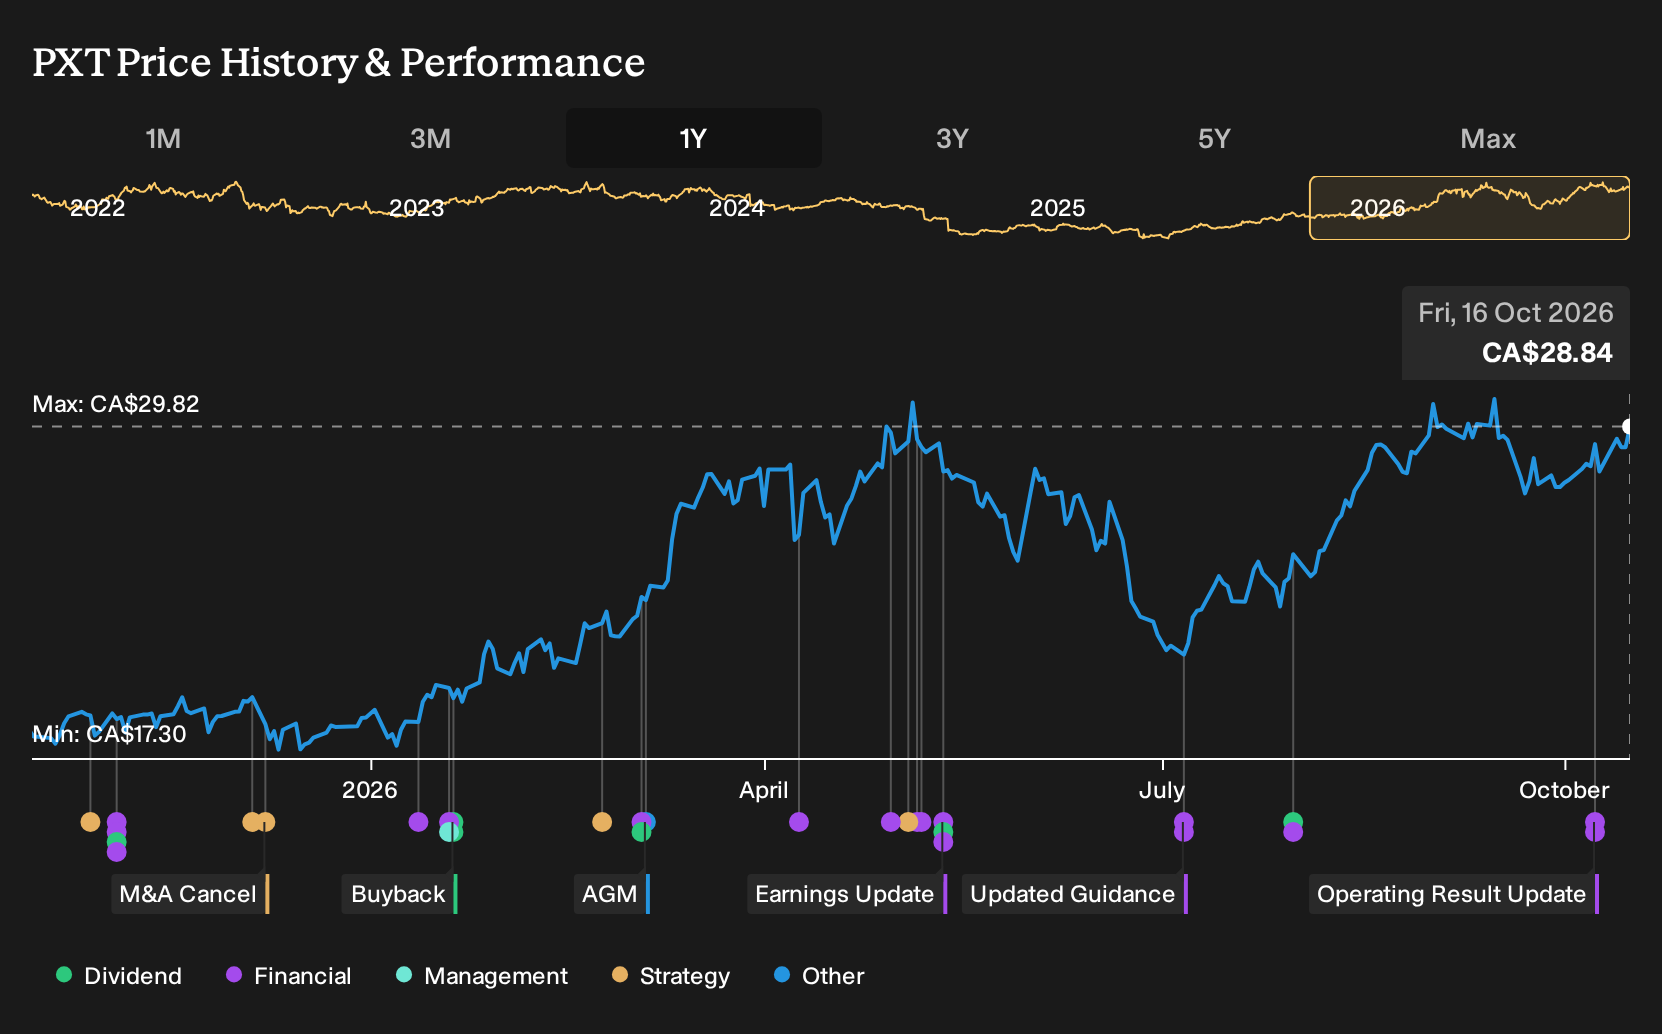
Where this matters most is in the tension between strong recent financial markers and flagged risks around future earnings and cash coverage. The stock has delivered a 73% total return over the past year, trades on a P/E of 3.4x versus an estimated fair multiple of 7.5x, and currently carries high net profit margins of 55%. At the same time, forecasts point to revenue growth with declining profits, a dividend that is not well covered by free cash flow, and a high share of non cash earnings. The reaffirmed production outlook slots into that picture as operationally reassuring, without really changing the key debate around how durable those economics look a few years out.
That said, before treating Parex Resources as a simple production plus valuation story, it is worth pausing on ...
There's only one way to know the right time to buy, sell or hold Parex Resources. Head to Simply Wall St's company report for the latest analysis of Parex Resources's Fair Value.
Exploring Other Perspectives
One bullish twist on Parex Resources focuses on how much more earnings power some analysts saw even before this production update. The most optimistic group was pencilling in revenue of $2.9b and earnings of $542.1 million by about April 2029, with 47.6% annual revenue growth. Those forecasts may shift as you factor in the latest guidance reaffirmation, so treat them as a starting point and compare several viewpoints before deciding how this story fits your portfolio.
Explore 5 other Parex Resources fair value estimates, including one that suggests up to 801% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Parex Resources research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Parex Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parex Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Parex Resources?
If Parex Resources has put oil and gas producers on your radar, it can be useful to broaden your watchlist with other companies that share some of the qualities you care about, whether that is resilience, income or mispriced value.
The Simply Wall St Screener can help you quickly turn those preferences into a focused set of stocks to research next.
- If capital preservation sits near the top of your checklist, start by reviewing 8 resilient stocks with low risk scores that pair steadier risk profiles with more resilient fundamentals.
- For investors who want potential mispricing opportunities on their radar, scan through 10 high quality undiscovered gems that combine quality fundamentals with less crowded ownership.
- If regular income matters to you, line up 3 dividend fortresses that currently offer yields above 5% and then compare their cash coverage and payout history.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com