


How Seattle Airport Duty Free Win At Avolta Stock Has Changed Its Investment Story
- Avolta AG’s Hudson unit secured a new 20 year duty free concession at Seattle Tacoma International Airport in October 2026, covering A, N and S Concourses with stores that blend global duty free assortments with local Washington State products and experiences.
- The concession leans heavily into Seattle’s sense of place, with local food, regional spirits, artist performances and city themed merchandising that test Avolta’s focus on experiential, location specific travel retail formats.
- We will look at how Avolta's long term Seattle Tacoma duty free concession shapes the broader investment narrative around experiential travel retail.
Scan how Avolta’s experiential airport model compares with other travel focused retailers by running through the hand picked 618 high quality undiscovered gems that could be flying under most investors' radars.
Avolta Investment Narrative Recap
For Avolta, the core belief as a shareholder is that travel retail can still reward in person experiences and that management can convert footfall into higher spend per passenger. The Seattle Tacoma contract supports that thesis but does not change the reality that interest costs are a pressure point and earnings growth expectations are moderate rather than explosive.
The near term swing factor remains execution on new concessions and integration of retail and food formats, not this single airport win. The biggest risk is still external, with passenger volumes and geopolitical shocks able to hit sales, alongside tighter competition for prime airports that could squeeze margins.
The Seattle Tacoma duty free award is the clearest recent example of Avolta leaning into experiential stores, local assortments and cross category travel concepts. This goes directly to the core catalysts analysts focus on, such as higher value transactions from premium and localized formats, plus the incremental benefit of more concessions in high traffic hubs.
That said, one airport deal does not remove structural issues. Interest payments remain only modestly covered by earnings and funding is fully reliant on external borrowing, so each long duration concession adds both opportunity and commitments. Investors still need to weigh these contracts against valuation, given the stock trades on a higher P/E than many Specialty Retail peers.
Avolta Forecasts Behind the Experiential Push
Avolta's narrative projects CHF 15.2b revenue and CHF 322.1m earnings by 2029. This assumes 2.8% yearly revenue growth and an earnings increase of about CHF 123.1m from CHF 199.0m today.
Uncover how Avolta's fair value indicates an 18% potential upside to its current price before the discount closes.
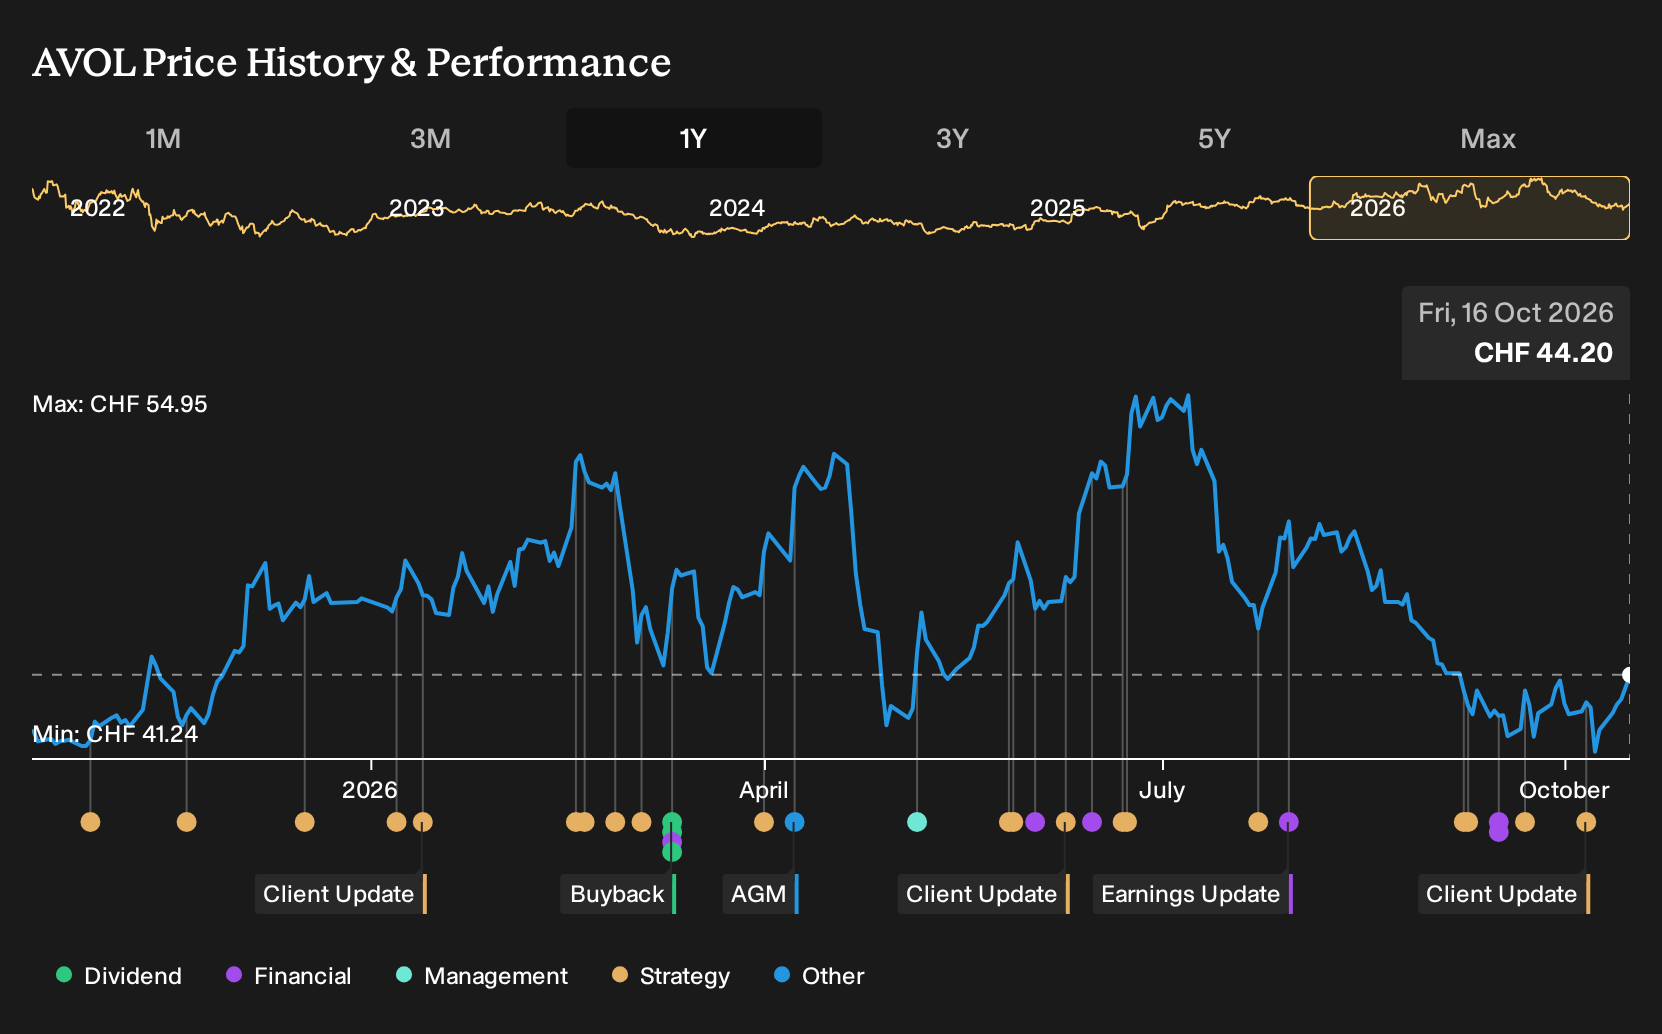
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between CHF 39.28 and CHF 51.94, even before factoring in the Seattle Tacoma contract. That tight band still hides very different views on risks such as geopolitical shocks or concession competition. Use these contrasting opinions to pressure test your own thesis on Avolta.
Explore another Avolta fair value estimate, including one that suggests as much as 18% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Avolta research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avolta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avolta's overall financial health at a glance.
Looking for more Avolta style investment ideas?
If the Avolta story has sharpened your thinking around contracts, risk and pricing power, use that same framework to scan other businesses that might fit your watchlist through the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, start with a curated set of 191 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and balance sheet strength sit high on your checklist, filter the market using a list of solid balance sheet and fundamentals (203 results) to see which companies clear that hurdle.
- Income focused investors who prize consistency over excitement can review a hand picked group of 214 dividend fortresses that might suit a yield oriented strategy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com