


Laser Warning Center Might Change The Case For Investing In Elbit Systems Stock (TASE:ESLT)
- Elbit Systems reported that its Swedish subsidiary plans to launch Europe’s first production and maintenance center for laser warning systems, targeted to be operational in 2027 to support regional and NATO customers with local manufacturing and service.
- This move points to a deeper push by Elbit Systems into European defense supply chains, with on-the-ground capability that can influence contract structures, delivery timelines and long-term support economics for its electronic warfare portfolio.
- We will now look at how Elbit Systems’ new Swedish laser warning facility could reshape the existing investment narrative around European expansion.
Elbit Systems Investment Narrative Recap
To own Elbit Systems, you need to be comfortable with a defense contractor that leans heavily on a record US$25.2b backlog, multi year programs and a rising share of sales outside Israel. The key near term swing factor is how efficiently that order book turns into revenue and cash, especially as European demand shapes mix and delivery priorities.
The biggest immediate risk sits on the other side of that same equation. A cooling in global defense budgets or a shift in U.S. spending away from Elbit’s focus areas could soften new awards, while any execution slip on large contracts or advanced energy programs would pressure margins that currently benefit from scale and automation.
The Swedish laser warning facility plan ties directly into Elbit Systems’ push to deepen its European presence, alongside existing investments in Sweden and Germany. A local production and maintenance base in Sweden can align closely with European and NATO tenders. This matters for converting the existing backlog into higher margin electronic warfare work and for competing on new programs.
Operationally, this move sits in the same bucket as the wider rollout of directed energy systems such as IRON BEAM. Both rely on Elbit showing it can industrialize complex tech and support it locally, which is where the execution risk lies. If the group manages cost, timing and certification well, these projects can reinforce its position in higher value segments and support the multi region growth profile already reflected in analyst forecasts.
Elbit Systems' current analyst narrative points to revenues of $11.8b and earnings of $1.1b by 2029, based on an assumed 11.5% yearly increase in sales and a move from $636.0m of earnings today to that higher profit base. This implies an earnings uplift of about $464.0m over the period.
Uncover why Elbit Systems' fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
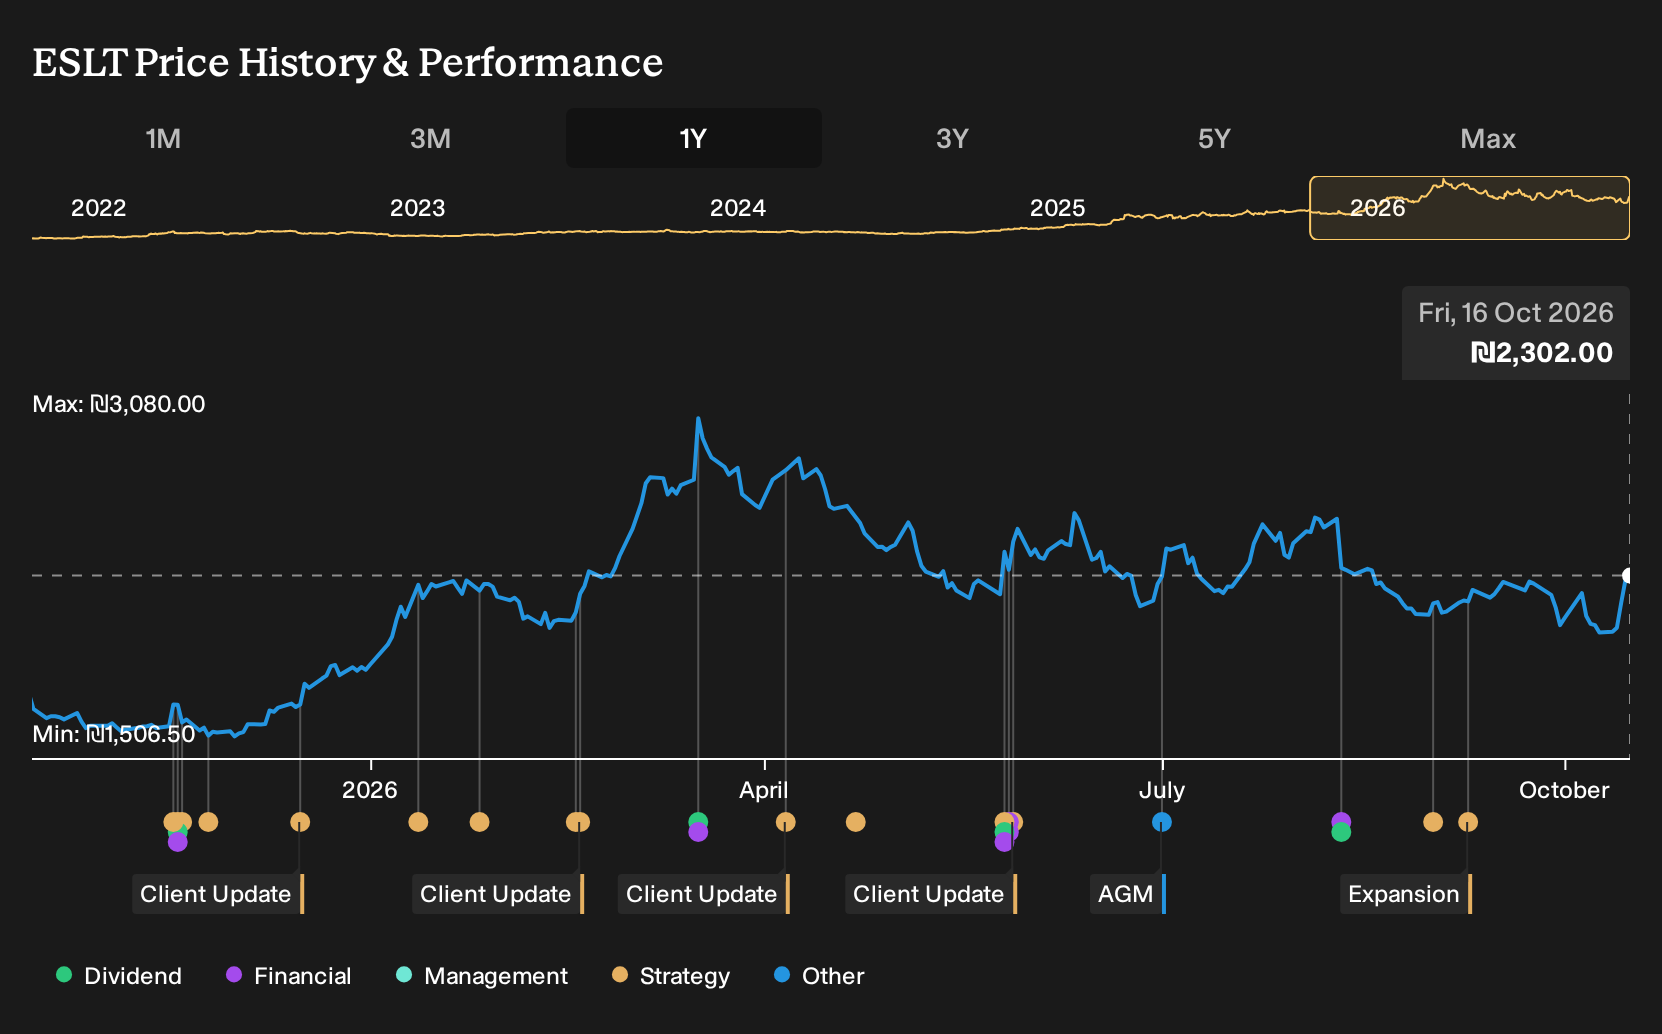
Four fair value estimates from the Simply Wall St Community range from about US$1,009 to almost US$2,968 per Elbit Systems share, a very wide spread that signals sharply different expectations. Those views were formed before the Swedish facility news and before upcoming Israeli elections, so you should weigh them against fresh political and defense budget risk.
Explore 3 other Elbit Systems fair value estimates, including one that suggests as much as 29% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Elbit Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Elbit Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elbit Systems' overall financial health at a glance.
Looking for more investment ideas beyond Elbit Systems?
You do not need to stop with Elbit Systems. If this Swedish expansion has you thinking more broadly about defense exposure, balance sheet strength or future income, the Simply Wall St Screener can help you quickly surface other candidates that fit your preferences.
- For investors who care most about valuation support and fundamental strength, start with a curated set of 191 high quality undervalued stocks that already clear quality and balance sheet checks.
- If your priority is resilience and capital preservation, focus on companies screened for stability and lower risk profiles by reviewing 233 resilient stocks with low risk scores that may better match a cautious approach.
- When the goal is to back underfollowed opportunities with solid numbers, widen your research universe through 618 high quality undiscovered gems that already show strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com