


Learn Why The Bull Case For American Airlines Stock Could Change Following Earnings Outlook Cut
- American Airlines Group recently reduced its 2026 earnings outlook as higher fuel costs pressured profitability, even with record revenue and plans to add more premium seats and seatback entertainment to attract higher spending travelers.
- The key tension for American Airlines Group is that the push toward premium cabins and onboard upgrades comes at a time when operating margins still lag peers, so heavier investment and rising fuel expenses are occurring simultaneously.
- This article examines how American Airlines Group's investment narrative is tested by higher fuel costs that are pressuring already thin profitability and guidance.
Compare how American Airlines Group's premium push stacks up against other carriers by scanning a curated set of list of solid balance sheet and fundamentals (25 results) that may be better positioned for fuel and cost swings.
What Is American Airlines Group's Investment Narrative?
To own American Airlines Group, you have to believe the premium push can eventually offset a structurally heavy cost base. This is a scale carrier with a 1,013 aircraft fleet, high fixed expenses, and a capital hungry model. The bet is that higher spending passengers, better cabin mix, and loyalty economics can turn record revenue into consistent profits. The snag is that the latest fuel driven cut to 2026 earnings guidance, and the stock’s roughly 24% slide since mid 2026, underlines how thin the current margin for error looks.
The near term story now hinges on execution. Management must keep planes full at resilient fares while fuel stays expensive and Q3 2026 expectations already assume a quarterly loss of $0.28 per share. Analysts have been marking earnings estimates down, which can lower the bar, but it does not fix negative shareholders’ equity, weak interest coverage, or insider selling over the past quarter. Any premium cabin refresh still needs funding, so balance sheet pressure and higher risk funding remain front and center.
That said, there is one structural issue in American Airlines Group’s setup that could matter far more than the earnings cut...
There's only one way to know the right time to buy, sell or hold American Airlines Group. Head to Simply Wall St's company report for the latest analysis of American Airlines Group's Fair Value.
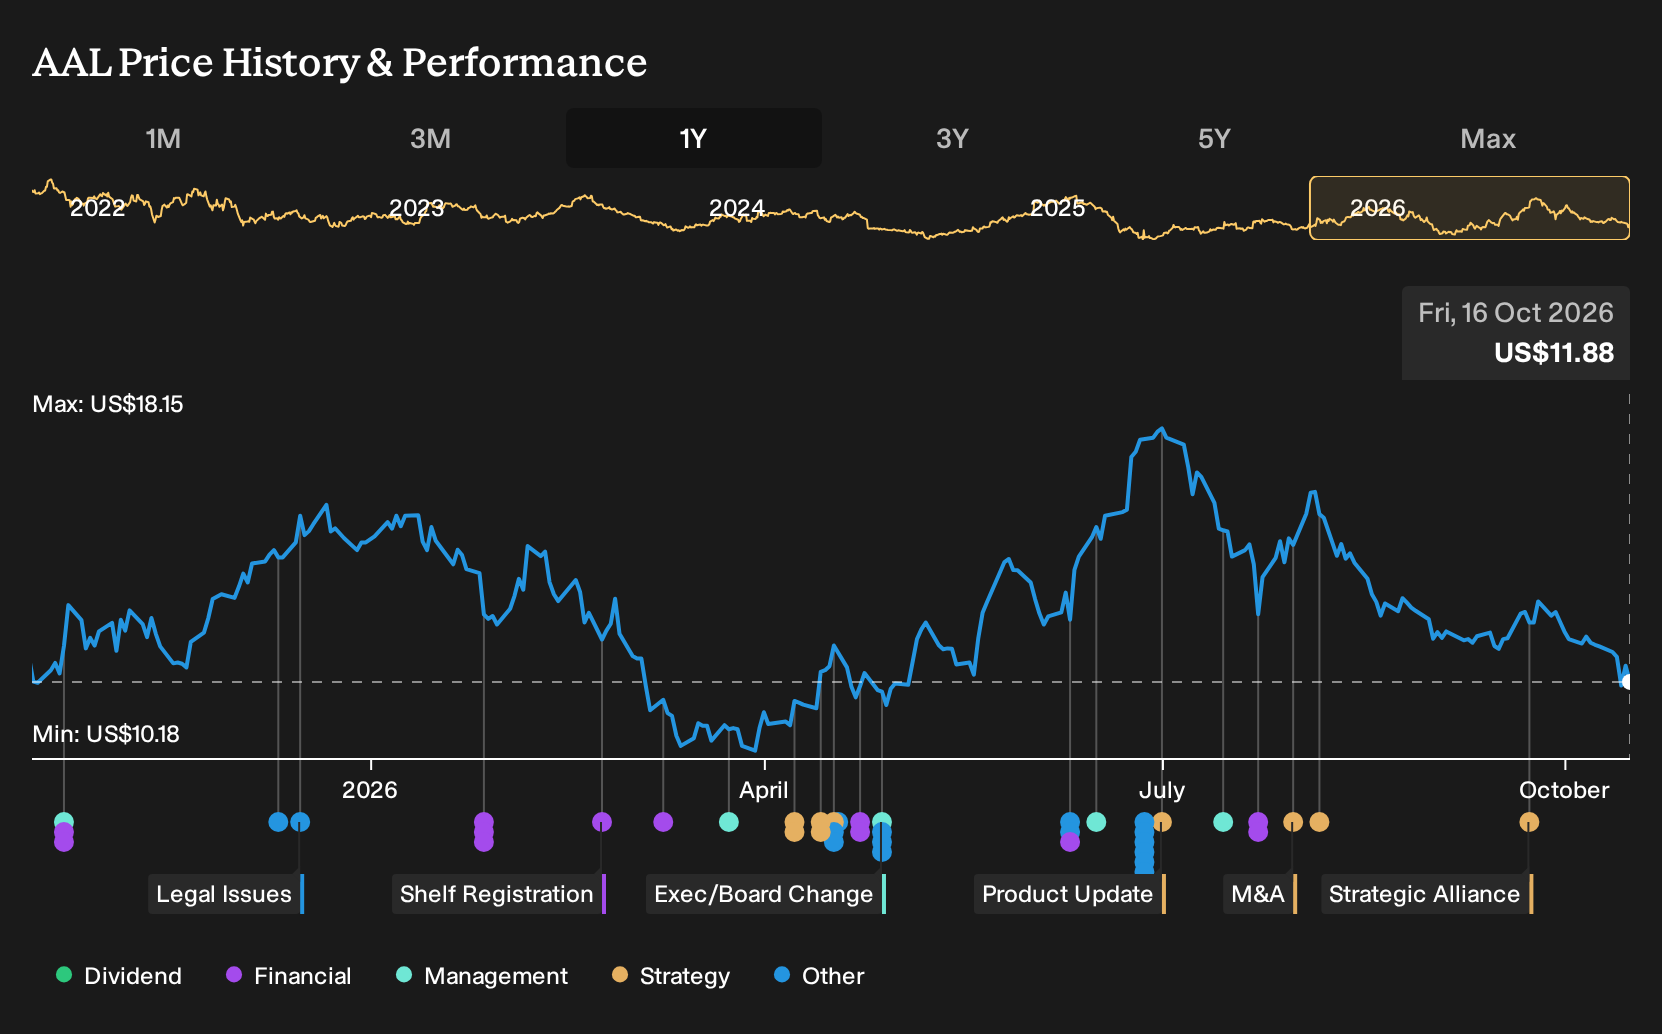
Exploring Other Perspectives
One optimistic twist in the alternate view on American Airlines Group is the belief that technology driven cost savings could outweigh fuel and labor pressure. The most bullish analysts were penciling in revenue of about $74.8b and earnings of $3.7b by 2029, so their upbeat story may shift after this latest guidance cut.
Explore 6 other American Airlines Group fair value estimates, including one that suggests as much as 538% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Airlines Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for American Airlines Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Airlines Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Airlines Group?
Once you have a view on American Airlines Group, it can help to compare it with very different business models so your portfolio is not leaning on a single story. The Simply Wall St Screener is a quick way to line up alternatives that match the kind of risk and return profile you want.
- If you want potential mispricing with quality in focus, scan through 33 high quality undervalued stocks that pair stronger fundamentals with more modest prices.
- For investors who care about income stability, review 8 dividend fortresses that aim for robust payouts with higher yield profiles.
- When capital preservation is front of mind, filter for 32 resilient stocks with low risk scores that score better on balance sheet strength and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com