


Tarsus Pharmaceuticals (TARS) Could Be 32% Undervalued After New Shelf Registrations
Why Tarsus Pharmaceuticals Filed New Shelf Registrations
Tarsus Pharmaceuticals (TARS) recently filed two shelf registrations covering potential share offerings totaling about US$382 million. This kind of move can matter for investors because it may signal future fundraising plans or upcoming business initiatives.
Recent trading has cooled some of the earlier enthusiasm around Tarsus Pharmaceuticals. The share price is down about 12% over the past month and 16% year to date, even though the 3 year total shareholder return of more than 4x remains very strong. This hints that the new shelf registrations are landing in a market where short term momentum is fading and investors are rethinking risk and funding needs after a long winning run.
Compare how Tarsus Pharmaceuticals' funding playbook compares with other healthcare stocks raising fresh capital by scanning our hand picked 33 high quality undervalued stocks.
Tarsus Pharmaceuticals now trades well below recent highs even after a multi year run that multiplied early investors. The real puzzle is whether the bigger upside already played out or if the fresh capital plan creates another leg.
Most Popular Narrative: 32% Undervalued
The most followed narrative currently pegs fair value for Tarsus Pharmaceuticals at about $99.50 per share, compared with the last close of $68.07. That gap frames the shelf registrations as part of a broader funding story, not just a one off capital move.
The company's pipeline expansion (e.g., TP-04 for ocular rosacea) positions Tarsus for multi-product leverage in underserved markets, supporting diversified, long-term earnings growth and reducing future revenue concentration risk.
See why 14 investors see Tarsus Pharmaceuticals as 32% undervalued.
The fair value estimate uses a 7.24% discount rate and builds in assumptions for faster revenue expansion, margin improvement, and future earnings power. It reflects a view that Tarsus Pharmaceuticals could justify a higher future earnings multiple if those growth and profitability expectations are met.
Result: Fair Value of $99.50 (UNDERVALUED)
Still, the narrative around Tarsus Pharmaceuticals can crack if XDEMVY uptake disappoints, or if heavy commercial and R&D spending keeps profitability under pressure for longer.
Find out about the key risks to this Tarsus Pharmaceuticals narrative.
Another View on Tarsus Pharmaceuticals Valuation
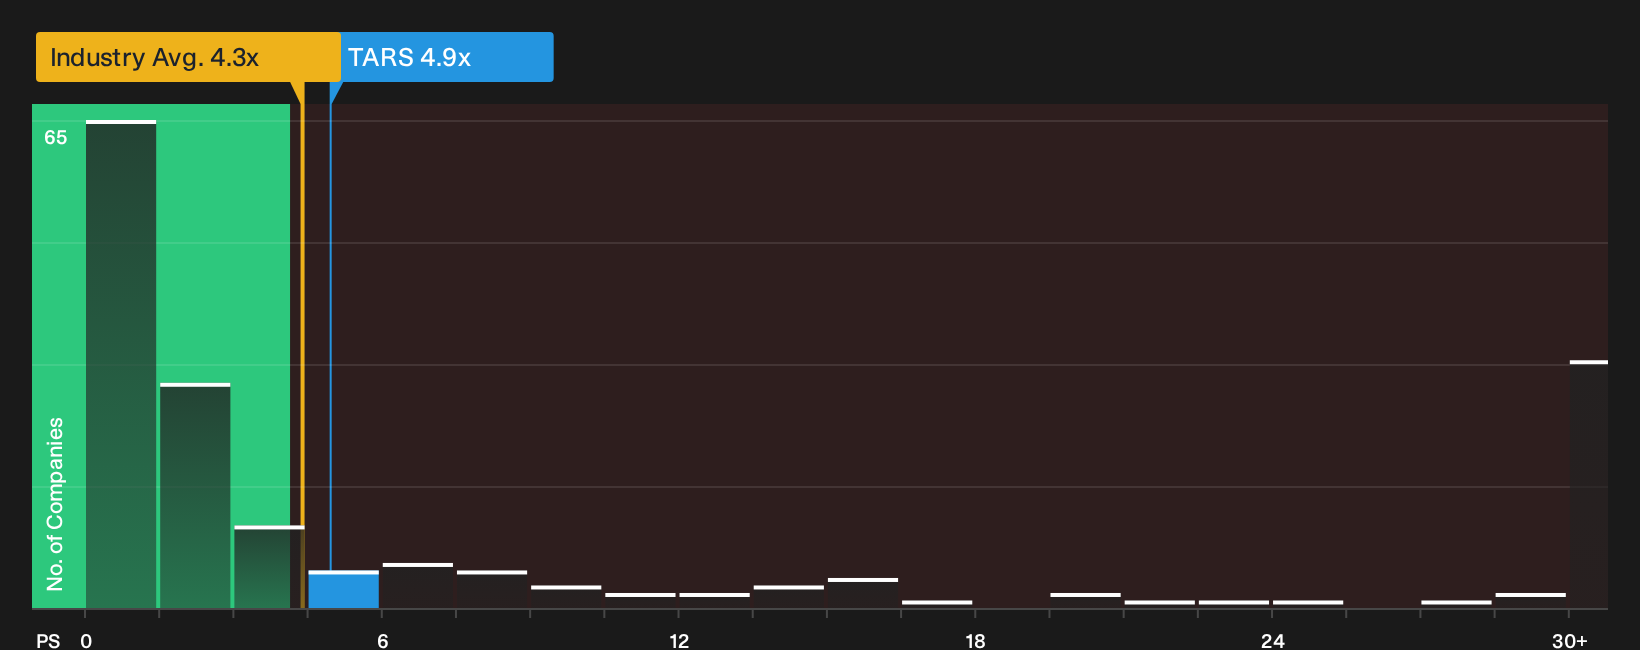
The first story presents Tarsus Pharmaceuticals as materially undervalued, with a fair value near $99.50 compared with a share price of $68.07. A different lens tells a more mixed story. On a simple P/S yardstick of 4.9x, the stock appears slightly expensive versus the US Pharmaceuticals group at 4.5x, yet still well below peers at 11.5x and beneath a fair ratio of 8.3x. That gap suggests both potential for rerating and the possibility that the market continues to treat TARS as cheaper for a reason. Which side of that trade-off seems more convincing to you.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views remain about what this all means for Tarsus Pharmaceuticals. Act while the facts are fresh and pressure-test the balance of upside and risk through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tarsus Pharmaceuticals?
If Tarsus Pharmaceuticals has you thinking harder about opportunity and risk, do not stop with a single ticker. Cast a wider net while this research is fresh.
Use the Simply Wall Street Screener to quickly surface fresh ideas that fit different goals, risk levels, and balance sheet profiles.
- Target potential upside in quality businesses that the market may be overlooking by scanning our hand picked 20 high quality undiscovered gems.
- Strengthen portfolio resilience by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Reduce stress around big drawdowns by filtering for steadier performers through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com