


FirstEnergy (FE) Draws Valuation Focus After Goldman Cuts Its Price Target
Goldman Sachs reduced its target on FirstEnergy (FE) from US$55 to US$53, drawing fresh attention to how the utility stock’s current US$46.19 price compares with broader analyst expectations.
Recent trading has been mildly positive, with FirstEnergy’s share price posting a 1-day gain of 1.41% and a 7-day share price return of 2.64%, even though the 90-day share price return is down 4.82% from earlier levels.
Over a longer stretch, the picture looks steadier for shareholders, with a 1-year total shareholder return of 2.29% and a 3-year total shareholder return of 48.29%. This suggests that momentum has cooled in the near term while remaining constructive over multi year horizons.
Scan how FirstEnergy compares with other grid and infrastructure plays by reviewing the hand picked 41 power grid technology and infrastructure stocks.FirstEnergy looks like a solid regulated utility with growing revenue and net income, yet Goldman’s lower target and the current US$46.19 price raise a simpler issue: Is this quality already fully reflected in the valuation?
Most Popular Narrative: 10% Undervalued
Against FirstEnergy’s last close of $46.19, the most followed narrative pegs fair value nearer $51.42, which implies the stock trades at roughly a 10% discount once future earnings and risks are run through a 7.24% discount rate.
Surging demand from data centers, AI, and high growth sectors remains a central theme for FirstEnergy, with forecasted data center load of roughly 25 GW by Q2 2026 and 6.4 GW already contracted. This supports further investment in transmission and distribution assets and can lift long term revenue and earnings growth.
See why 16 investors see FirstEnergy as 10% undervalued.
Result: Fair Value of $51.42 (UNDERVALUED)
Still, the FirstEnergy narrative depends heavily on regulators allowing timely bill recovery and on capital spending not squeezing free cash flow if funding costs remain elevated.
Find out about the key risks to this FirstEnergy narrative.
Another View: FirstEnergy On Earnings Multiples
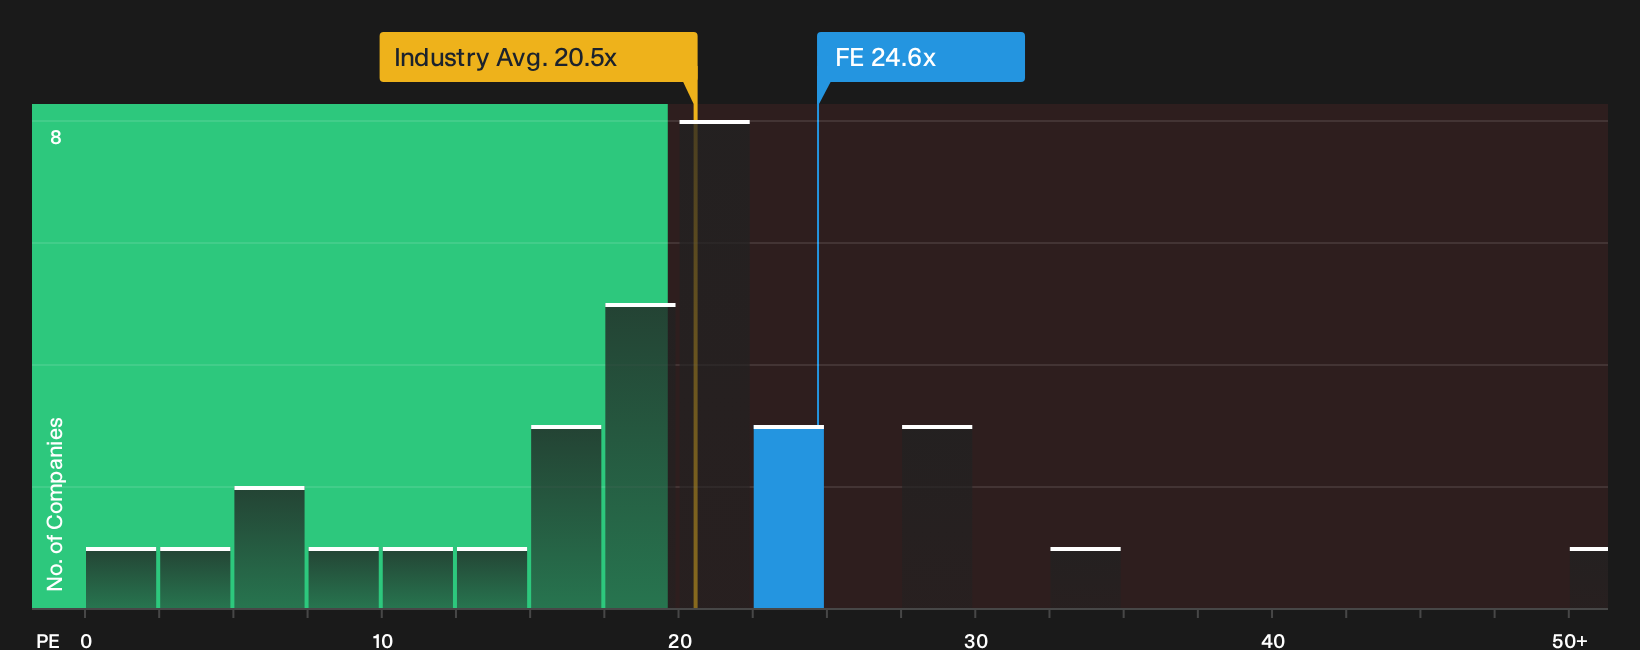
There is a different read on FirstEnergy if you focus on simple earnings multiples instead of the narrative fair value. The stock trades on a P/E of 24.6x, compared with about 20.2x for the US Electric Utilities industry and 18.9x for peers, while the fair ratio flags 21.4x as a level the market could move toward. That richer P/E points to valuation risk rather than a clear bargain, so the key question is whether you think the quality of the regulated grid story really justifies paying more than sector and peer averages.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on FirstEnergy is mixed, and the tug of war between concerns and upside potential is clear for anyone watching closely. You can move quickly from headline takes to your own judgment by weighing the 1 key reward and 2 important warning signs.
Looking for more ideas beyond FirstEnergy?
If you stop at FirstEnergy, you risk missing out on other opportunities that could fit your goals even better, so broaden your search before making a move.
- Target stronger value by scanning the 33 high quality undervalued stocks that blend solid fundamentals with prices that still look reasonable.
- Prioritise resilience and sleep easier at night by reviewing a 32 resilient stocks with low risk scores that scores well on stability metrics.
- Spot underfollowed potential by checking a 20 high quality undiscovered gems with quality financial profiles that have not yet drawn heavy attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com