


What UNIQA Insurance Group Holders Got Right
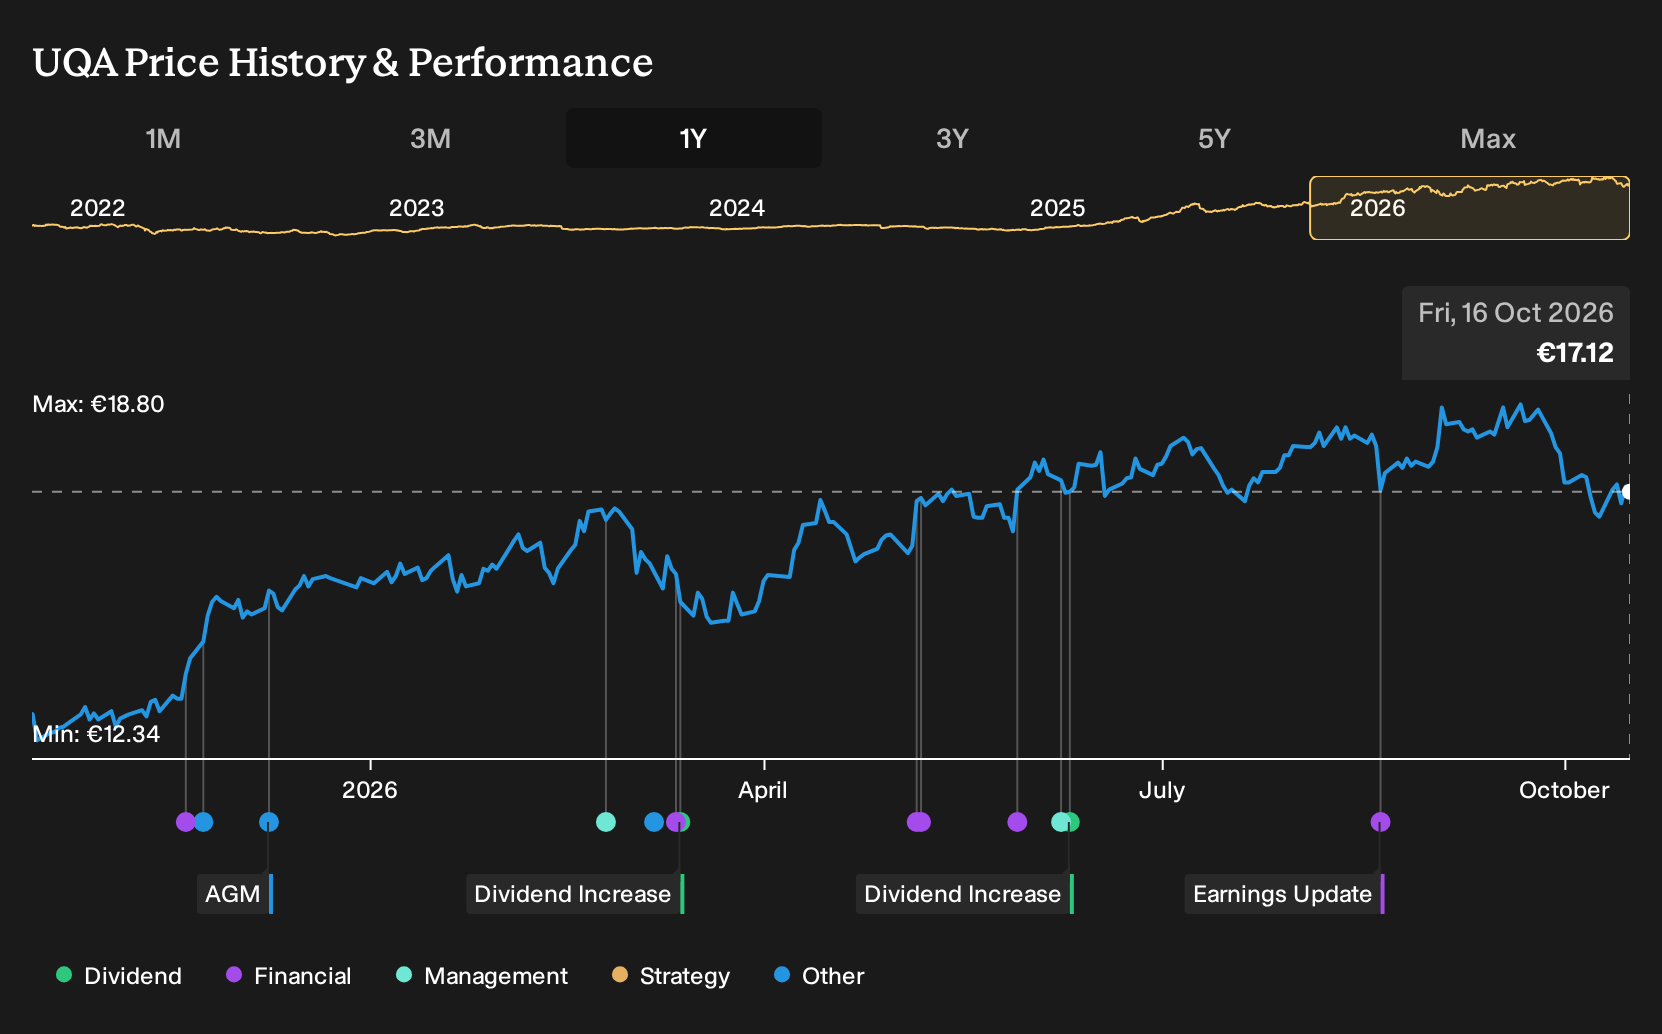
If you only skimmed the headlines about UNIQA Insurance Group repaying a subordinated Tier 2 bond, completing a share buyback, and approving a €0.72 dividend, you might not expect the shareholder outcome that followed. Investors who held UNIQA Insurance Group over the past year are up 44.6%, including dividends. If you were weighing a purchase back on 16 October 2025, what did that later payoff ask you to see in the business risks and capital moves on record then?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
UNIQA Insurance Group has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Case For, And The Case Against UNIQA Insurance Group Back Then
The shares cost €12.84 at the start of the period. Any Narrative on UNIQA Insurance Group had to answer whether that quote left enough room for upside or downside.
The bull case argued for a Fair Value of €13.78, built on 4.6% annual revenue expansion and profit margins reaching 5.5% over three years, with Central and Eastern European digital growth doing much of the lifting.
The bear view pointed to a Fair Value of €11.6, stressing pressure from insurtech competitors and the risk that low or volatile European interest rates would weigh on investment income.
What The Results Changed For UNIQA Insurance Group
UNIQA Insurance Group repaid its subordinated Tier 2 bond and completed a share buyback, which supported the bullish focus on capital flexibility. Quarterly figures also gave both sides new data to weigh. Revenue moved from €1,916.1m in Q2 2025 to €2,147.9m in Q2 2026, net income rose, and net margin edged from 4.2% to 4.6%. The evidence cut both ways but leaned toward the optimistic case on profitability.
The clear hinge here was profitability and capital use. When you test another insurer's story, check whether reported margins move toward or away from the thesis and whether debt reduction or buybacks align with the original risk argument.
What UNIQA Insurance Group's Price Seems To Assume Now
UNIQA Insurance Group now trades at €17.12. The selected Narrative places its Fair Value above that quote and pins the argument less on Central and Eastern Europe expansion and more on capital strength and a broader earnings base.
At this price you are effectively judging whether the Zurich reinsurance arm, solvency position and Life and Health profit pool can support durable returns that the Narrative argues are not yet fully credited.
"The view on UNIQA Insurance Group has shifted from a broad focus on underappreciated Central and Eastern European growth and digital efficiency to a more specific, earnings-quality-driven thesis that centres on the new external reinsurance arm, capital strength and contractual service margin sustainability as the key pillars for future returns."
The price and this Narrative do not agree. → Uncover what this Narrative says UNIQA Insurance Group is actually worth
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 33% below our estimate - targets higher value nutrition offerings and builds export channels beyond its base.
- Company 2 - 23% below our estimate - attracts senior lawyers from traditional partnerships to a tech enabled, fee sharing model.
- Company 3 - 46% below our estimate - shifts from pure underwear toward faster growing sports fashion for everyday athletes.
Those are three of them. See all 203 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com