


12% Below Fair Value Following Buyback And Guidance Lift At Takeuchi Mfg (TSE:6432)
Takeuchi Mfg (TSE:6432) just packed several shareholder moves into one day, combining a sizeable buyback authorization, a higher year-end dividend forecast, and upgraded full-year earnings guidance on October 13, 2026.
The latest package of shareholder moves lands on a stock that already has momentum, with a 1-day share price return of 2.26% at ¥7,680 and a 7-day gain of 5.49% adding to a 12.45% year to date move. Over a longer stretch, Takeuchi Mfg has delivered a 34.87% 1-year total shareholder return and 213.87% over five years. As a result, the buyback, higher dividend guidance, and upgraded earnings outlook are hitting an investor base that has already seen strong compounding and may view these announcements as a fresh signal that management is responding to that support.
Scan how Takeuchi Mfg's latest buyback and dividend upgrade compares with other income focused opportunities using our hand picked 29 dividend fortresses.
After this buyback and dividend reset, investors face a simple fork in the road: step in at ¥7,680, or wait and let the valuation case make the next move first.
Preferred P/E of 12.1x: Is it justified?
On simple valuation math, Takeuchi Mfg is screening as modestly cheap. The stock closed at ¥7,680 and is trading at a P/E of 12.1x, which is lower than both the estimated fair P/E of 13.9x and the JP Machinery industry average of 12.8x.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors are paying for each unit of profit. For a construction machinery manufacturer with a long operating history, earnings based measures tend to matter more than story driven metrics because cash generation and cycle resilience sit at the forefront of investor focus.
That lower P/E suggests the market is not paying a premium for 6432's profit stream despite high quality earnings and a 5 year annual earnings growth rate of 17.5%. When the current multiple of 12.1x is compared with the estimated fair P/E of 13.9x, it indicates a sizeable gap that the valuation could move toward if investors become more comfortable with the forecast profile, even though earnings are only projected to expand 2.7% per year and return on equity is described as low at 14.8%.
Compared with peers, the picture is mixed. Against the broader JP Machinery industry, 6432 is on the cheaper side with a P/E below the 12.8x sector average. Against a narrower peer set, the shares are described as expensive relative to a peer P/E of 8x. That tension between a discount to the sector and a premium to direct peers is one reason the fair P/E of 13.9x is useful as a reference point for the level the market could migrate toward if sentiment shifts.
Explore the SWS fair ratio for Takeuchi Mfg.
Result: Price-to-earnings of 12.1x (UNDERVALUED).
Still, the story can break if Takeuchi Mfg hits a construction downturn that crimps demand, or if peers on 8x P/E continue to drag investor expectations lower.
Find out about the key risks to this Takeuchi Mfg narrative.
Another view on Takeuchi Mfg’s value
A second lens comes from the SWS DCF model, which values Takeuchi Mfg at ¥8,751.63 per share versus the current ¥7,680. On that math the stock screens as undervalued again, this time by 12.2%. So is the market just slow to catch up, or is it correctly discounting future growth?
Look into how the SWS DCF model arrives at its fair value.
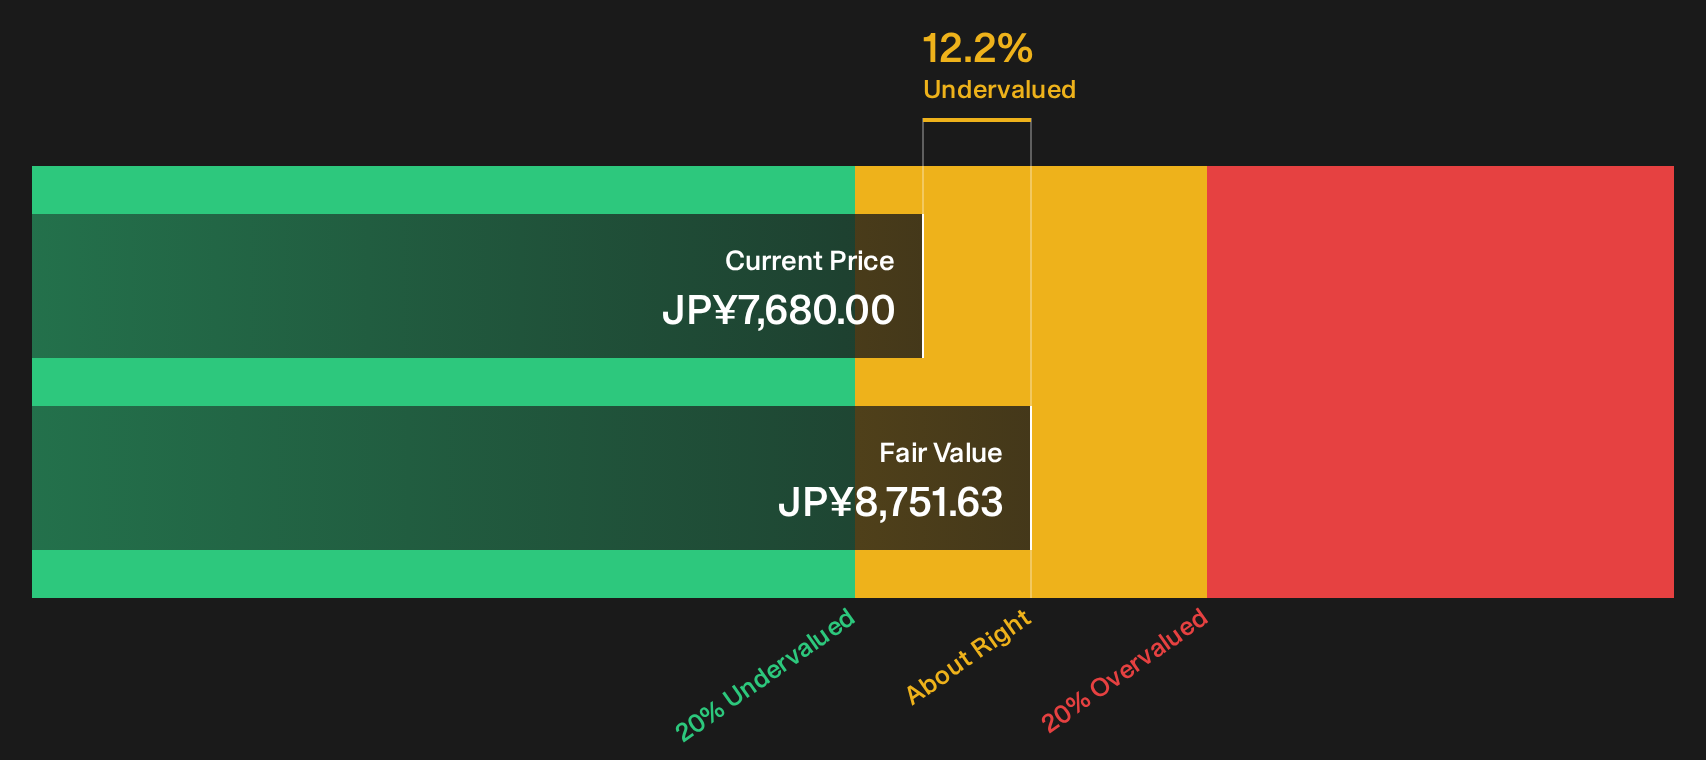
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takeuchi Mfg for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Views on Takeuchi Mfg may feel pulled in both directions right now, so move fast, review the full picture, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Takeuchi Mfg?
If Takeuchi Mfg has your attention, do not stop there. Broaden your watchlist now so you are not relying on a single opportunity.
- Target stability first and see which resilient businesses clear our balance sheet quality bar through the list of solid balance sheet and fundamentals (21 results).
- Hunt for mispriced opportunities by scanning companies that combine quality fundamentals with appealing value using the 14 high quality undervalued stocks.
- Spot earlier stage potential by filtering for smaller companies with stronger financial underpinnings through the 1 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com