


Harmonic (HLIT) Could Be 34% Undervalued After Cablenet Broadband Win
Harmonic (HLIT) just secured a fresh broadband win, with Cablenet choosing its cOS virtualized platform to overhaul DOCSIS access infrastructure and support higher speed tiers, lower operating costs and AI-driven network intelligence.
Recent momentum around Harmonic includes this Cablenet win and new fiber broadband showcases at Network X 2026. However, the 90-day share price return is down 11.14%, while the 5-year total shareholder return of 15.07% points to a steadier long-run record.
Scan a curated set of broadband and AI-infrastructure plays by checking out the 55 AI infrastructure stocks, which share Harmonic’s focus on fiber, DOCSIS upgrades and network intelligence.
After a 90 day pullback and a solid five year record, Harmonic now sits between two stories: most of the upside already cashed in, or more value still on the table when you run the numbers?
Most Popular Narrative: 34% Undervalued
Harmonic is trading at a last close of $10.69, while the most followed narrative anchors fair value at $16.14 and views today’s price as a discount that depends heavily on how its broadband software and intelligence story develops.
The shift toward higher margin software and recurring broadband services is accelerating as Harmonic targets recurring revenue of 22% to 25% of total, including intelligence at about 10% of sales within three years, which may support higher gross margin and operating margins above 20%.
See why 17 investors see Harmonic as 34% undervalued.
Result: Fair Value of $16.14 (UNDERVALUED)
Still, Harmonic’s reliance on two customers for 63% of Q2 2026 revenue, along with ongoing memory cost pressure, could quickly weaken that 34% undervaluation story.
Find out about the key risks to this Harmonic narrative.
Another View: Harmonic On Earnings Multiples
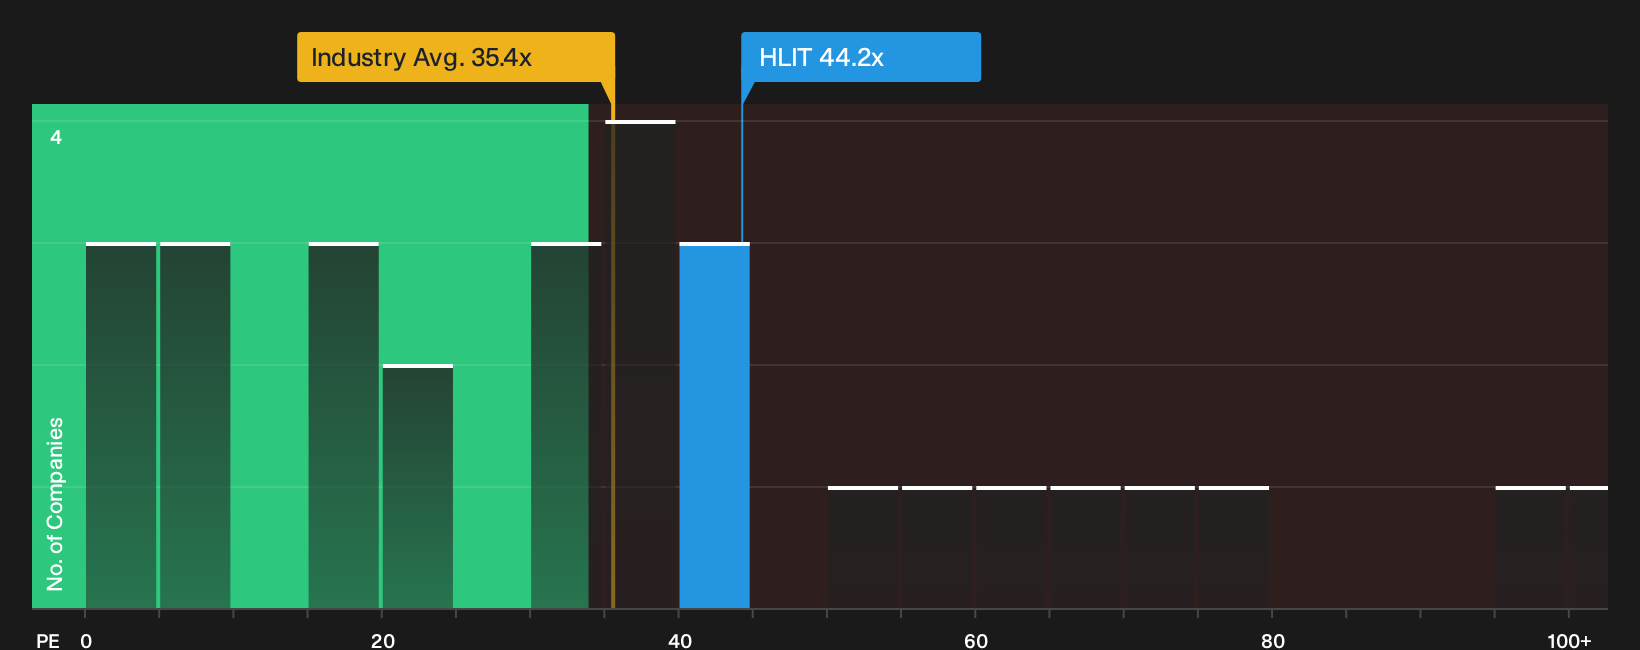
On earnings, Harmonic appears less generous. The stock trades on a P/E of 44.2x, which sits above both the US Communications sector at 35.4x and its own fair ratio of 34.1x. Anyone using this measure has to decide if that premium represents potential headroom or valuation risk.
For a closer look at how that earnings multiple compares across industry peers, and where the fair ratio suggests pricing could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals so far, right? If you want a clear view, move quickly, pull up the data yourself, and weigh Harmonic’s upside against its weak spots with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Harmonic?
If Harmonic has your attention, do not stop here. Broader context from other opportunities can sharpen your judgement and help inform your decisions.
- Target dependable income streams by reviewing companies in the 8 dividend fortresses that may suit a portfolio focused on regular cash returns.
- Hunt for quality at a discount by scanning the 20 high quality undiscovered gems that might not yet be on most investors’ radar.
- Prioritise resilience by filtering for businesses in the 32 resilient stocks with low risk scores that pair sturdier balance sheets with lower overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com