


What Aker BP (OB:AKRBP)'s Third Quarter Operating Results Mean For Shareholders
- Aker BP reported third quarter 2026 operating results, with equity production averaging 3,743 mboepd and net volume sold at 395.7 mboepd.
- The gap between equity production and volumes sold, alongside the comparison to the prior quarter’s 375.7 mboepd, gives investors additional detail on how Aker BP is moving barrels through its system.
- This section examines how Aker BP's investment narrative could be affected by its third quarter production and sales volume disclosure.
Aker BP Investment Narrative Recap
Aker BP appeals to shareholders who want a focused Norwegian Continental Shelf producer with large, long life fields and a visible project queue. The third quarter report, with equity production at 3,743 mboepd and 395.7 mboepd sold, keeps that operational story intact. The key short term catalyst still sits in execution on existing hubs and sanctioned projects, rather than one quarter of volumes.
The biggest near term risk remains heavy project load and capital intensity layered on top of a relatively high debt position and a dividend that is not well covered by earnings or free cash flow. Against that backdrop, this quarter’s production and sales disclosure looks important as a check in, but not a material reset of the business case.
The preliminary sales disclosure for the third quarter is the announcement that matters most around this update. Net volume sold of 395.7 mboepd, compared with 375.7 mboepd in the prior quarter, gives a clearer view of how Aker BP is converting field production into revenue generating barrels and managing timing effects between output and liftings.
This is a story built on keeping production above 500,000 barrels per day beyond 2030. Every data point on volumes and uptime feeds into conviction on long duration projects such as Yggdrasil and Johan Sverdrup. Execution on these assets, cost control as emissions pricing evolves, and discipline on exploration and acquisitions remain the practical catalysts to watch around the stock.
Aker BP's current analyst narrative points to forecast revenues of $13.4b and earnings of $1.8b by 2029, based on an assumed 4.1% yearly revenue growth rate. That path implies earnings rising from $1.4b today to $1.8b, an increase of about $0.4b over the forecast period.
Uncover why Aker BP's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
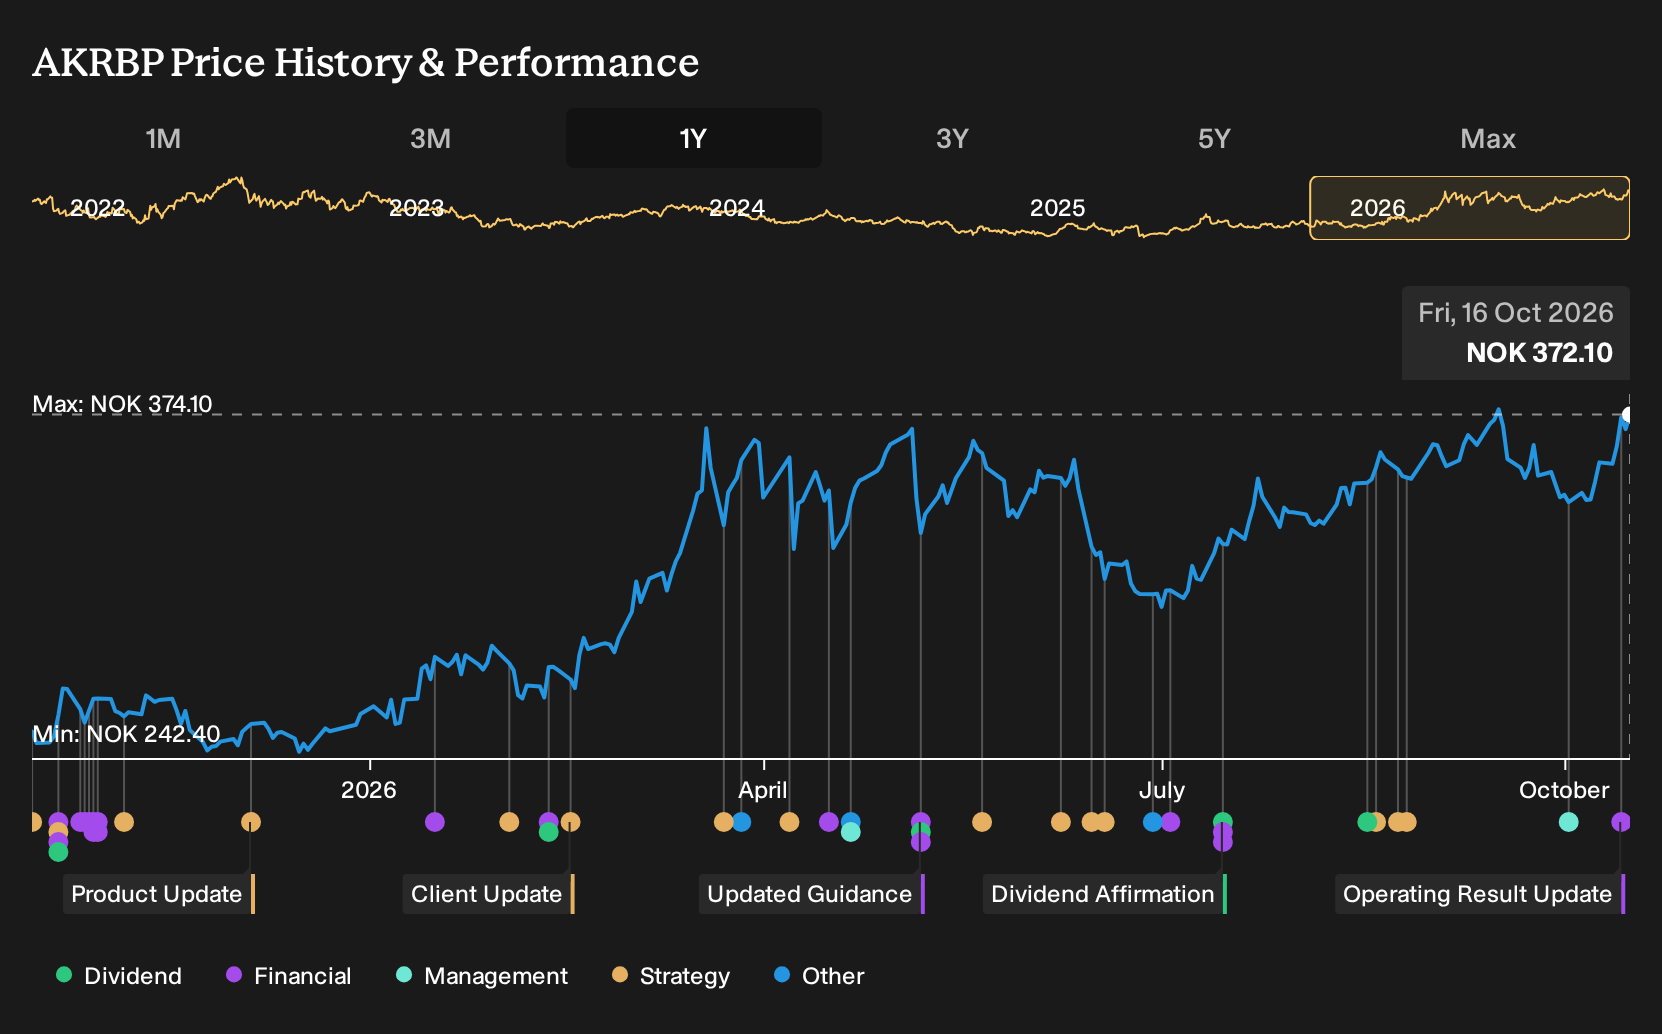
Exploring Other Perspectives
For an alternative lens on Aker BP, focus on demand risk rather than project execution. The most cautious analysts were assuming revenue of about $12.1b and earnings flat at $1.4b by 2029, even before this production and sales update. That more pessimistic story may shift, and you can compare these views to form your own stance.
Explore 5 other Aker BP fair value estimates, including one that suggests as much as 34% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Aker BP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aker BP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aker BP's overall financial health at a glance.
Looking For More Ideas Beyond Aker BP?
If the Aker BP story has you thinking about portfolio gaps, it can help to line it up against other opportunities with different risk profiles and income characteristics. The Simply Wall St Screener is built for that kind of side by side comparison.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (203 results) that can sit at the core of a more defensive portfolio.
- Hunt for misunderstood quality by reviewing a 618 high quality undiscovered gems that combine stronger fundamentals with relatively underfollowed tickers.
- Prioritise stability and income by using a 213 dividend fortresses that focuses on companies offering higher yields backed by more robust metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com