


Does New Conveyor Belt Launch Change The Bull Case For Gates Industrial (GTES)?
- Gates Industrial has launched the Gates IntraLogix LRB-100 live roller belt in the US, using a homogeneous polyurethane design that targets longer belt life, lower maintenance needs and more consistent uptime for high speed warehouse and distribution center conveyor systems.
- The LRB-100 extends the IntraLogix range alongside LRB-45 and LRB-77, signaling deeper focus on warehouse automation customers that depend on abrasion resistance, higher weld strength and lower drive tensions to keep e-commerce fulfillment running with fewer conveyor related interruptions.
- We will look at how Gates Industrial's investment narrative ties into warehouse automation after the LRB-100 launch for intralogistics customers.
Scan how Gates Industrial's warehouse automation push compares with other logistics focused players by reviewing our hand picked 92 robotics and automation stocks tied to conveyor, robotics and intralogistics themes.
Gates Industrial Investment Narrative Recap
To own Gates Industrial, you need to believe that new platforms like warehouse automation, personal mobility, and data centers can steadily offset softer traditional auto and industrial OEM demand. The LRB-100 launch fits that belief because it ties Gates Industrial more tightly to e-commerce fulfillment and intralogistics customers that care about uptime, reliability, and total cost of ownership.
The near term swing factor still looks like end market health in industrial OEM, construction, and conventional automotive, where conditions have been challenging. If those areas stay weak and newer segments remain small against the US$3.5b revenue base, the LRB-100 announcement alone is unlikely to meaningfully change the biggest risk, which is muted overall growth and pressure on returns.
The most relevant recent development for this launch is Gates Industrial ongoing focus on new engineered belt platforms across automation and industrial applications. Management has been investing in research and development to push chain to belt conversion in a roughly US$7b industrial market, aiming for more recurring replacement cycles and potentially better margins as installed base builds.
LRB-100 slots directly into that playbook. The product data points matter operationally because much longer belt life, lower elongation, higher abrasion resistance, and lower drive tension all speak to reduced downtime and wear on equipment. If customers validate these outcomes at scale, it could support adoption across high speed warehouses and intralogistics systems. That, in turn, makes that broader automation catalyst more tangible for the business over time.
Gates Industrial's narrative projects US$4.1b revenue and US$435.2m earnings by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of about US$71m from US$364.1m today.
Uncover why Gates Industrial's fair value indicates a 29% potential upside to its current price that could close more quickly than investors expect.
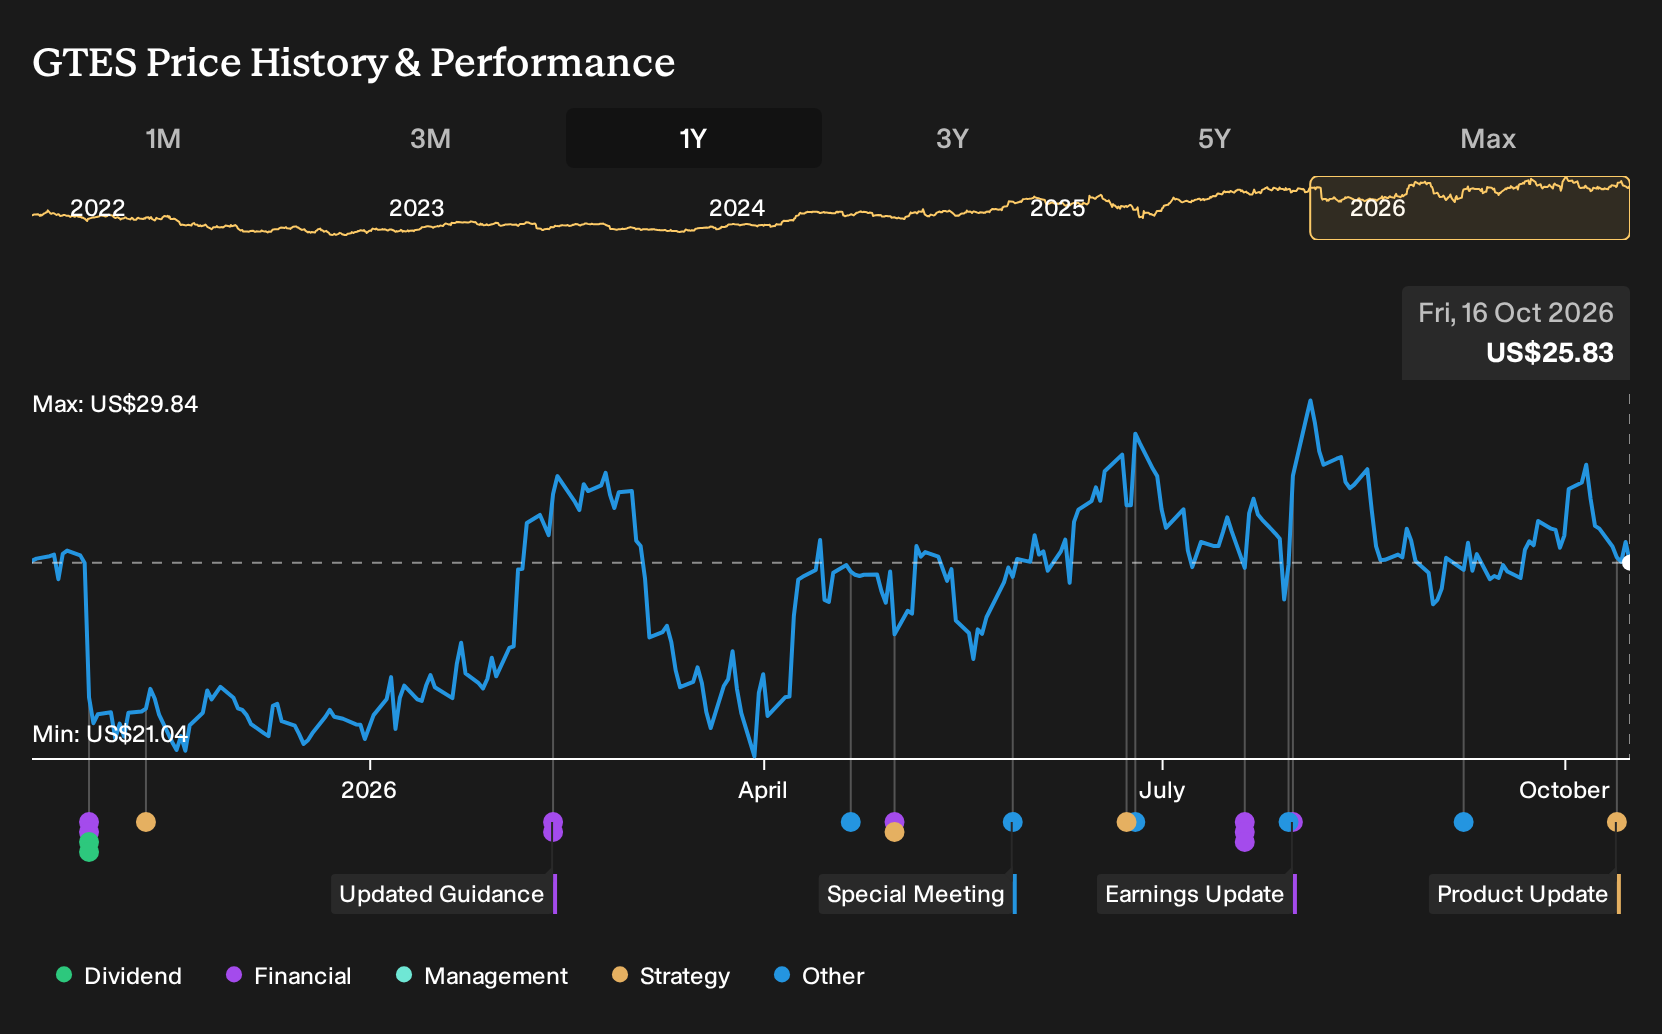
Exploring Other Perspectives
Some of the lowest ranked analysts frame a very different risk for Gates Industrial. They worry that data center and personal mobility projects stay too small to offset flat core markets, which is why they were only penciling in US$4.0b revenue and US$399.3m earnings by 2029. Those views were set before the LRB-100 news, so you may want to see how this launch eventually reshapes both the bullish and bearish stories.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gates Industrial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Gates Industrial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gates Industrial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gates Industrial?
Once you have formed a view on Gates Industrial, it often helps to widen the lens and compare it with other opportunities that share similar quality, income, or risk profiles. The Simply Wall St Screener can surface a broad set of businesses that match the kind of characteristics you care about most.
- If you want income to do more of the heavy lifting in your portfolio, start with companies that combine higher yields with resilient payouts through our 8 dividend fortresses.
- For investors who care most about balance sheet strength and fundamentals, filter for sturdier operators using the list of solid balance sheet and fundamentals (25 results).
- If you prefer to hunt for less widely followed stories backed by solid numbers, cast a wider net with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com