


SoftBank Group (TSE:9984) Stock Looks Below Fair Value Despite AI Funding Fears
SoftBank Group has seen its share price swing sharply in recent weeks, which leaves a straightforward but important question for investors who care about valuation. Do the current earnings of SoftBank Group make the latest price move look sensible, or is the stock now leaning more on hope than on its reported profits.
- Over the past 3 years the stock has gained about 220%, which puts a lot of previous optimism about SoftBank Group's earnings power under the microscope today.
- Fresh headlines around large scale AI investments, including new funding vehicles and data center projects, can reshape expectations for how quickly SoftBank Group might turn ambitious spending into steady earnings.
- Your read on SoftBank Group is one view; the desks covering it have another. See what analysts think SoftBank Group's shares could be worth.
The issue now is whether the earnings that SoftBank Group currently generates are enough to make today's share price look well supported.
If you want a reference point for how other AI focused stocks are being priced after this kind of volatility, scan through the 55 AI infrastructure stocks.
Is SoftBank Group Still Cheap on Earnings?
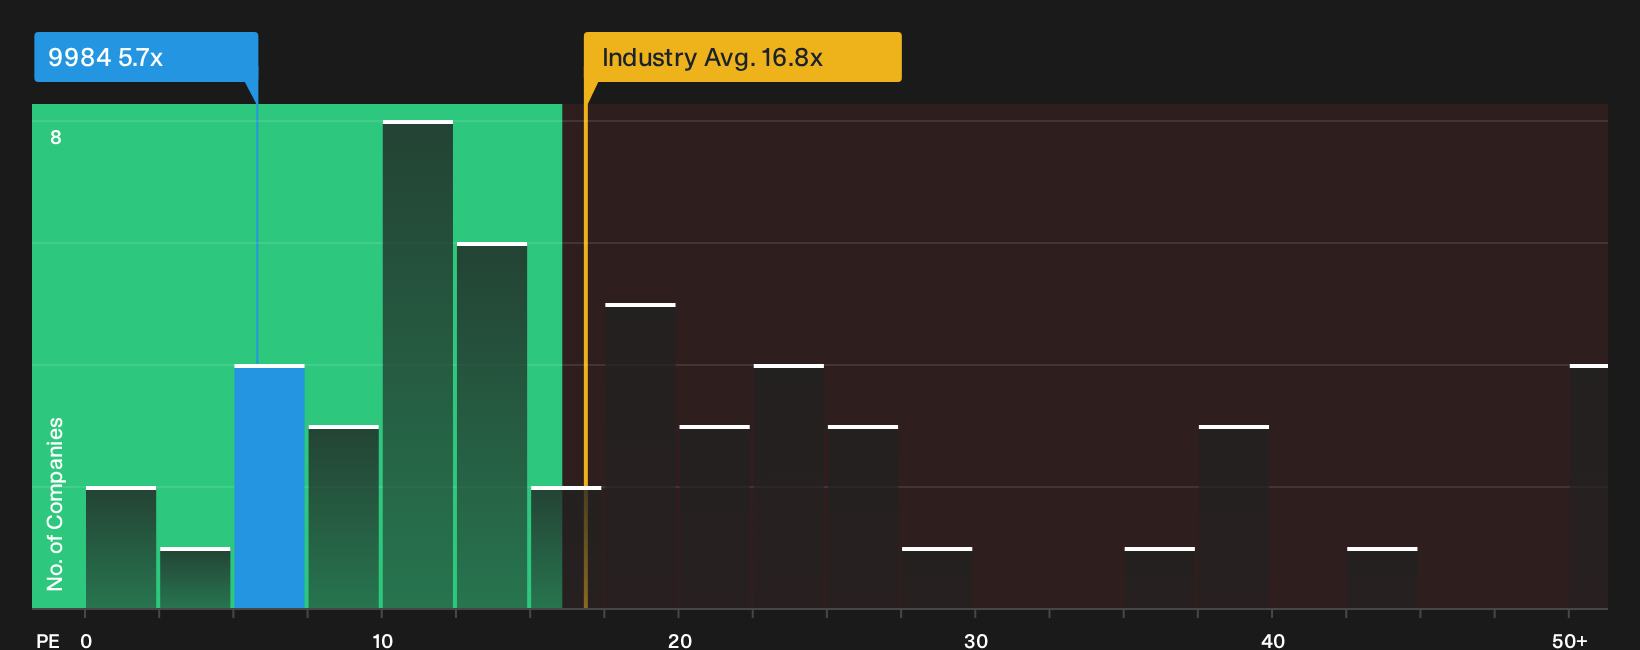
The P/E multiple is a straightforward way to see what investors are paying today for each unit of earnings that SoftBank Group generates. On this yardstick, the stock trades on roughly 5.7x earnings, which is far below the Wireless Telecom sector average of about 14.8x and also under the broader peer group around 18.2x.
The fair value framework, which adjusts for SoftBank Group's own risk profile, business mix and growth assumptions, points to a higher P/E than where the shares are now. As a result, the current valuation screens as undervalued on this measure. Despite SoftBank's push for large AI funding vehicles and the scrutiny that brings to its balance sheet, the market is still applying a sizeable discount to what similar earnings streams in this space typically command. Explore the numbers behind SoftBank Group's P/E valuation.
The SoftBank Group Narrative: What Would Justify Today's Price?
Narratives for SoftBank Group pick up where this valuation question leaves off by spelling out which assumptions about future growth, profitability and earnings power would need to hold for the shares to look meaningfully cheaper or richer than today. Each storyline lays out the key inputs behind its view of fair value in plain terms, so you can weigh those expectations against SoftBank Group's reported results as they come through on Simply Wall St's Community page.
SoftBank Group followers are split between those who see the AI build out as a discounted asset story and those who worry the excitement already runs ahead of itself.
Bull case: 36% undervalued
"SB Energy’s planned Nasdaq listing, backed by roughly 8.8 GW of contracted AI data center capacity and an estimated US$430b lease revenue backlog that is still to be realized..."
Discover why this Narrative puts SoftBank Group at 36% undervalued.
Bear case: 10% overvalued
"SoftBank’s exposure to frontier AI through strategic investments positions it to benefit significantly as global AI spending accelerates..."
Explore why this Narrative puts SoftBank Group at 10% overvalued.
One more SoftBank Group check that belongs beside the earnings math
Price and profit only tell part of the story, because the people deciding how SoftBank Group spends capital and the way their rewards are structured can tilt long term outcomes in powerful ways. See who runs SoftBank Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com