


How Earnings Beat Will Impact Enbridge (TSX:ENB) Investors
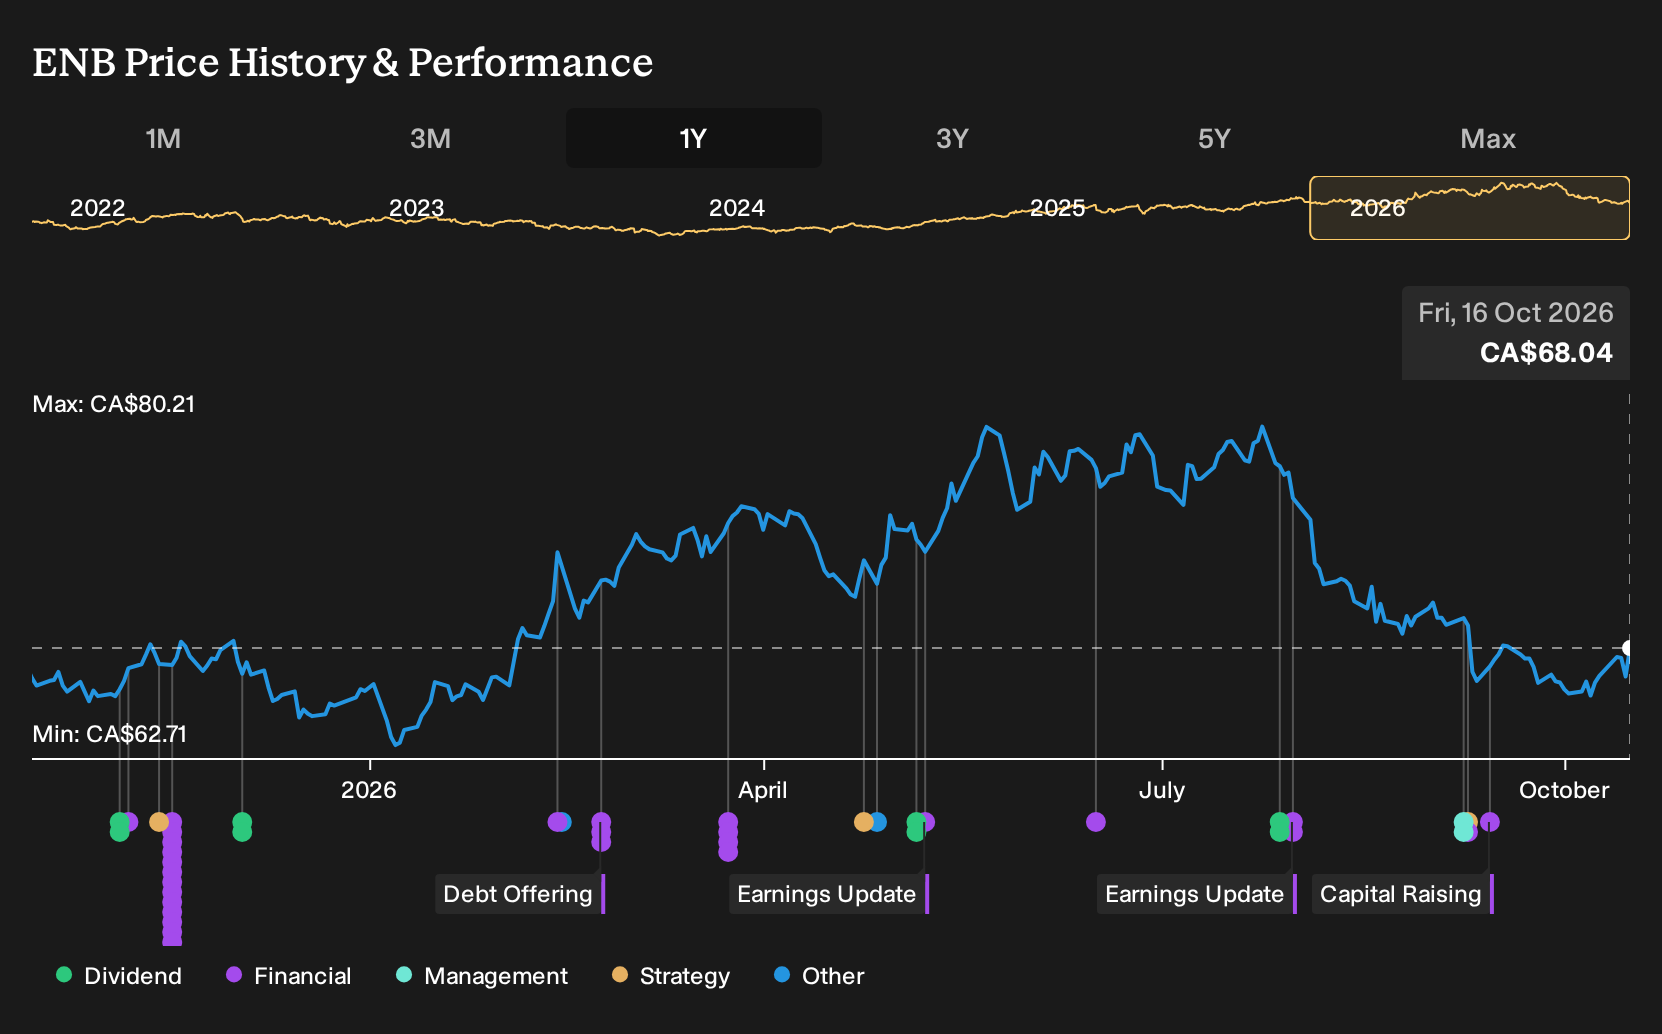
- Enbridge recently reported quarterly revenue and earnings per share that were above consensus estimates, highlighting solid recent operational performance across its energy infrastructure assets.
- The earnings beat has prompted analysts to revisit their forecasts, which can sharpen the focus on how Enbridge converts its large secured project backlog into future cash flow.
- We will now explore how Enbridge's recent earnings outperformance could influence the broader investment narrative around its long term infrastructure build out.
See how Enbridge's earnings surprise compares with other income-focused infrastructure plays using our curated list of 3 dividend fortresses.
Enbridge Investment Narrative Recap
Owning Enbridge means buying into a long build out of regulated and contracted energy infrastructure that aims to turn a large secured project backlog into steadier cash generation. The recent revenue and EPS beat supports confidence that existing pipelines, gas networks and renewable assets are running relatively well, but it does not radically change the story on its own.
The short term swing factor is still execution on that roughly C$41b secured backlog while keeping debt within the 4.5x to 5.0x target range. Leverage and dividend coverage remain the key pressure points. Any delays or weaker returns from new projects or the Tallgrass and Salt Creek assets could keep balance sheet flexibility tight.
Against that backdrop, the most relevant recent development is Enbridge’s push to integrate the Tallgrass and Salt Creek Midstream acquisitions, which were bought for about C$4.5b at single to low double digit EBITDA multiples. These systems plug into its broader crude and gas network and are intended to support future earnings and distributable cash flow.
For you as a holder or potential holder, Tallgrass and Salt Creek sit right at the junction of opportunity and risk. Strong integration and steady utilization would help absorb Enbridge’s elevated leverage and support its large growth backlog. Softer asset performance or slower synergy capture would work the other way and could keep project funding and dividend headroom under scrutiny.
Enbridge's current earnings are CA$5.7b and analysts expect CA$8.1b of earnings and CA$79.3b of revenue by 2029, which implies revenue falling 1.7% per year and an earnings increase of about CA$2.4b from today.
Uncover why Enbridge's fair value indicates a 16% potential upside to its current price, which could narrow quickly as investors re-rate the story.
Exploring Other Perspectives
Six fair value views from the Simply Wall St Community put Enbridge anywhere between CA$47 and roughly CA$269, which is a huge spread for one stock. That gap reflects very different expectations for how the C$41b project backlog and Tallgrass or Salt Creek risks play out. Use it as a prompt to compare multiple viewpoints before deciding your own stance.
Explore 5 other Enbridge fair value estimates, including one that suggests as much as 31% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Enbridge research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enbridge. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enbridge's overall financial health at a glance.
Looking For More Ideas Beyond Enbridge?
If Enbridge has sharpened your focus on income, balance sheet strength and long term cash generation, it can be useful to line it up against a wider watchlist built from different angles of the market.
- For investors who want resilient balance sheets and solid fundamentals at the foundation of their portfolio, start with a list of solid balance sheet and fundamentals (8 results) to spot companies that may handle stress more effectively.
- If your priority is uncovering potential value where quality and price look out of sync, scan through 10 high quality undiscovered gems to see which businesses fit that profile.
- Income focused readers who care most about reliable cash distributions can review 3 dividend fortresses to find stocks with higher yield profiles and robust financial backing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com