


ASML Holding (ENXTAM:ASML), What Is Drawing Fresh Attention Now?
ASML Holding (ENXTAM:ASML) closed a long running shelf registration on October 15, covering 1,443,753 ordinary shares tied to an employee share offering in the amount of about US$136.7m.
For context, ASML Holding’s share price has shown strong long term momentum, with a year to date share price return of 49.77% and a 1 year total shareholder return of 69.79%. This comes even as the 7 day share price return fell 7.77% amid a wider tech sell off and mixed reactions to its recent earnings, guidance, dividend and buyback announcements.
Scan how ASML Holding fits into the wider AI buildout by comparing it with 55 AI infrastructure stocks, which is now driving the semiconductor equipment theme.
Bulls point to ASML Holding’s record earnings, full year guidance and tight EUV supply. Bears focus on premium pricing, AI funding worries and the recent share pullback. Which story do today’s numbers actually support as you weigh valuation next?
Most Popular Narrative: 17% Undervalued
ASML Holding last closed at €1,477.20, while the most followed valuation narrative pegs fair value at €1,780. The gap is not huge, but it matters once risk, China competition and AI capital spending are all on the table at the same time.
Valuation multiple risk is therefore at least as important as operating risk. At the current price, ASML trades at roughly 33 times my 2027 EPS estimate. That is defensible for a company with a strong balance sheet and a highly differentiated technology position, but it leaves little room for revenue postponements or a lower terminal-growth narrative. The stock can perform well without becoming conventionally cheap, but large upside requires earnings to grow into the multiple quickly.
See why 43 investors see ASML Holding as 17% undervalued.
Result: Fair Value of €1,780 (UNDERVALUED)
Still, the story can shift quickly if Chinese lithography efforts gain traction faster than expected or if AI driven chip capex cools just as ASML lifts capacity.
Find out about the key risks to this ASML Holding narrative.
Another View: ASML Holding Through a Cash Flow Lens
There is a different read on ASML Holding when the focus shifts from earnings multiples to future cash generation. The SWS DCF model values the shares at about €955.55, well below the current price of €1,477.20, which points to an overvalued outcome rather than a discount.
This kind of gap suggests meaningful valuation risk if cash flows progress closer to the DCF path than to the more optimistic earnings-based narrative. It raises a simple question for investors weighing ASML Holding today: Which set of assumptions feels more realistic when growth timing and competitive threats are still in play?
Look into how the SWS DCF model arrives at its fair value.
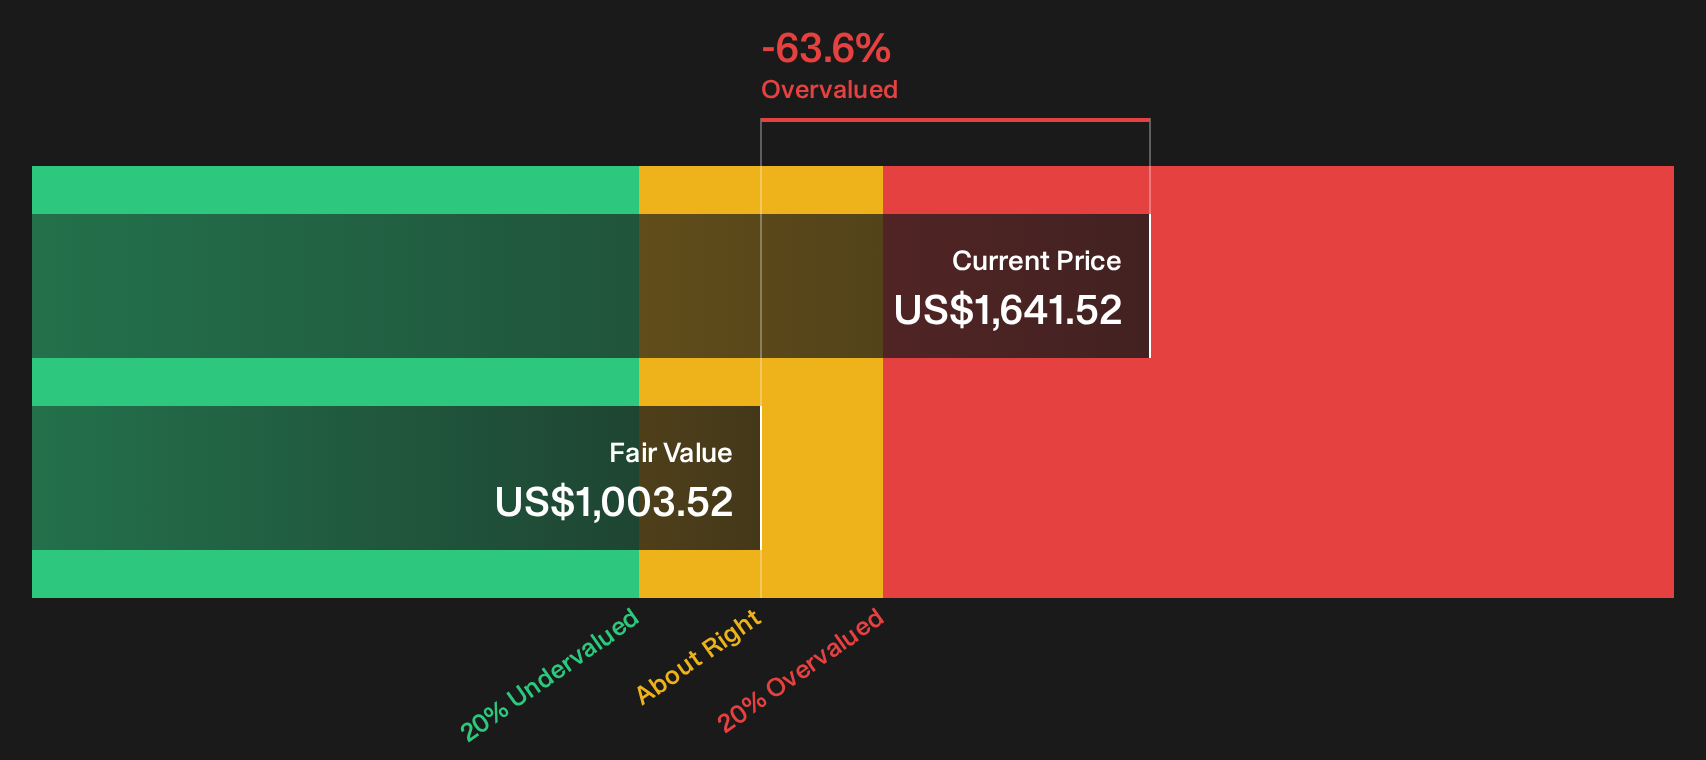
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASML Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With ASML Holding caught between optimism about AI demand and concerns about its rich valuation, it is important not to remain undecided. Go through the data, weigh both sides of the story, and pressure test your own thesis with the 5 key rewards and 1 important warning sign.
Looking for more ASML Holding sized opportunities?
You have weighed ASML Holding. Now widen the lens and stress test your portfolio ideas with a few focused stock lists built from clear, data driven rules.
- Target potential mispricing by reviewing companies that current models flag as offering value upside through the 191 high quality undervalued stocks.
- Build a steadier income stream by scanning for higher yield payouts in the 213 dividend fortresses.
- Limit portfolio shocks by filtering for sturdier balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com