


What Xero Investors Missed Before A 60% Fall
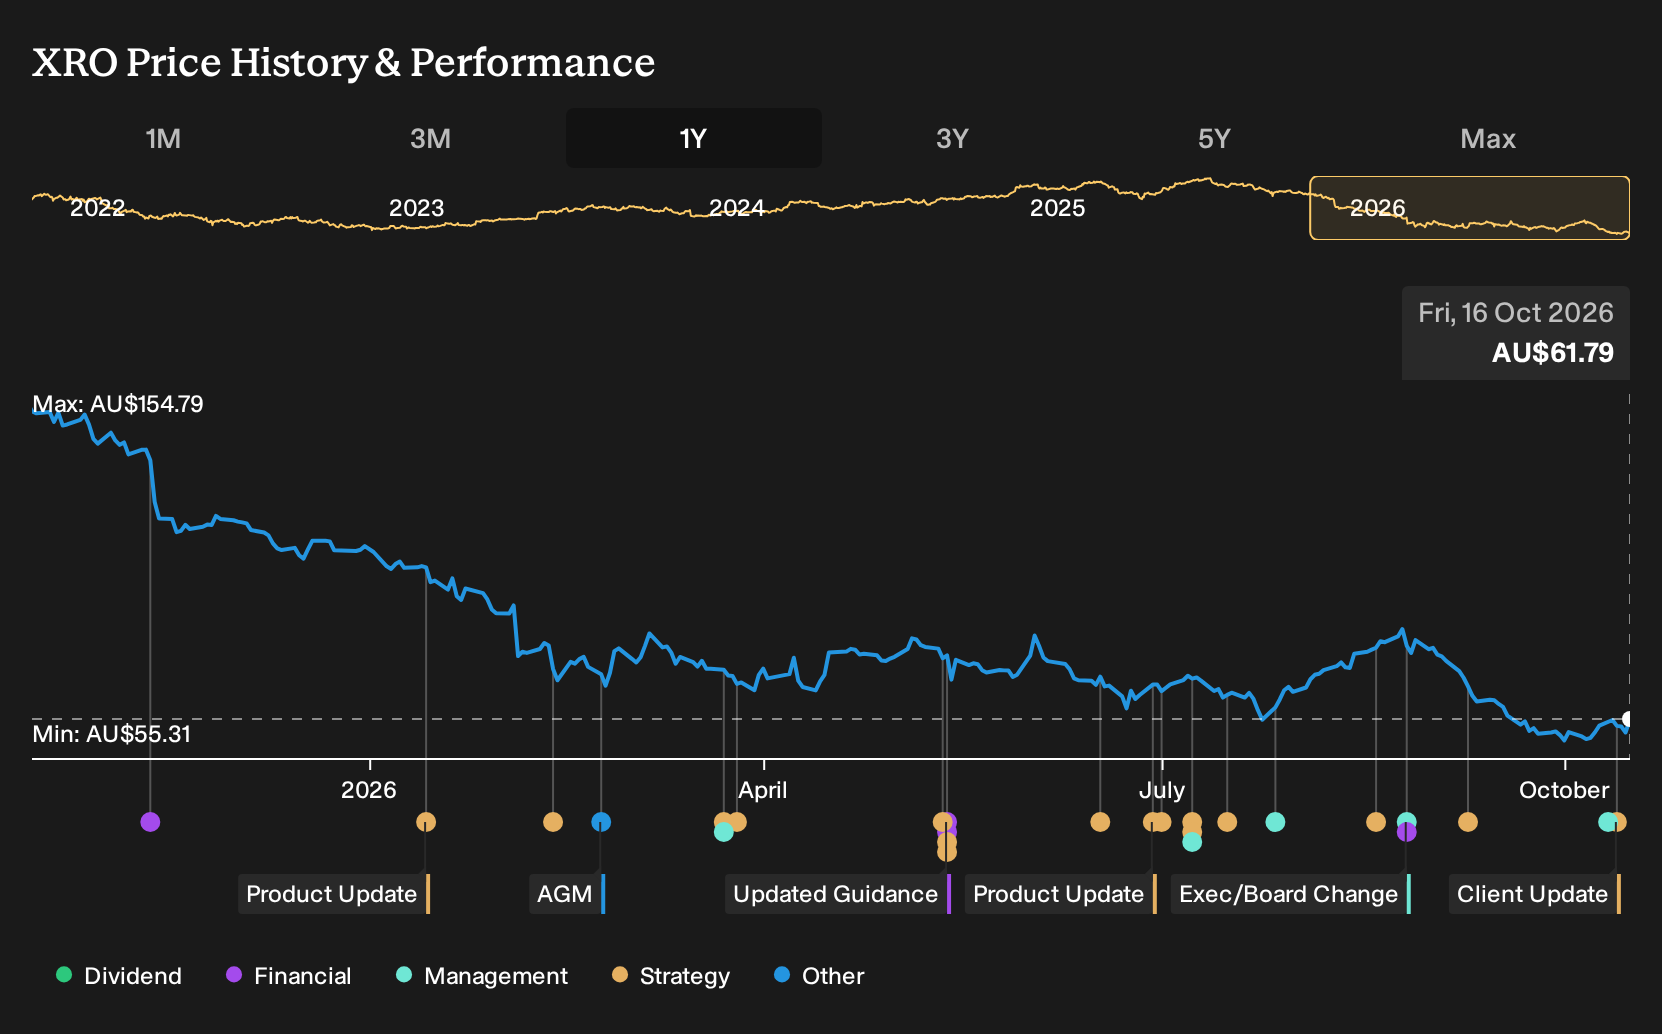
Xero’s latest FY26 result landed with a thud for many holders, as 31% revenue growth came alongside a much weaker net margin and fresh questions about the Melio acquisition and AI spending. Investors who held Xero over the past year are down 59.9%, including dividends. If you had put money in on 16 October 2025 expecting AI features and US expansion to pay off, how should today’s mix of higher sales and thinner profits reshape your expectations?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Xero is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Two Stories Xero Investors Were Really Weighing
The shares cost A$155 at the start, and anyone looking at Xero then had to decide which story about its future sounded more convincing.
On the bullish side, the narrative saw Fair Value at A$195, built on AI features like Just Ask Xero, U.S. payroll expansion and an assumption that revenue might grow 18.1% a year with profit margin at 18.1%.
The bearish view put Fair Value at A$100, focused on cyber risk and heavier regulation, and warned that rising compliance and security spend could pressure earnings even if revenue grew.
What The Results Changed For The Xero Thesis
Xero’s FY26 picture gave both sides new facts to work with. Revenue for H2 2026 was NZ$1,558.9m compared with NZ$1,106.8m in H2 2025, helped by Melio driven US growth and new AI products like JAX and XeroForce. Net income excluding extra items fell to NZ$32.6m and net margin moved from 12.0% to 2.1%, so profitability momentum in the optimistic case stayed unproven. The evidence cut both ways.
The useful takeaway is clear. When a story rests on AI and expansion improving earnings, do not just track top line and product launches. Keep checking net income and margin direction against the original forecast and ask whether new spend heavy initiatives are helping or diluting that part of the thesis.
What Buying Xero Today Would Really Be Betting On
Xero trades at A$61.79 today, after a loss of 59.9% over the past year from A$155. The current bullish Narrative sees Fair Value above this price, based on AI enabled products, subscriber trends and cost structure.
Before treating the fall as a potential opportunity rather than a warning, a buyer would need to believe Xero can grow while holding operating expenses relatively steady.
"Xero has high scalability of its products, with current gross margin of approximately 88%. Higher revenue would be applied across relatively static operating expenses, once Xero reaches the point where it can continue steady feature rollouts without needing to increase spending relative to revenue. This would result in higher net profit margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 32% below our estimate - converts affiliate funds under management into higher margin platform fee income.
- Company 2 - 49% below our estimate - wins recurring mining and civil contracts as project pipelines and tenders expand.
- Company 3 - 48% below our estimate - secures data center and smart building work as clients upgrade digital infrastructure.
Three companies from the same screener. Open the full list of 4 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com