


PNC Financial (PNC) Q3 Earnings Sharpen Focus On Margins And Credit
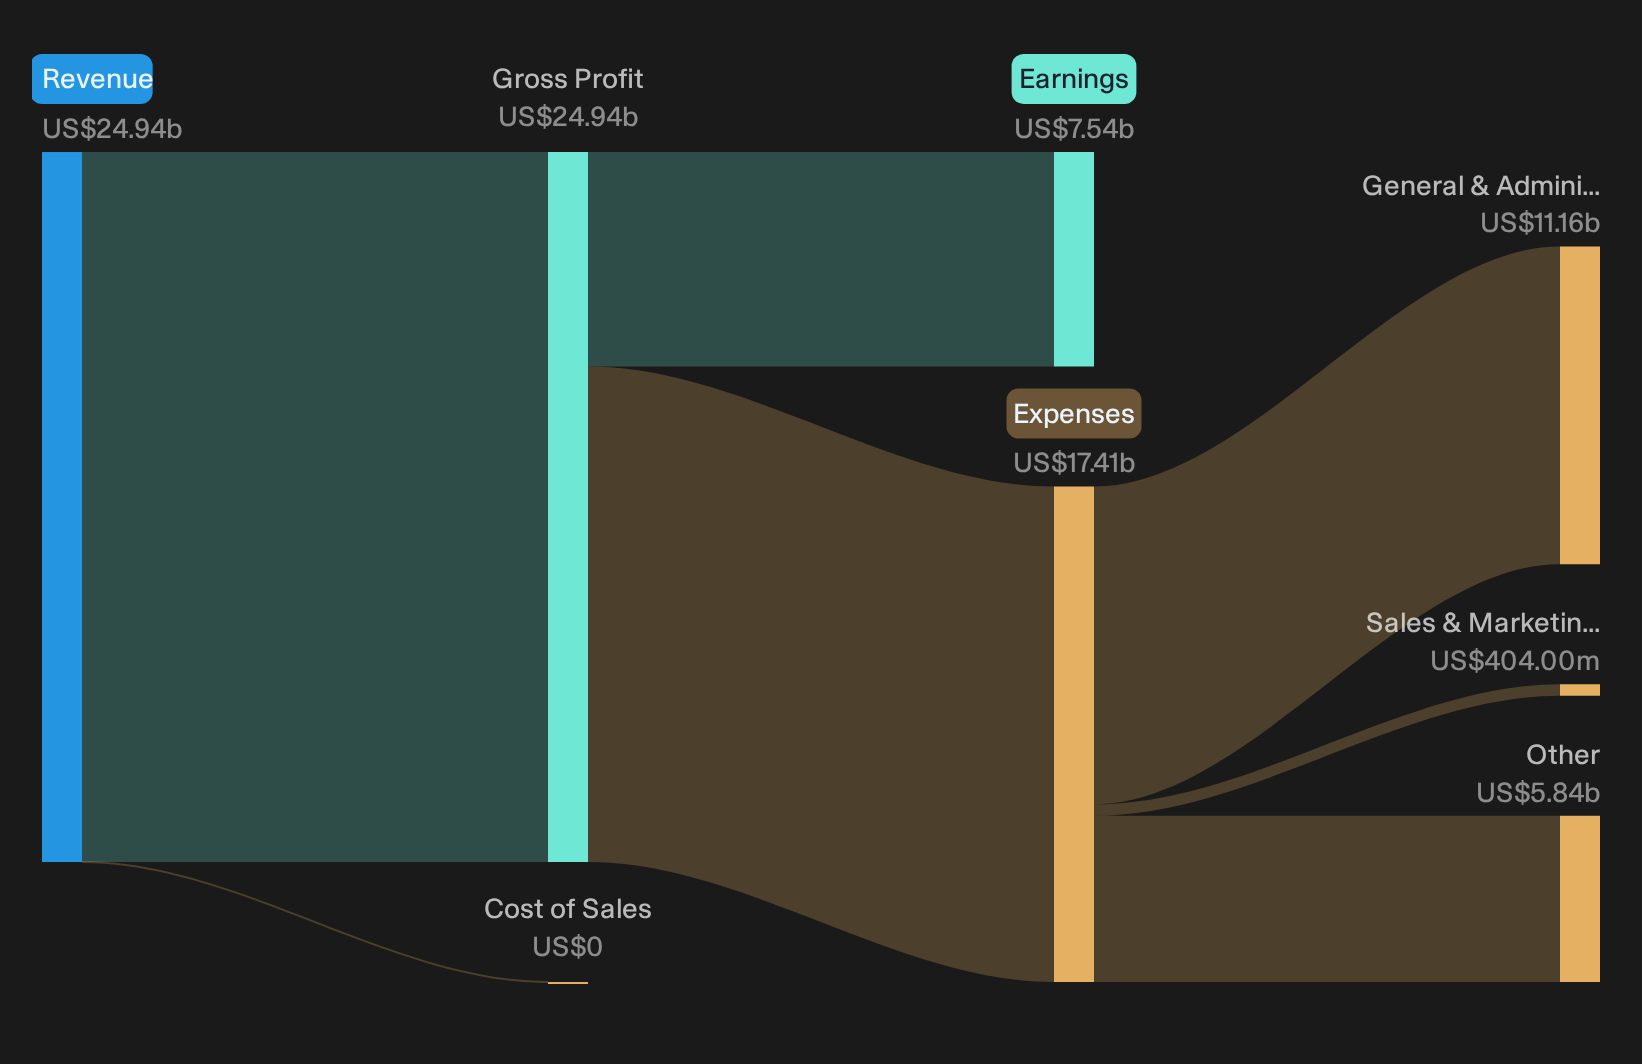
PNC Financial Services Group shares were up 1.1% on Friday at US$217.39, even though the stock is still down over the past month and quarter. That muted price response sits alongside a punchy Q3 2026 print, with basic earnings per share at about US$5.00 and net income around US$2.0b.
The real story sits on the income statement. Net interest margin held close to 3% while the cost to income ratio improved to 57%. For a large regional bank, that mix of earnings power and efficiency is what will matter far more for long term holders than a 1% move in the stock.
Like the earnings power at PNC Financial Services Group but want a broader set of banks with strong balance sheets and disciplined cost control to compare it against? Run your checklist against our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$6,373m vs. US$5,748m (up about 10.9%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$2,006m vs. US$1,723m (up about 16.4%)
- Basic EPS (Q3 2026 vs Q3 2025): US$5.00 vs. US$4.35 (up about 15.0%)
- Net Interest Margin (Q3 2026 vs Q3 2025): 2.94% vs. 2.79% (improved by 0.15 percentage points)
Skip the headline EPS beat. Ask Charlie what PNC said about its AI investment plans.
PNC’s AI And Expansion Ambitions On Trial
For the bullish story on PNC Financial Services Group, the crux is whether heavy spending is actually turning into operating leverage and healthier fee streams.
"PNC Financial Services Group expects its multi year AI and automation program, which targets about 40 points of operating leverage from 2025 to 2030 on top of earlier gains and focuses on roughly 171 opportunities and US$1.4b of addressable spend, to further support net margins and earnings."
Q3 results move this from theory toward evidence. Net interest margin held near 3% while the cost to income ratio improved to 57%. Noninterest income for the year to date grew 15%. Expenses fell 3% quarter on quarter excluding items. That combination suggests early traction on cost discipline while tech and branch investment continues.
Testing PNC’s Fee Sensitivity And Credit Fears
On the cautious side, investors question whether fee dependence and credit risk could undo these gains just as AI and branch projects ramp.
"PNC Financial Services Group relies heavily on continued growth in fee based businesses such as capital markets, advisory, card, cash management and asset management. These areas can be sensitive to client activity and market conditions that are not covered in the current data, so any pullback could limit the contribution of noninterest income to revenue and earnings."
Recent numbers are mixed rather than alarming. Quarterly fee income declined 6% from an elevated Q2 as capital markets cooled, yet year to date noninterest income is still up 15%. Net loan charge offs increased to US$226m from US$198m a year earlier, which points to some credit normalization that bears have been watching for.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Disconnects
PNC Financial Services Group recently reported results that did not immediately shift the share price. The real opportunity sits in spotting stocks that could be undervalued before sentiment catches up.
- Company 1 - 35% below our estimate - uses a fast growing super app to steer users toward secured lending products and manage funding costs.
- Company 2 - 30% below our estimate - embeds custom chips and software at key digital infrastructure points to process and secure heavy data traffic.
- Company 3 - 45% below our estimate - sells a digital banking platform that consolidates branches and channels into unified mobile focused customer access.
Those are three of them. See all 33 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com