


How Raised Earnings Estimates Will Impact Old Second Bancorp (OSBC) Investors
- Old Second Bancorp recently drew attention as analysts updated their models ahead of the September 2026 quarter, with consensus pointing to higher earnings and revenue and a fresh earnings release scheduled for 21 October 2026.
- The focus now sits on how Old Second Bancorp’s core banking engine, including its net interest margin and specialty lending economics, lines up with the more optimistic earnings assumptions.
- We will now look at how Old Second Bancorp's investment narrative could be shaped by these higher earnings expectations and estimate revisions.
Spot opportunities around Old Second Bancorp by scanning a curated set of resilient financials in the 32 resilient stocks with low risk scores that may handle earnings surprises with fewer shocks than the wider market.
Old Second Bancorp Investment Narrative Recap
For someone holding Old Second Bancorp, the core belief is that a high net interest margin, low deposit costs and a growing specialty lending book can keep supporting solid earnings power, even as growth expectations moderate. The upcoming September 2026 quarter is mainly a check in on whether that engine is still running as modeled.
The short term swing factor is how credit costs and net interest income trend relative to recent patterns of elevated net charge offs and slower top line growth. The biggest risk is that credit issues in commercial real estate or powersports lending linger, which could chip away at that high margin profile if loss rates remain stubborn.
The most relevant recent datapoint is the expectation of higher earnings and revenue for the September 2026 quarter, with Old Second Bancorp carrying an Earnings ESP of +1.54% and a Zacks Rank #2. That combination has coincided with three earnings beats in the last four quarters, so this update matters as a sentiment check on execution.
For catalysts, that earnings setup sits alongside a story built on a tax equivalent net interest margin above 5%, deposit costs near 1.00% and specialty loans with APRs above 10%. If the 21 October release shows those pieces still intact while credit issues remain contained, it would support the idea that the business can keep turning a modest revenue growth profile into consistent profitability.
Old Second Bancorp Forecast Setup In One Snapshot
Old Second Bancorp's narrative projects US$357.0 million in revenue and US$138.4 million in earnings by 2029. This lines up with analysts building in 1.5% yearly revenue growth and an earnings increase of about US$46.0 million from current earnings of US$92.4 million.
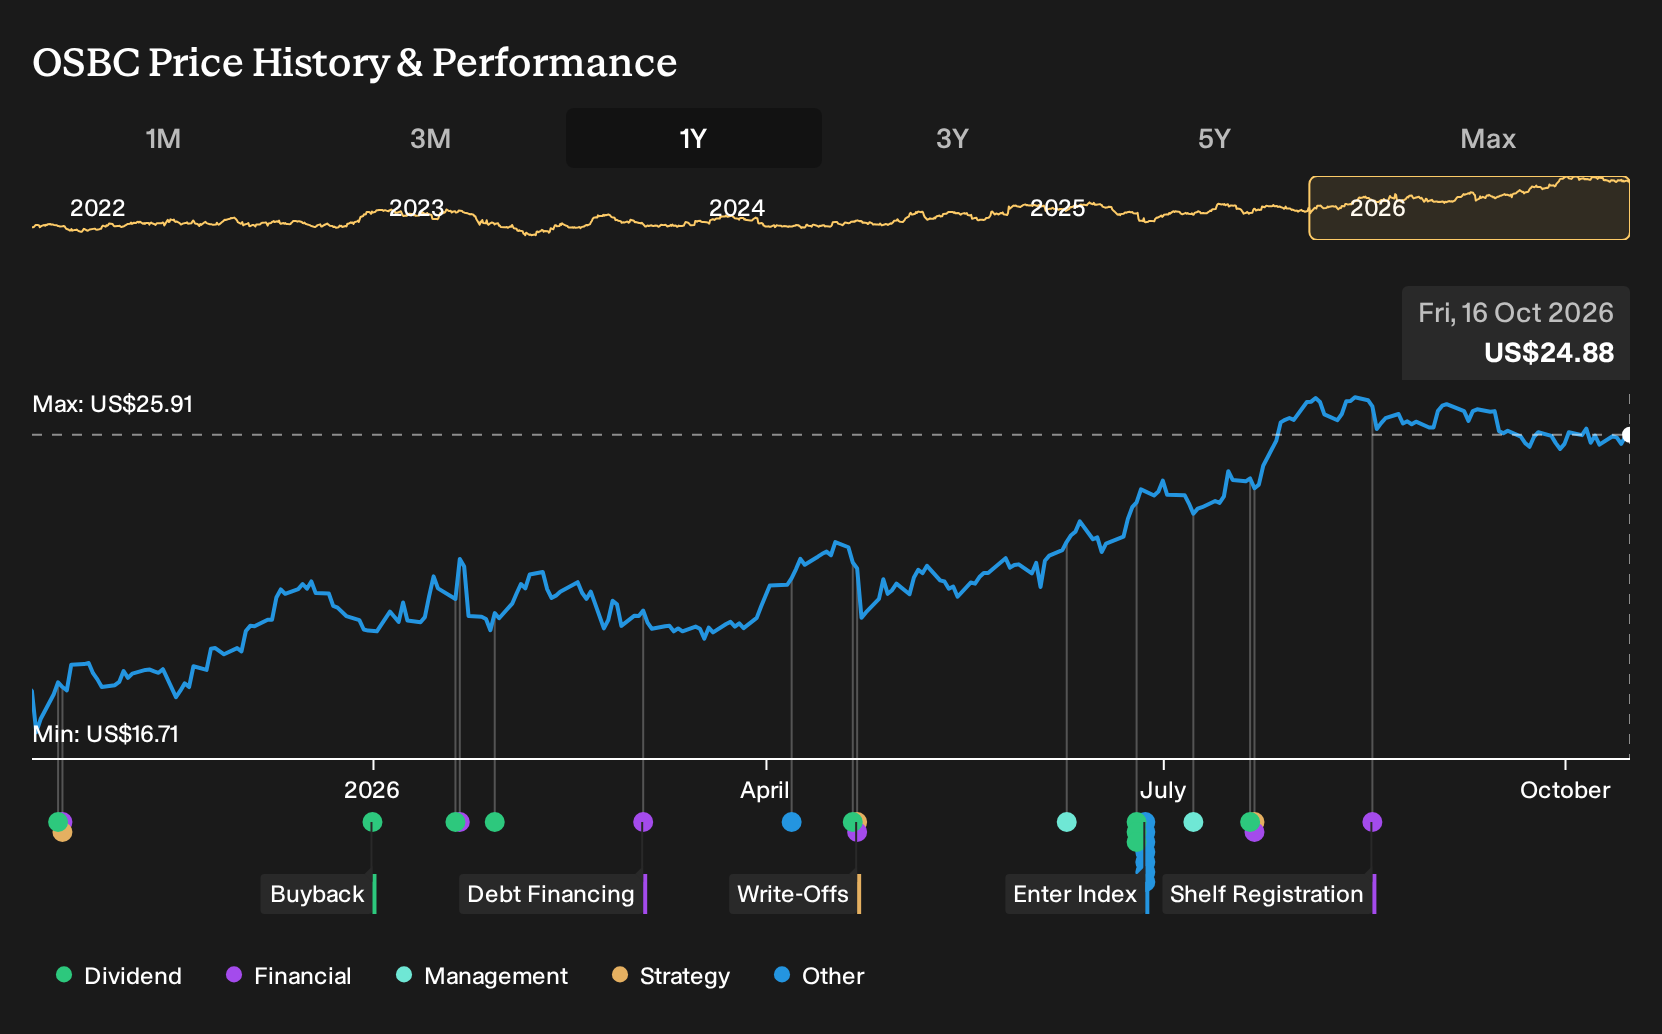
Uncover why Old Second Bancorp's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Old Second Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Second Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Second Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Old Second Bancorp?
Once you have a view on Old Second Bancorp, it can help to set it alongside a wider watchlist of stocks that share some of the qualities you care about most, whether that is value, resilience or income strength.
- If you want potential value ideas with solid fundamentals, start by scanning a curated set of companies through the 33 high quality undervalued stocks.
- For investors who care most about balance sheet strength and financial robustness, the list of solid balance sheet and fundamentals (25 results) can quickly surface candidates worth a closer look.
- If income is a key part of your plan, use the 8 dividend fortresses to focus on companies offering higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com