


Spin Master (TSX:TOY) Stock May Be A Bargain On Sales
Spin Master has delivered a mixed ride for shareholders, with the stock at C$20.65 and a long term chart that includes some steep declines alongside more recent gains. The question now is whether that current share price lines up with what the company generates in sales.
- Over the past 5 years the share price has fallen 47.6%, which puts a lot of weight on whether the market is now paying an appropriate price for the company’s revenue base.
- The business depends on turning its toy and entertainment brands into consistent cash inflows, which can affect how much value investors are willing to place on each dollar of sales.
- The analysts covering Spin Master have run their own numbers. See what analysts think Spin Master's shares could be worth.
The issue now is whether Spin Master’s current share price is justified by its sales when measured against the Fair Ratio benchmark.
To cross check whether Spin Master's 5 year share price decline lines up with what investors are paying for sales, it can help to compare that P/S story with 5 high quality undervalued stocks
Is Spin Master Still Cheap on Sales?
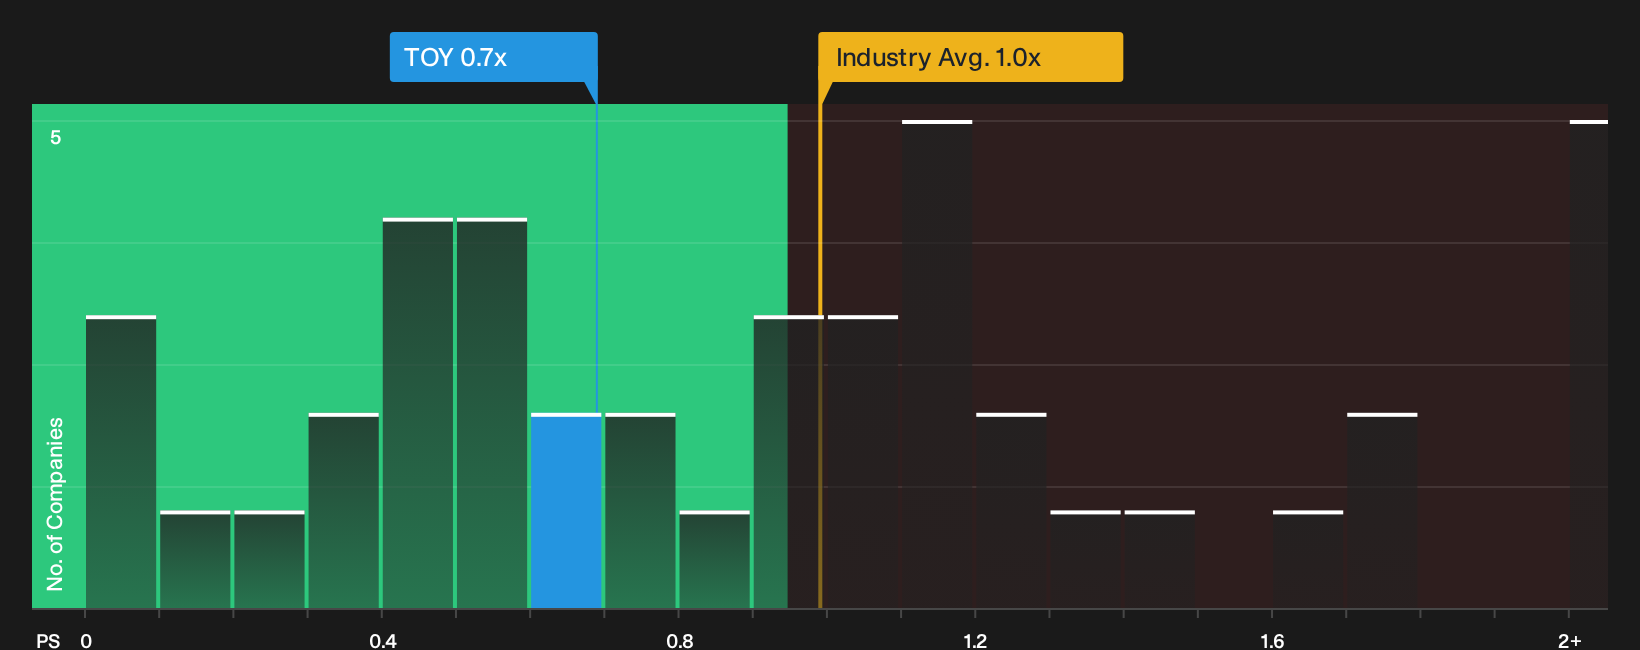
P/S is a useful lens for Spin Master because toys and entertainment rely heavily on branded sales rather than short term earnings swings. On this measure, the stock trades on a P/S of about 0.7x, which is below both the Leisure industry average of roughly 1.0x and the peer group near 1.9x.
The tailored Fair Ratio, which blends Spin Master’s sector, size, margins and risk profile into one benchmark, comes in higher than the current P/S level. That points to the shares screening as undervalued on sales relative to what this model would expect, with the market putting a smaller tag on each dollar of revenue than either the industry or peer pack. Investors who focus on top line driven businesses may want to explore why the market is applying this discount and whether they agree with it. Explore the numbers behind Spin Master's P/S valuation.
The Spin Master Narrative: What Would Justify Today's Price?
Narratives on Spin Master pick up where the P/S puzzle leaves off by mapping out what kind of future growth, profitability and earnings path would need to play out for the stock to be worth materially more or less than today’s price, and they sit on Simply Wall St’s Community page. Rather than stopping at a single valuation output, they describe the set of business outcomes that number relies on so you can see over time whether reality is tracking the script.
One of the top community narratives on Spin Master: 44% undervalued
"The current valuation implies the market is still discounting Spin Master as a traditional toy company rather than fully reflecting the company’s multi-channel IP monetization plans…"
Discover why this Narrative puts Spin Master at 44% undervalued.
Before you make a move on Spin Master, there is one more angle to check
Valuation only tells part of Spin Master’s story. The research checks also flag specific areas of concern that can change how you frame the risk side of the thesis. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com