


Is Innovent Biologics (SEHK:1801) A Bargain After SYCUME Phase 3 Results?
Innovent Biologics (SEHK:1801) is back in focus after reporting that SYCUME met both primary and key secondary endpoints in a Phase 3 trial for inactive thyroid eye disease in China.
The SYCUME update comes after a mixed period for Innovent Biologics, with the share price returning 13.01% year to date but easing over the past month with a 30-day share price decline of 5.37%. At the same time, the 3-year total shareholder return stands at 101.93% and the 1-year total shareholder return is 2.53%, indicating that long-term holders have seen gains even as shorter-term momentum has softened.
Scan beyond Innovent Biologics and compare this TED milestone against 127 healthcare AI stocks that are also pushing the frontier of data-driven treatments and precision medicine.
After SYCUME’s latest data and a share price that is up 13.01% year to date but softer over the past month, Innovent Biologics now forces a timing call. Is it better to step in at this level, or to wait for a cheaper reset?
Price-to-Earnings of 107.2x: Is it justified?
On simple multiples, Innovent Biologics is priced richly, with a P/E of 107.2x at a last close of HK$89.05 while its own DCF estimate points to a fair value of HK$153.57.
The P/E ratio compares what investors pay today for each dollar of current earnings. For a biopharma group like Innovent Biologics, a high P/E often reflects expectations that profits could change meaningfully as the pipeline converts into commercial products.
Here, the current earnings profile is paired with several moving parts. Earnings grew 8.8% over the past year and are forecast to grow 33.46% per year, while the business has high quality earnings but a low 5.9% Return on Equity and profit margins that moved from 9.9% to 7.8%. The combination suggests the market may be paying up heavily for the earnings it sees today, relative to both the firm’s own profitability metrics and the cash flow value implied by the SWS DCF model.
The comparison with peers is stark. Innovent Biologics trades on a P/E of 107.2x, which is very expensive versus the Hong Kong Biotechs industry average of 15.9x and the peer average of 21.7x. It is also well above an estimated fair P/E of 37.5x, a level the market could move towards if sentiment or expectations reset.
Explore the SWS fair ratio for Innovent Biologics.
Result: Price-to-Earnings of 107.2x (OVERVALUED)
Still, the Innovent Biologics story can be knocked off course if SYCUME or other pipeline assets face regulatory setbacks, or if the current 107.2x P/E scares off buyers.
Find out about the key risks to this Innovent Biologics narrative.
Another View: SWS DCF model paints a very different picture
The rich 107.2x P/E suggests investors are paying up for Innovent Biologics today. The SWS DCF model tells a different story, with a fair value estimate of HK$153.57 versus the current HK$89.05, implying the stock trades at a 42% discount.
That kind of gap cuts both ways. It could signal a margin of safety if cash flows unfold as modeled, or it could highlight how sensitive any DCF is to its inputs. The key question is which lens investors rely on more, given that SYCUME and the wider pipeline are still moving through the clinic.
Look into how the SWS DCF model arrives at its fair value.
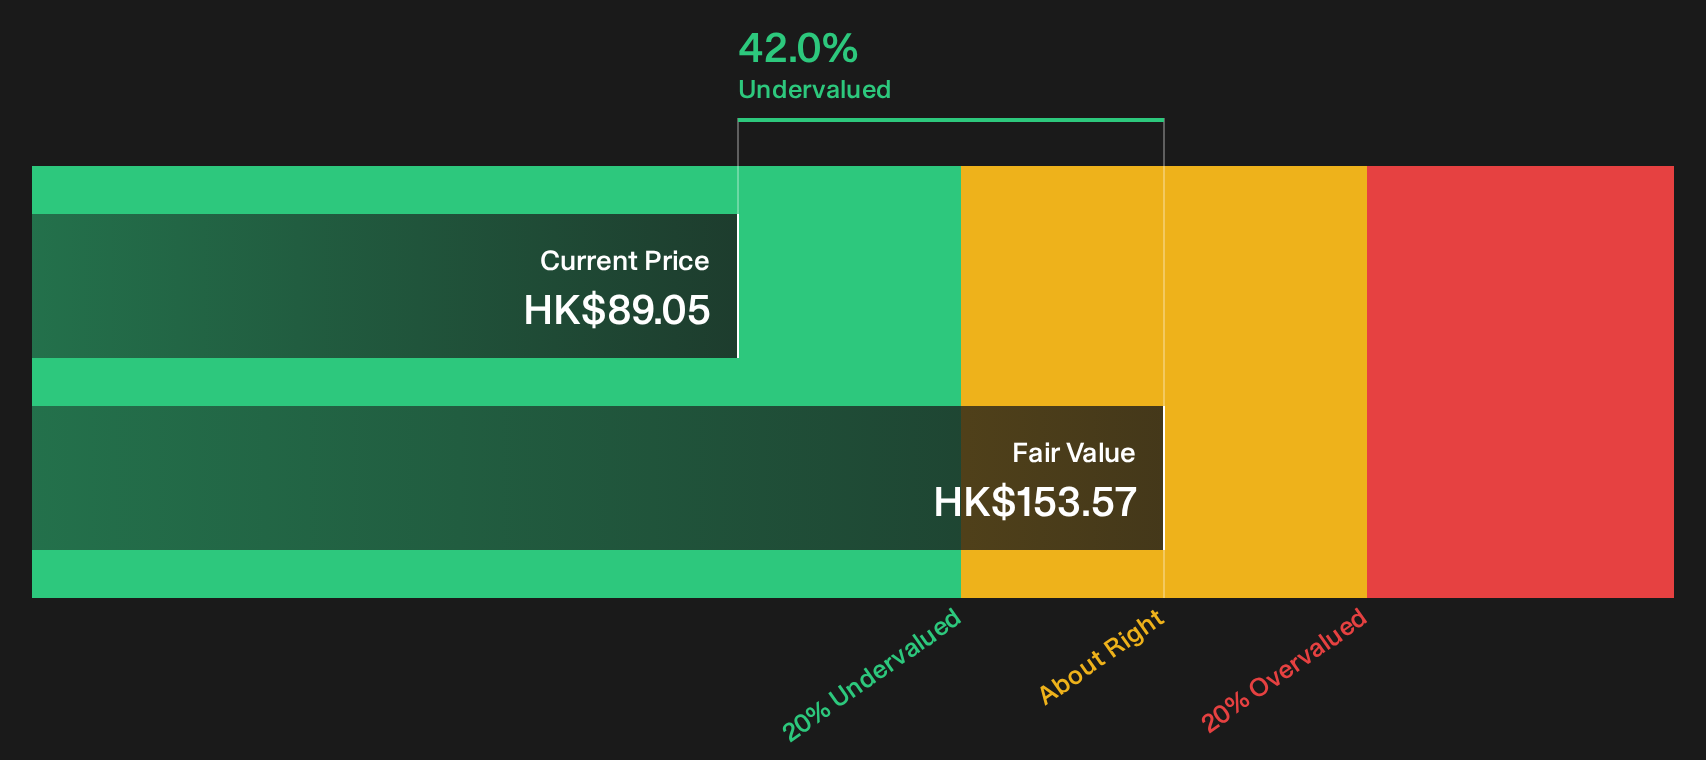
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innovent Biologics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Innovent Biologics so far, or a clear signal hiding in plain sight. If you want to move quickly and build your own view before sentiment shifts again, start by weighing the upside case reflected in the 4 key rewards.
Looking for more Innovent Biologics style ideas?
If Innovent Biologics has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more options before the crowd catches on.
- Target resilient opportunities with steadier profiles by reviewing a 233 resilient stocks with low risk scores that can help you focus on companies with fewer red flags.
- Hunt for potential bargains by scanning the 192 high quality undervalued stocks that pairs healthy fundamentals with prices that may not fully reflect them yet.
- Strengthen your core holdings by focusing on balance sheet resilience with a list of solid balance sheet and fundamentals (203 results) that can support your portfolio through tougher periods.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com