


What International Money Express Holders Got Wrong Before The Slide
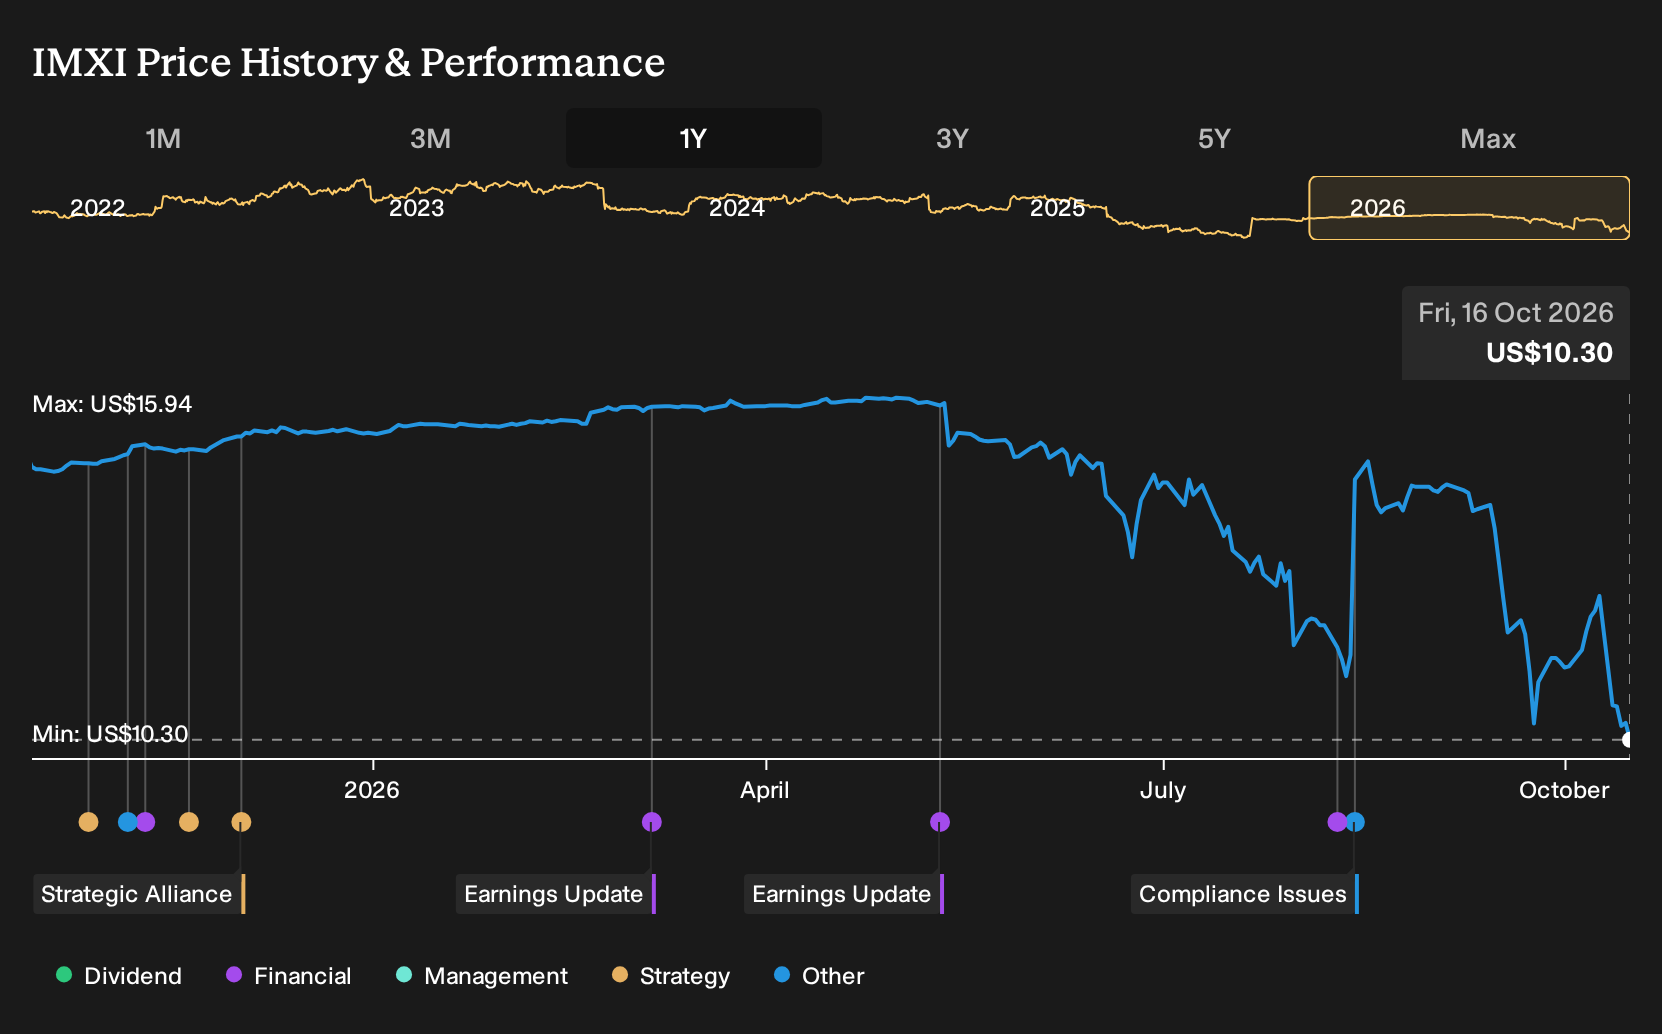
If you had decided in October 2025 that International Money Express looked too complicated and moved on, the past year might feel like a bullet dodged. Investors who held International Money Express over the past year are down 30.2%, including dividends. Q2 2026 results later showed revenue at US$131.162 million and net income at US$4.205 million, with margin pressure clearly visible. The real question is which of the earlier digital growth hopes or disruption risks offered the sharper warning signal.
International Money Express has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Two Futures Investors Saw For International Money Express
The shares cost US$14.76 at the start of the period, so anyone looking at International Money Express then had to decide which story about its future sounded more realistic.
The optimistic Narrative pointed to a Fair Value of US$16, described as a rough guide to what the assumptions implied rather than a fixed truth. This was based on the idea that revenue could grow 1.5% a year with profit margins at 8.0% and a future P/E of 9.5x.
The cautious Narrative argued for a Fair Value of US$12 and focused on the risk that rapid adoption of digital wallets and new fintech rivals could pressure fees in core US to Latin America corridors.
What The Results Changed For International Money Express
The clearest data point arrived with Q2 2026. International Money Express reported revenue of US$131.162 million and net income of US$4.205 million, compared with US$161.133 million and US$11.007 million in Q2 2025, while net margin moved from 6.8% to 3.2%. That shift challenged the optimistic case that assumed steady 8.0% profitability.
The lesson to take elsewhere is simple. When a thesis leans on stable or rising profitability, track the reported net margin every quarter and test it against the forecast path, not just the headline revenue line.
What You Are Paying For In International Money Express Today
International Money Express now trades at US$10.3, with the selected Narrative suggesting a Fair Value figure above that level rather than below it. That view leans heavily on the idea that digital remittances and the Western Union transaction could reshape the earnings mix.
The key assumption a buyer must weigh is that regulators eventually clear the Western Union deal and that digital volumes grow enough for higher margin channels to matter more than current fee pressure.
"International Money Express is still focused on accelerating its digital growth efforts in core corridors. This keeps the potential for higher digital mix and improved unit economics alive and can support revenue growth and operating margins as digital volumes scale."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 33% below our estimate - turns subsea project leads into higher margin equipment and recurring service work.
- Company 2 - 32% below our estimate - sells GPUs and tightly integrated software stacks for AI-focused data centre builds.
- Company 3 - 42% below our estimate - advises on complex product failures as regulation and AI risks increase scrutiny.
Three companies from the same screener. Open the full list of 25 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com