


SSP Group (LSE:SSPG) Faces A Valuation Test Following Softer Profit Guidance
SSP Group (LSE:SSPG) has drawn fresh attention after its 9 October trading update flagged slightly lower than planned operating profit of about £230m, linked to subdued North American passenger numbers.
The share price reaction reflects that tension. SSP Group’s 1-day share price return of 1.39% and 7-day return of 1.16% follow a year to date share price decline of 11.2%. At the same time, the 1-year total shareholder return of 17.58% points to earlier optimism now facing a test as guidance tightens and execution risks around Continental European rail reshape how investors think about the risk and reward balance.
Compare how SSP Group’s risk and reward trade off against travel peers by scanning our hand picked 4 resilient stocks with low risk scores that have held up better under recent pressure.
Bulls point to SSP Group’s guided EPS of about 14p and a 1 year total return of 17.58%. Bears focus on weaker profit guidance and execution risk. Which case does today’s valuation really lean toward?
Most Popular Narrative: 7% Overvalued
SSP Group’s most followed narrative anchors fair value at about £1.70 per share, compared with the last close of £1.82. As a result, the focus shifts to whether execution and cash delivery justify paying above that mark.
The planned reshaping of Continental European rail, including exiting around one third of units and halving capex in that channel, rests on future passenger volumes and contract economics that are not yet secured. If traffic and concession terms fail to improve enough, the lower capital base could still produce margins and returns that fall short of current expectations.
See why 1 investors see SSP Group as 7% overvalued.
Result: Fair Value of £1.70 (OVERVALUED)
Still, if SSP Group’s cash focused model delivers more than £100m of free cash flow and Continental Europe shifts toward 5% margins, this bearish narrative could weaken.
Find out about the key risks to this SSP Group narrative.
Another View: SSP Group Through Sales Multiples
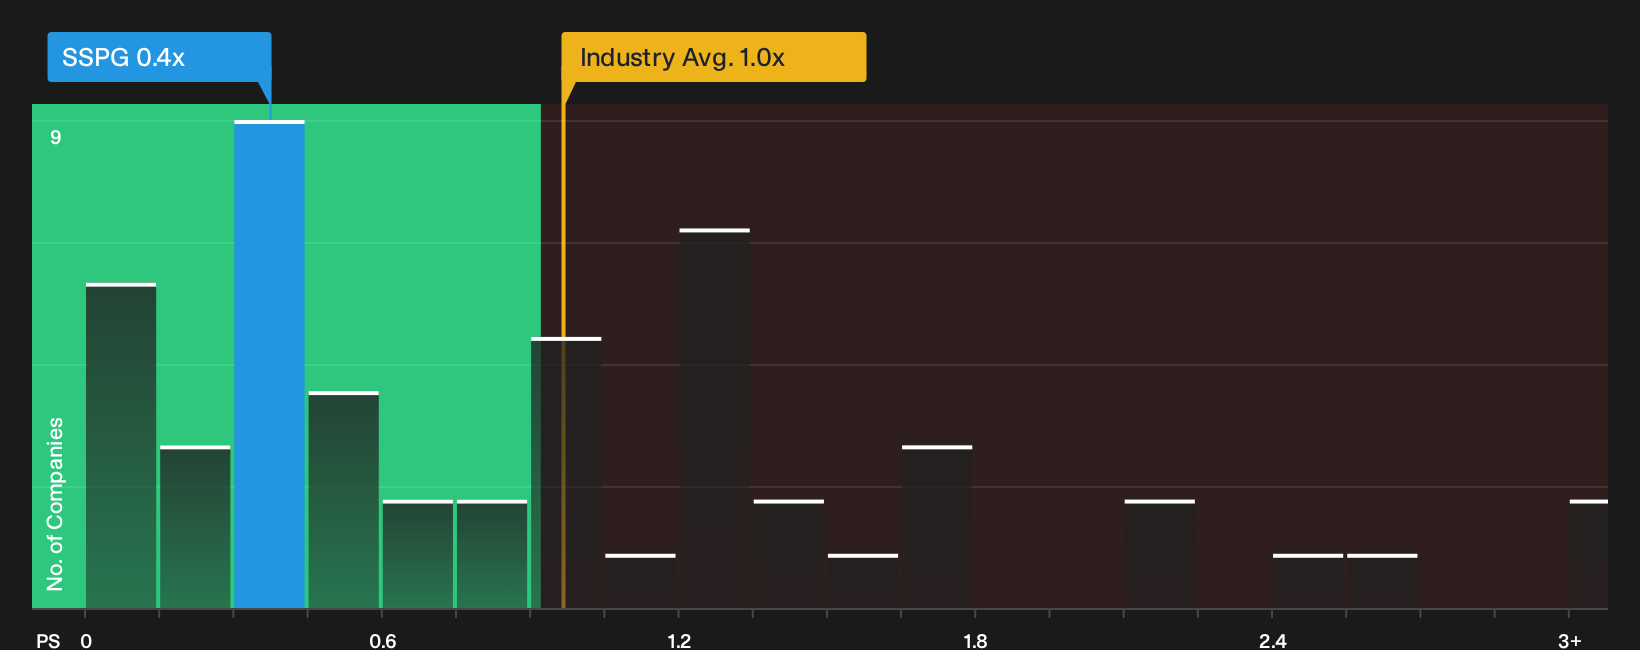
The narrative fair value of £1.70 points to SSP Group looking 7% overvalued, yet its valuation on sales tells a different story. The shares trade on a P/S of 0.4x compared with a fair ratio of 0.9x, the UK Hospitality average of 1.0x and a peer mark of 0.9x. That discount suggests the bigger pricing risk might be underestimating what even modest revenue progress could be worth to shareholders.
To test whether this gap reflects genuine concerns or potential mispricing, review how current pricing stacks up in our valuation breakdown, then judge which story feels closer to your own expectations for SSP Group. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SSP Group’s outlook can be useful for you, not a problem. You can weigh the potential benefits against the concerns by reviewing the 2 key rewards and 1 important warning sign
Looking for more SSP Group style investment ideas?
If SSP Group has sharpened your thinking, use that momentum and spend a few focused minutes with curated stock ideas that could reshape your watchlist.
- Target value first and scan companies that combine quality fundamentals with pricing that still looks reasonable through the 7 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with balance sheets that can better absorb shocks using the list of solid balance sheet and fundamentals (9 results).
- Hunt for overlooked opportunities and see which under followed stocks clear high quality hurdles inside the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com