


Independent Bank (INDB) Stock Jumps After Record Q3 Earnings
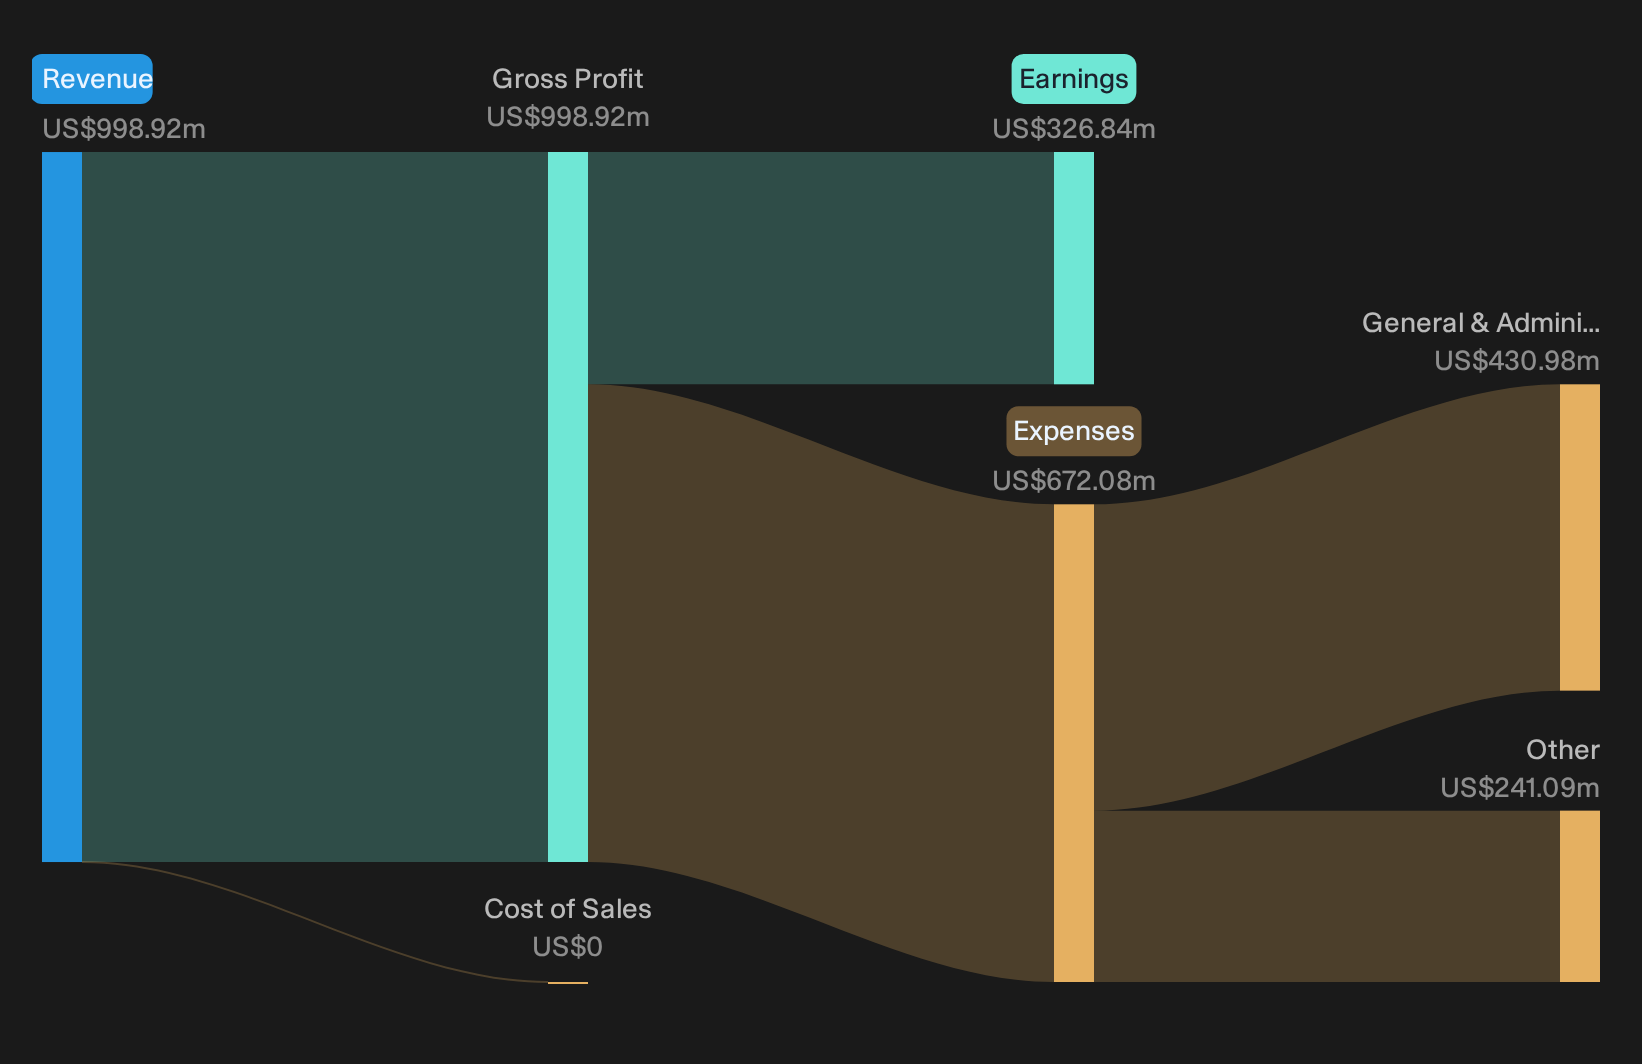
Independent Bank walked into its Q3 2026 report with a mixed tape behind it. The share price was down over the past month and quarter, yet up modestly across the past week. Then the earnings hit. The stock jumped 3.6% on the day while the company reported record quarterly net income of US$89.7 million and basic earnings per share of US$1.90.
That kind of one day pop looks emotional at first glance. The bigger story is a bank reporting solid profitability while the market has been lukewarm on the stock for months.
Like the idea of Independent Bank putting up record earnings while the share price drifts, but want a wider set of profitable financials that the market has not fully embraced? Check out the 33 high quality undervalued stocks
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$255.45m vs. US$205.22m (up about 24%)
- Net Income (Excl. Extra Items) (Q3 2026 vs. Q3 2025): US$89.75m vs. US$34.26m (up about 162%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.90 vs. US$0.69 (up about 177%)
- Net Interest Margin (Q3 2026 vs. Q3 2025): 3.89% vs. 3.62% (higher quarterly margin)
Ask Charlie what Independent Bank’s 100% payout target really means.
Independent Bank’s Bull Story Meets Q3 Reality
Independent Bank’s optimism around a cleaner business mix hinges on lending, deposits and technology all pulling in the same direction.
"Analysts expect Independent Bank to keep rebalancing toward relationship-based C&I lending, low-cost core deposits, and scalable technology."
Q3 loan growth was modest in total, yet C&I rose about 5% annualized excluding dealer runoff, which supports that pivot. Non-time deposits grew and funding costs of 1.42% still sit well below the reported net interest margin of 3.89%. The core conversion was pushed to February 2027, so the technology payoff is delayed and conversion expense guidance has risen.
CRE, Conversion Risks For Independent Bank
The bear narrative focuses on commercial real estate and execution risk, so the question is whether Q3 shows cracks or containment.
"The earlier concern about Independent Bank's high commercial real estate concentration remains live because office exposure is still being worked through, with several criticized and classified office loans including a US$17.4 million life science office property that carries a full reserve and another office credit of about US$14 million being brokered for sale."
Nonperforming office balances of about US$60 million now sit inside a broader NPA ratio of 0.5% of assets and net charge-offs were 2 basis points. Provision expense rose to US$6.5 million, which shows the risk is active but so far absorbed within record quarterly earnings and a 15.4% ROTCE.
The price and this Narrative do not agree. → Uncover what this Narrative says Independent Bank is actually worth.
Hunt For Quiet Mispricings
Independent Bank reminded investors that share prices may react differently from quarterly earnings results. The real opportunity could be identifying stocks where fundamental trends improve before wider market pricing reflects them.
- Company 1 - 48% below our estimate - tightens project execution on a large infrastructure backlog while higher labor and technology spending challenges margin resilience.
- Company 2 - 35% below our estimate - shifts a growing super-app customer base toward secured credit products while managing funding, risk costs and operating expenses carefully.
- Company 3 - 33% below our estimate - expands from standalone hardware into modular data center building-block solutions so large AI buyers can standardize complex infrastructure with one supplier.
That is three of the list. See all 33 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com