


Westamerica Bancorporation (WABC) Q3 Earnings Show Quiet Strength Behind The Stock
Westamerica Bancorporation has a reputation as a quietly efficient community bank, yet Q3 2026 earnings told a more forceful story than the mild 0.8% share price move to $61.39 suggests. The quarter landed with basic earnings per share of about $1.22 on revenue of roughly $64.1 million, both solid outputs for a lender of this size. What really stands out is the consistency in profitability, with net income of about $28.2 million again underscoring a business that keeps turning deposits into earnings while the market reaction stayed relatively muted.
Appreciate Westamerica Bancorporation’s steady earnings engine but want a few more options with similar consistency on your radar? Scan a curated list built around strong fundamentals and cleaner balance sheets in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$64.05 million vs. US$63.74 million (roughly flat top line with a slight uplift)
- Net Income (Q3 2026 vs. Q3 2025): US$28.15 million vs. US$28.26 million (broadly stable profitability in dollar terms)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.22 vs. US$1.12 (around 9% improvement in earnings per share)
- Non Performing Loans, NPL ratio proxy, (Q3 2026 vs. Q3 2025): US$0.81 million vs. US$2.64 million (material reduction in problem loan balances)
Earnings only tell part of the Westamerica Bancorporation story, because accounting profit can look steady while the actual cash coming in and out of the business paints a different picture for valuation focused investors. When you focus on Westamerica Bancorporation's cash flows instead of just the income statement, the stock could be a dramatic 44% undervalued.
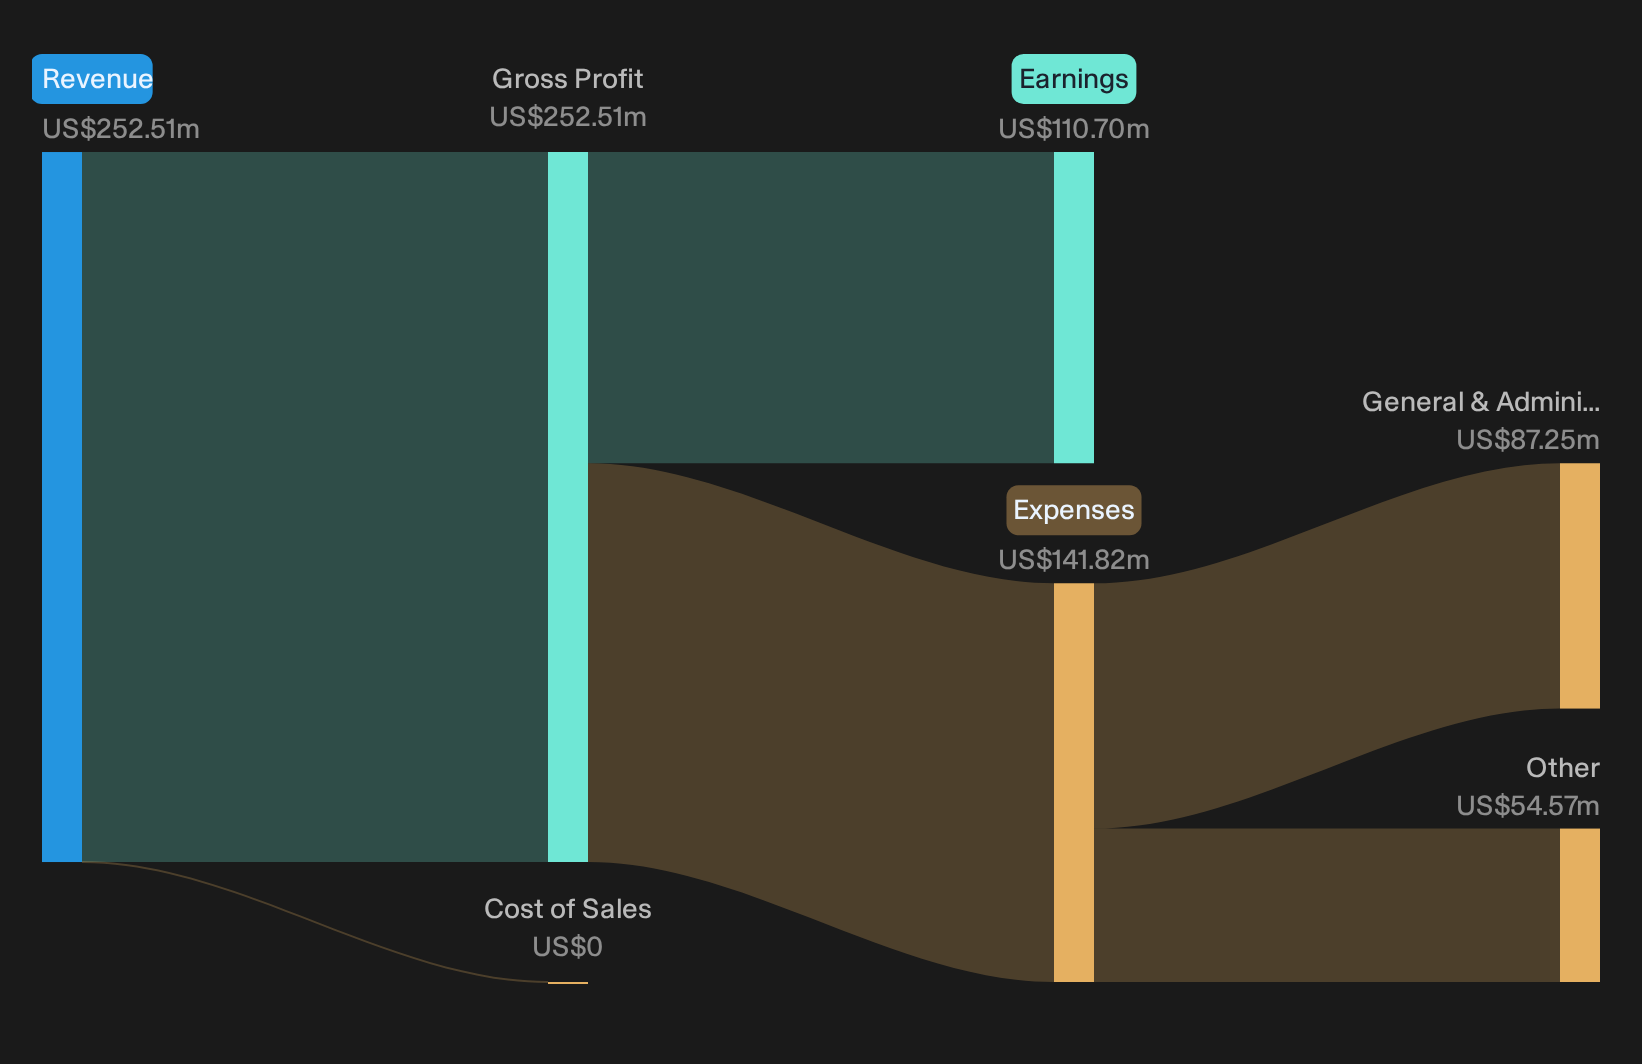
Westamerica bullish story still leans on consistency
Westamerica Bancorporation’s appeal as a conservative relationship bank still rests on steady output rather than rapid change. Revenue is roughly flat year on year, while basic EPS moved from US$1.12 to US$1.22, which points to earnings per share efficiency holding up. Non performing loans fell from US$2.64 million to US$0.81 million, echoing the conservative risk profile described by management in the July 2026 dividend announcement. A modest 0.8% share price move after the release suggests the market already viewed this earnings stream as reliable rather than surprising.
Bearish credit fears look less urgent this quarter
Credit risk is where the cautious narrative around Westamerica Bancorporation gets tested. Concern about commercial real estate and consumer exposure is common for regional lenders; yet the drop in non performing loans points in the opposite direction for now. Net income is broadly stable at about US$28.2 million, and the bank continued its US$0.48 quarterly dividend in August, which implies no immediate stress signal from the board. Recent returns near flat over 90 days show skepticism still exists, but the latest quarter does not intensify it.
Reveal where the surface looks calm but analyst models start to diverge on Westamerica Bancorporation’s timeline. Access the multi year revenue, EPS and dividend analyst estimates for Westamerica BancorporationHunt Quiet Gaps In Expectations
Westamerica Bancorporation just reported a steady quarter and its share price barely moved. The real opportunity sits in finding stocks that could be undervalued before the market closes the gap.
- Company 1 - 36% below our estimate - uses a broader advisory platform and a strong deal pipeline to pursue larger fee rich transactions.
- Company 2 - 49% below our estimate - builds digital tools that draw small businesses into primary banking relationships as loan demand and deposits grow.
- Company 3 - 45% below our estimate - converts a strong backlog of data center and modular projects into higher utilization across newly expanded capacity.
Three companies from the same screener. Open every one of the 32 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com