


Top 3 Founder Led Stocks To Watch In October 2026
When the Federal Reserve hints at holding interest rates steady, as it did in Fed Chair Kevin Warsh's recent comments, investors start hunting for business models that can carry their own weight without cheap money. Founder led companies often fit that brief. Their leaders usually have more on the line than a bonus. This article walks through three such stocks from our screener that show how that mindset can matter.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is deeply invested in long term performance. However, if you want the absolute best, these 29 top founder-led companies are the cream of the crop.
newcleo (NWCL)
Overview: newcleo develops modular lead cooled fast reactors and MOX nuclear fuel from reprocessed materials, led directly by founder CEO Riccardo Procuranti.
Operations: The business currently reports about €44 million in Electric Equipment revenue, mainly across Italy, France, and Switzerland.
Market Cap: €1.92b
Founder-led investors are watching newcleo because Procuranti is tying his own reputation to high risk, capital intensive nuclear technology that aims to close the fuel cycle using MOX from reprocessed materials. The business is still early, loss making, and heavily funded from outside capital, so long term returns depend on how one unresolved regulatory and commercialization hurdle plays out.
That hinge point makes the 3 warning signs (2 are major!) essential reading for understanding where this high stakes bet could crack or suddenly accelerate.

Sweetgreen (SG)
Overview: Sweetgreen runs a founder-influenced fast-casual chain of healthy restaurants in the US, built around branded stores and a digital ordering platform.
Operations: Sweetgreen generates about US$682 million in revenue from company-owned restaurants in the United States that sell food and beverages.
Market Cap: US$1.26b
Sweetgreen matters for this founder-led screen because the restaurant concept, brand and digital ecosystem all trace directly back to the original co-founders, and current management is still working from that playbook as the chain matures.
"Although Sweetgreen is leaning on large menu platforms like wraps and lower entry price points to lift transactions, the recent 6.2% decline in comparable restaurant sales with a 4.2% negative mix and no price increase highlights the risk that value architecture simply trades down the check instead of rebuilding revenue and earnings."
For investors focused on founder legacies, a lot now turns on how one unresolved pressure on Sweetgreen’s unit economics ultimately plays out.
That pressure on Sweetgreen’s unit economics is exactly what the full narrative for Sweetgreen unpacks, showing where value architecture might be masking a stronger long term setup.

Lincoln International (LCLN)
Overview: Lincoln International is an independent advisory firm that helps founders and private funds structure capital raises, liquidity solutions, and valuations worldwide.
Operations: Lincoln International generates about US$697 million from Investment Banking Advisory and US$188 million from Valuations and Opinions, mainly across the Americas and Europe.
Market Cap: US$2.49b
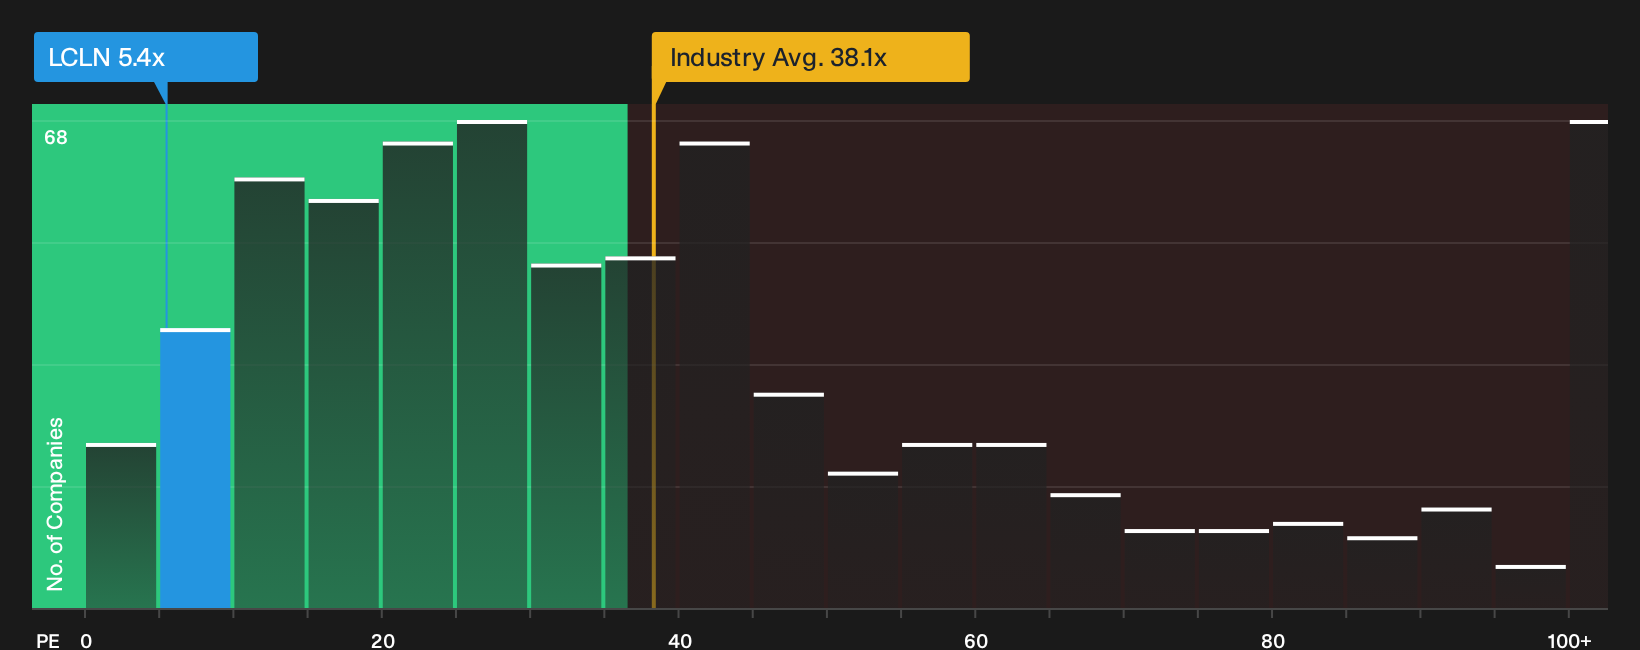
Lincoln International provides focused access to founder-oriented advisory work, ranging from growth equity to continuation vehicles. The shares currently trade on a 5.4x P/E, which highlights both the level of risk and the possibility of mispricing in a business closely tied to founder liquidity needs. The outlook now depends on how one unresolved pressure on earnings and margins ultimately develops.
That earnings pressure is exactly why the 2 key rewards and 2 important warning signs (1 is major!) could be worth a look if you think Lincoln International’s low P/E might be masking something bigger.
Seeking Fresh Alternatives Before They Fly
Market momentum shifts fast and the next breakout list will not stay under the radar for long. Scan fresh ideas before the crowd catches them and act now.
- Target dependable cash flows by scanning a curated 7 dividend fortresses that focuses on income strength while it still aligns with today’s yields.
- Consider the AI infrastructure buildout by using the hand picked 55 AI infrastructure stocks that ties directly into data center and compute demand.
- Track developments in the energy transition with a focused 16 nuclear energy infrastructure stocks that highlights potential long dated nuclear buildout beneficiaries.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com