


Biogen (BIIB) On Lupus Trial Results Looks Fully Valued Or Still Worth Buying
Biogen (BIIB) shares are in focus after the company released 52-week Phase 2 results from its AMETHYST trial of litifilimab in cutaneous lupus erythematosus, highlighting sustained skin disease activity improvements.
For context, Biogen shares trade at US$232.65, with a 30.83% year to date share price return and a 62.69% one year total shareholder return. The 12.94% 3 month share price gain hints that positive momentum around recent drug updates is still building.
Scan other potential biotech movers on the back of fresh trial data by comparing Biogen with a curated set of 34 healthcare AI stocks in one place.
Biogen’s sharp run on litifilimab leaves you weighing it up. Does it make more sense to accept today’s price after this move, or to wait and hope for a cheaper entry before the next data or decision hits the tape?
Most Popular Narrative: 5% Undervalued
Biogen’s most followed valuation narrative pegs fair value at about $243.98, only modestly above the last close at $232.65. This puts the recent litifilimab move into the context of a stock already priced for solid execution rather than a deep discount.
Growing uptake of Biogen’s multi-product growth portfolio, which generated over US$1b of revenue in Q2 2026 and has now exceeded the multiple sclerosis portfolio, supports the idea that a broader base of neurology and immunology brands can increasingly carry total revenue and help stabilise earnings.
See why 62 investors see Biogen as 5% undervalued.
Result: Fair Value of $243.98 (UNDERVALUED)
Still, Biogen’s story can wobble if multiple sclerosis revenue erosion accelerates, or if key launches like LEQEMBI and SKYCLARYS fall short of analyst adoption hopes.
Find out about the key risks to this Biogen narrative.
Another View: Biogen Through The P/E Lens
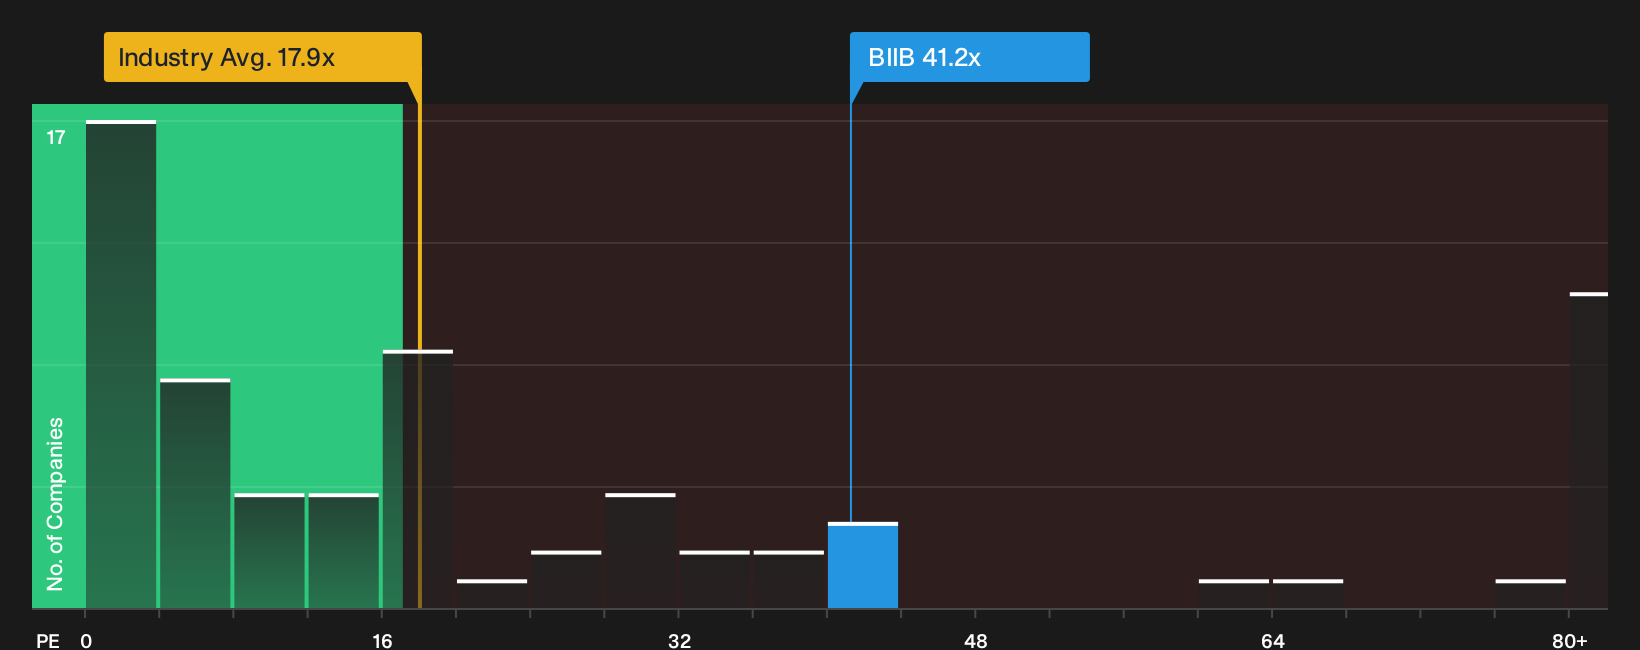
Biogen might look cheap on some models, but its current P/E of 41.2x tells a different story. That rating sits well above the US Biotechs industry at 17.9x and a peer average of 22.5x, and it also exceeds the 30.4x fair ratio that the market could move toward. For you as a shareholder, that kind of gap points to real valuation risk if sentiment shifts away from premium multiples. How much of your thesis rests on the P/E staying this elevated?
See what the numbers say about this price in the fuller context of Biogen’s valuation breakdown by checking the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Biogen’s momentum and the valuation questions raised here is normal. Move quickly, scrutinise the data, and weigh both the upside and the red flags by checking the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Biogen?
Do not stop at Biogen. Give yourself options by lining up fresh watchlist candidates that match the kind of risk and return profile you actually want.
- Target potential mispricing by scanning a curated pool of companies that currently screen as 33 high quality undervalued stocks.
- Lock in income-focused ideas by zeroing in on companies that qualify as 7 dividend fortresses.
- Dial down downside risk by filtering for businesses that pass the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com