


How Half Year Earnings Growth At San A (TSE:2659) Has Changed Its Investment Story
- SAN-A CO.,LTD. reported half-year results to August 31, 2026, with sales of ¥119,330 million and net income of ¥6,414 million, and basic EPS from continuing operations of ¥105.44.
- The wider gap between sales and net income compared with the prior year indicates that SAN-ALTD’s cost control and operating mix are becoming more supportive for earnings quality.
- The focus now is on how SAN-ALTD’s higher basic EPS from continuing operations reshapes the investment narrative, and what that means for long-term holders.
Compare SAN-A CO.,LTD.'s latest earnings momentum with a curated group of retailers and consumer names that also pair revenue scale with solid profitability through our 73 high quality undiscovered gems
What Is SAN-ALTD's Investment Narrative?
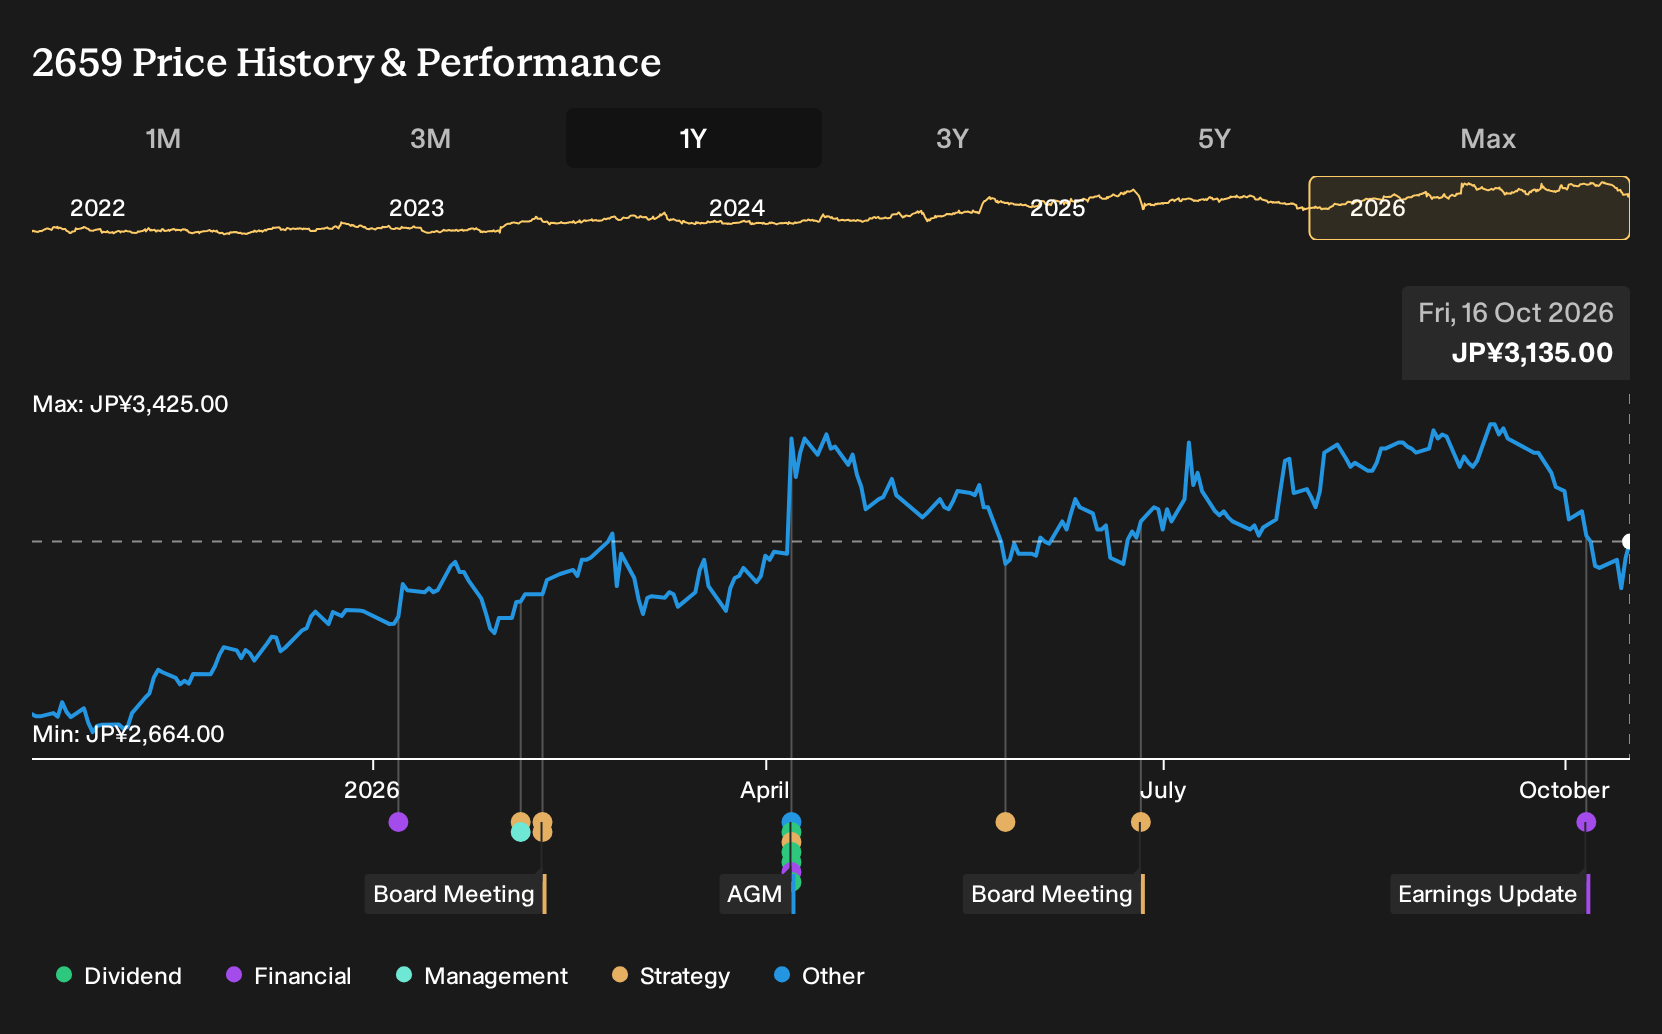
To own SAN-ALTD, you need to believe that a regional supermarket chain in Okinawa can keep translating steady shopper demand into consistent, if unspectacular, earnings. The latest half year numbers to August 31, 2026 sit in that camp. Sales reached ¥119,330 million and net income was ¥6,414 million, with basic EPS from continuing operations of ¥105.44. That supports the idea of a resilient everyday retail model where execution, store productivity and cost control matter more than headline growth stories.
The short term debate now focuses on how durable that earnings quality really is. Forecasts point to revenue growth of 3.3% per year and an average 0.8% annual decline in earnings, which keeps attention on pricing power, wage costs and any need for heavier investment in stores or logistics. A dividend yield of 3.51% that is not well covered by free cash flows also adds a capital allocation question, especially with a P/E of 16.6x above both the Consumer Retailing industry and peer averages. The fresh earnings print feeds into all of these moving parts rather than resetting them.
Even so, there is a quieter pressure point in SAN-ALTD's story that only really shows up once you start digging into ...
There's only one way to know the right time to buy, sell or hold SAN-ALTD. Head to Simply Wall St's company report for the latest analysis of SAN-ALTD's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SAN-ALTD research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SAN-ALTD. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SAN-ALTD's overall financial health at a glance.
Looking For More Investment Ideas Beyond SAN-A CO.,LTD.?
If you want to test your thesis on SAN-ALTD against other opportunities, it helps to scan a wider field of companies that match different risk and income profiles. The Simply Wall St Screener can surface very different types of stocks, so you can compare what you own with what you might be missing.
- For investors who care most about valuation support and fundamentals, it can be useful to review a curated set of companies trading on what looks like attractive metrics through the 14 high quality undervalued stocks.
- If reliable payouts matter to you, consider cross checking SAN-ALTD's yield and payout profile against a focused group of income ideas using the 29 dividend fortresses.
- Readers who prefer capital preservation and smoother rides may want to concentrate on businesses with stronger risk profiles. This is where the 22 resilient stocks with low risk scores can help narrow the field.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com