


Belite Bio (BLTE) Could Be 36% Undervalued On Tinlarebant Filing Progress
Belite Bio (BLTE) has advanced the development of tinlarebant by filing Marketing Authorization Applications in Singapore, the United Kingdom, and Switzerland, targeting Stargardt disease type 1, for which there are currently no approved therapies.
Recent moves in Belite Bio’s share price have been choppy, with the stock down 6.45% on a 1-day basis, 7.58% over 7 days and 15.62% over 30 days. At the same time, the 1-year total shareholder return of 62.79% and 3-year total shareholder return of about 4x highlight how strong longer term sentiment has been, even as investors reassess risk and timing around tinlarebant’s regulatory path and the latest Marketing Authorization Applications.
See how Belite Bio fits into the wider hunt for rare disease opportunities by comparing it with our curated list of 20 high quality undiscovered gems.
Belite Bio has surged over three years yet pulled back sharply in recent weeks as tinlarebant edges through regulators. Does that recent slide offer a reasonable entry now, or does patience on the sidelines make more sense?
Most Popular Narrative: 36% Undervalued
Compared with Belite Bio's most followed fair value estimate of about $223.89, the last close of $142.78 implies a wide valuation gap that hinges heavily on tinlarebant's path through regulators and eventual commercialization.
Potential first approval of Tinlarebant in Stargardt disease, supported by Phase III DRAGON data showing a 36% reduction in lesion growth, could introduce an initial revenue stream in an area with no existing pharmacologic treatment and begin to shift the company from pure R&D spend toward commercialization driven earnings.
See why 3 investors see Belite Bio as 36% undervalued.
Result: Fair Value of $223.89 (UNDERVALUED)
Still, the Belite Bio story leans heavily on pending FDA and EMA decisions, and any delay or a narrower label for tinlarebant could affect that 36% undervaluation narrative.
Find out about the key risks to this Belite Bio narrative.
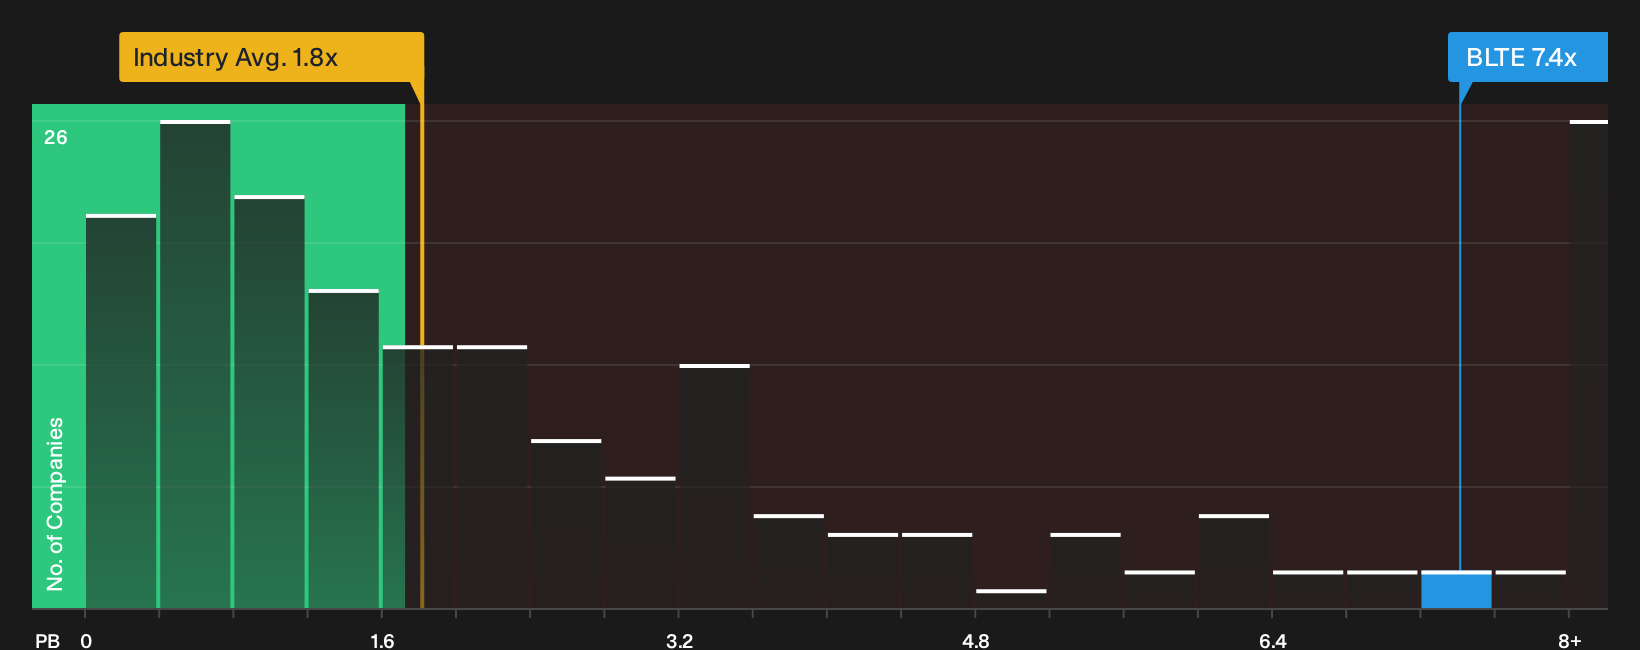
Another View: What Belite Bio’s P/B Ratio Is Telling You
That 36% discount to fair value looks appealing on paper. Yet on a simple P/B lens, Belite Bio trades at about 7.9x book value against roughly 1.8x for the wider US Pharmaceuticals group and about 55x for its closest high growth peers. This points to a rich valuation relative to assets even if it screens cheap versus fast growing comparables. The question for anyone considering the stock is whether that premium to the sector fairly reflects the regulatory and execution risk still ahead.
For a closer look at how this price compares with fundamentals, and how that gap could change as the story evolves, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Belite Bio is split between excitement over tinlarebant’s potential and concern about what could go wrong on the way to market. You can weigh those cross currents quickly using the detailed breakdown of 2 key rewards and 2 important warning signs.
Looking for more Belite Bio sized opportunities?
If you stop with Belite Bio, you miss the wider field of stocks screened for strong balance sheets, resilient dividends, and mispriced potential across the market.
- Target robust cash generation and lower financial stress by scanning companies filtered through our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality where fundamentals and valuation line up using the curated ideas inside 33 high quality undervalued stocks.
- Build reliable income streams by zeroing in on companies flagged as 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com