


Akamai Technologies (AKAM) Cloud Wins Raise The Question Of Whether Shares Are A Bargain
Akamai Technologies (AKAM) is back in focus after reporting fresh customer wins for its cloud computing services, as enterprises look for high-performance CPU and GPU infrastructure alongside resilient storage and disaster recovery.
The recent cloud customer wins arrive after a sharp pullback in Akamai Technologies’ share price. The stock fell around 17.9% over the past week and 26.9% over the last three months, while still showing a 3.2% year-to-date share price gain and a 20.5% total shareholder return over the past year. This pattern hints at fading short-term momentum, while the longer record remains more supportive.
Scan how Akamai Technologies compares with other AI and cloud infrastructure plays by running through our hand-picked 55 AI infrastructure stocks in the same space.
Bulls point to Akamai Technologies’ recent cloud wins and the stock’s pullback as a potential opportunity. Bears see a value trap in shares with mixed multi year returns. Which case does the current valuation appear to support?
Most Popular Narrative: 45% Undervalued
The most widely followed narrative pegs Akamai Technologies at a fair value of $158.87, well above the last close at $87.81. This places the recent share slide against a much higher long run value marker.
Active capital deployment toward cloud infrastructure growth, including an expected 2026 CapEx level of about 40% of revenue and roughly US$5.5b of planned Anthropic related CapEx supported by zero coupon convertible debt financing and new power sourcing arrangements, is intended to build a 95 to 105 megawatt AI infrastructure portfolio. Management expects this portfolio to deliver about US$22m in annual revenue per megawatt and support future cash gross margins in the mid 60s to mid 70s range.
See why 35 investors see Akamai Technologies as 45% undervalued.
Result: Fair Value of $158.87 (UNDERVALUED)
Still, the bullish case around Akamai Technologies depends on CIS contracts ramping as planned and heavy AI related CapEx earning the margins that management is targeting.
Find out about the key risks to this Akamai Technologies narrative.
Another View: What Multiples Say About Akamai Technologies
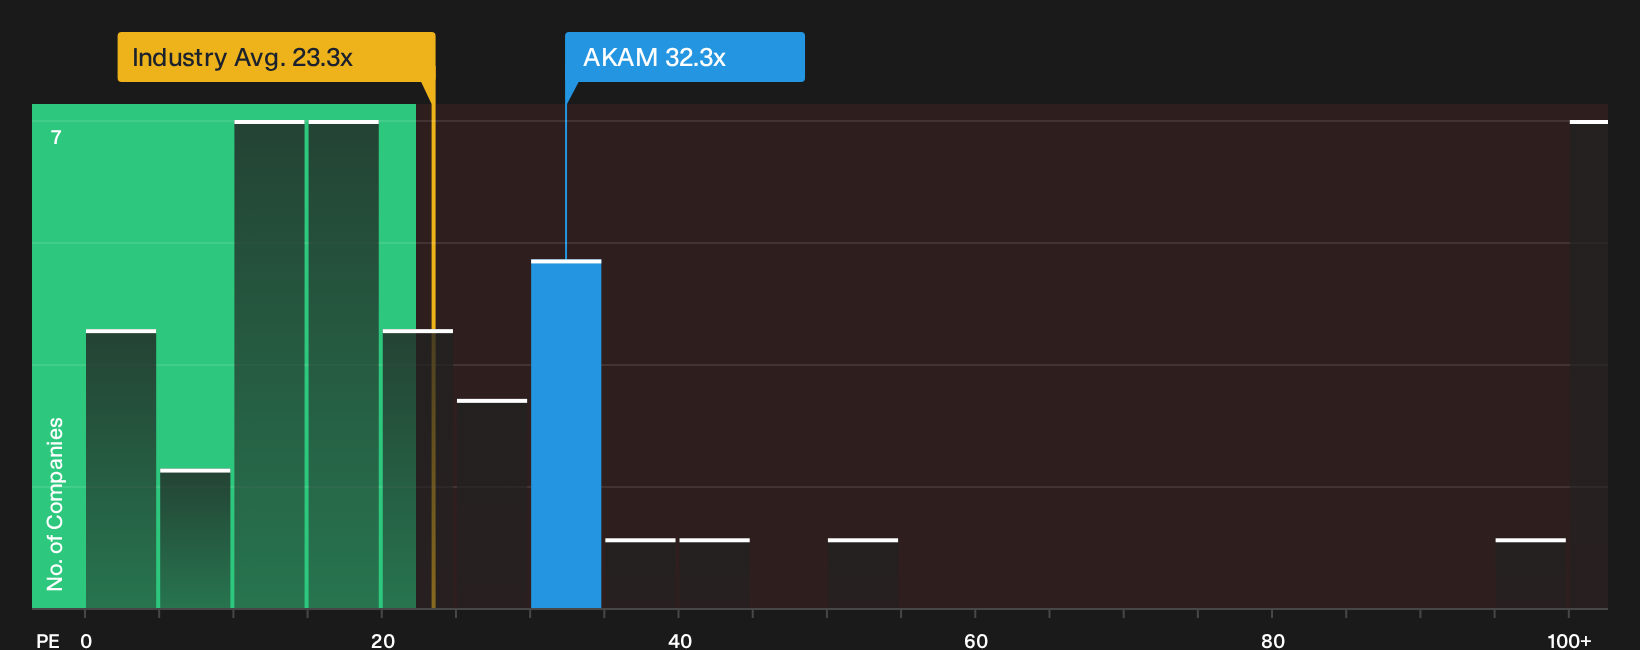
The SWS DCF model points to undervaluation, yet the P/E picture is far less forgiving. Akamai Technologies trades on 32.3x earnings, richer than the US IT sector at 23.3x and above peer averages at 27.8x, while only slightly below an estimated fair ratio of 35.8x. Is the discount to fair value enough to justify paying a premium multiple?
To see how that richer P/E profile fits with cash flow, margins, and future scenarios, take a closer look at our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Akamai Technologies is split, with clear risks on one side and appealing rewards on the other. Consider moving quickly and stress test the numbers yourself by checking the 2 key rewards and 1 important warning sign.
Looking for more Akamai Technologies sized opportunities?
If you only stop at Akamai Technologies, you might miss ideas that better fit your goals, risk limits, or income needs across the rest of the market.
- Target potential mispricing by scanning a hand picked pool of companies that score well on quality and value through the 33 high quality undervalued stocks.
- Strengthen capital preservation by focusing on businesses with sturdy finances using the list of solid balance sheet and fundamentals (25 results).
- Turn market volatility into a source of income by filtering for higher yielding opportunities with the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com