


How Restaurant Closures Will Impact Wendy's (WEN) Investors
- Wendy's is contesting proposed closures of 41 restaurants tied to bankrupt franchisee Meritage Hospitality Group. An analyst has also flagged expectations of further U.S. store shutdowns over the next 6 to 12 months, reflecting pressure on weaker locations and a breakfast menu that has not met expectations.
- The dispute over more than US$146 million in claimed unpaid royalties and fees from Meritage highlights how franchisee health can affect Wendy's systemwide sales, royalty income, and efforts to improve restaurant economics.
- We will now look at how Wendy's investment narrative is affected by fresh franchise closure risk tied to the Meritage bankruptcy dispute.
Compare how Wendy's challenges stack up against other potential opportunities and scan a curated list of 33 high quality undervalued stocks with stronger momentum behind their core franchises.
Wendy's Investment Narrative Recap
To own Wendy's, you need to believe the franchise model can recover in the U.S. while digital, international, and system optimization efforts gradually support more stable earnings. The Meritage dispute and analyst expectation of more closures put that thesis under pressure in the near term, but the core question is still franchisee economics, not short term legal noise.
The main near term catalyst remains better unit level performance, especially in breakfast and underperforming stores. This ties directly into royalty income and advertising support. The biggest current risk is that further closures and weak traffic deepen the drag on systemwide sales, limiting Wendy's ability to fund marketing and margin improvement projects.
The Meritage Chapter 11 process is the most relevant development for this story. A proposed closure list of 41 Wendy's restaurants and a disputed US$146 million royalty and fee claim underline how stressed operators can weigh on systemwide sales and corporate cash generation. This sits alongside an existing plan to close or sell about 60 sites tied to another major operator.
For you, the key link is between this bankruptcy case and the stated catalysts. Digital upgrades, Project Fresh, and system optimization rely on franchisees having enough cash flow to invest and stay current on obligations. If more operators follow Meritage into restructuring, execution risk around those projects increases, even if the long term turnaround framework on paper still looks intact.
What The Current Forecasts Assume For Wendy's
Wendy's narrative projects US$2.3b in revenue and US$148.4m in earnings by 2029. That profile rests on analysts building in 1.9% yearly revenue growth and an earnings increase of about US$22.3m from current earnings of US$126.1m.
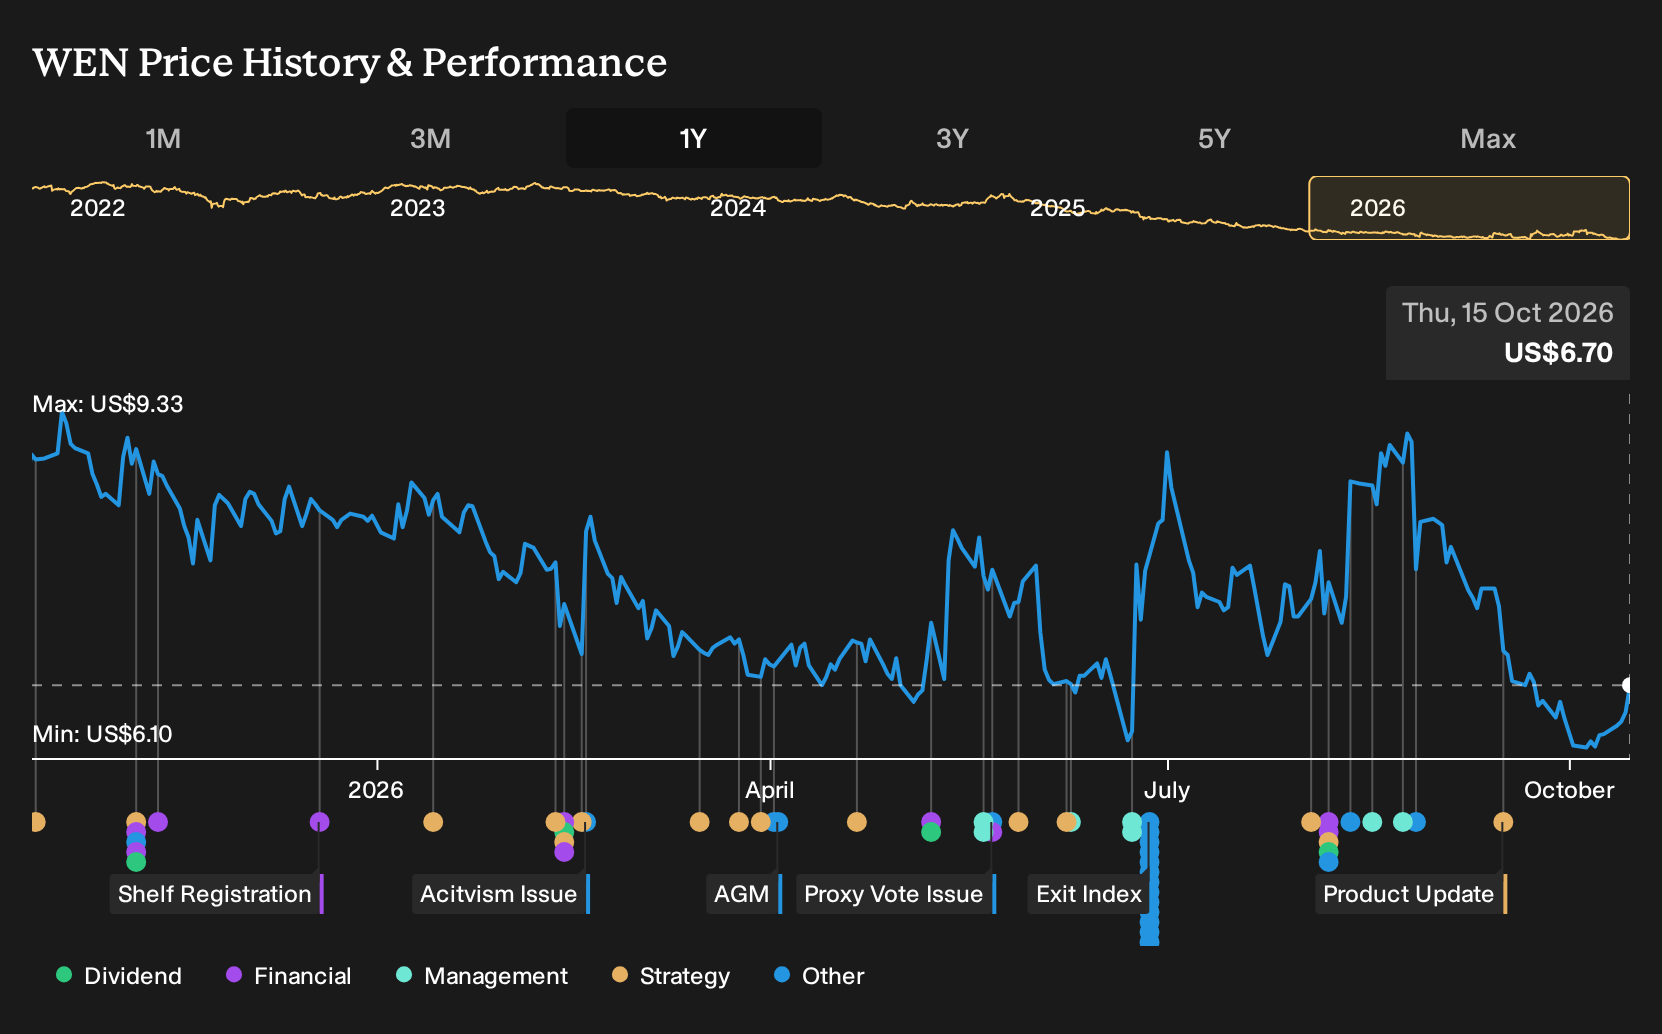
Uncover how Wendy's fair value indicates a 13% potential upside to its current price. This upside could narrow quickly if franchise pressure eases.
Exploring Other Perspectives
Some of the most optimistic analysts frame the China expansion as the real swing factor for Wendy's, not U.S. breakfast or closure noise. Before this Meritage dispute, the bullish camp was pencilling in revenue of about US$2.5b and earnings near US$162.3m by 2029. That is far above the most cautious US$97.7m view, and it shows how widely opinions can differ. Use this news as a prompt to compare those pre news narratives and decide which assumptions seem closer to your own.
Explore 5 other Wendy's fair value estimates, including one that suggests potential upside of up to 92% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wendy's research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Wendy's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wendy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wendy's?
Once you have a view on Wendy's, it helps to line that thesis up against a broader watchlist. Use the Simply Wall St Screener to benchmark this stock against other businesses with different strengths, risk profiles, and income characteristics.
- If you want potential mispricing combined with resilient fundamentals, scan a focused group of 33 high quality undervalued stocks that may offer a different balance of quality and price.
- For investors who care most about durability and balance sheet strength, start with a curated list of solid balance sheet and fundamentals (25 results) that can anchor a more defensive portfolio.
- When you are hunting for promising opportunities that are not yet widely followed, cast the net wider with a targeted set of 20 high quality undiscovered gems that could complement a position in Wendy's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com