


Is Roche Holding (SWX:ROP) Still Reasonable After Its 76% Run?
Roche Holding has delivered a strong share-price run in recent years, which raises a clear question for anyone looking at the stock today. Is the current price tag still grounded in what the group is earning, or has sentiment moved ahead of its underlying profits.
- Roche shares are up 75.9% over the past 3 years, putting a lot of weight on the idea that its earnings can support that kind of rerating.
- The recent US approval for Tecentriq in stage III dMMR colon cancer, along with fresh late stage data for vamikibart in uveitic macular edema and new licensing deals in Parkinson’s and obesity, may support expectations for future profit streams and shape how investors think about the stock's earnings power over time.
- There is a second opinion on Roche Holding worth weighing. See what analysts think Roche Holding's shares could be worth.
The stock's next move may depend on whether Roche's current earnings, and what investors expect them to deliver over time, are enough to justify today's price.
If you want a wider watchlist of healthcare names while you assess Roche Holding's earnings story, a focused stock screen of 128 healthcare AI stocks can help broaden your research.
Is Roche Holding a Bargain on Earnings?
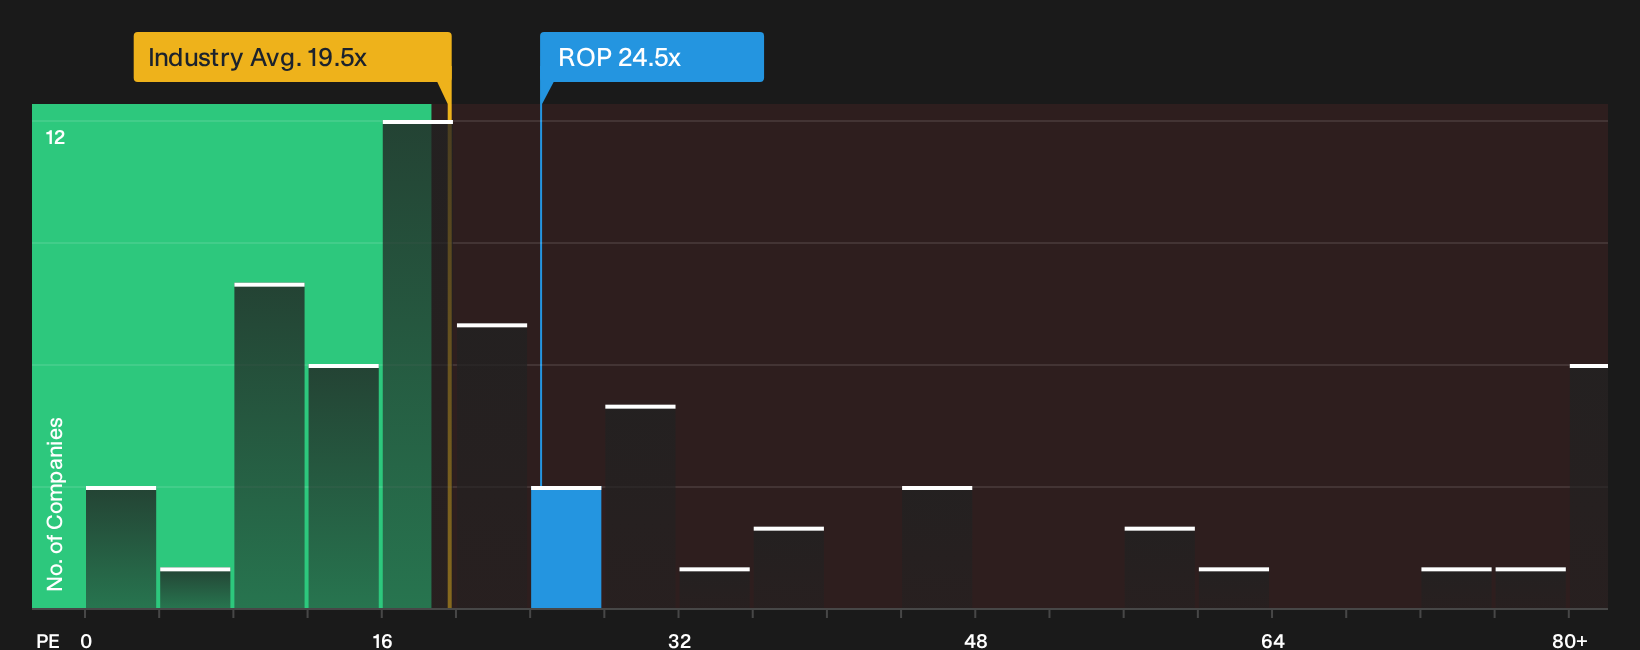
The P/E ratio is a decent starting point for thinking about Roche Holding because earnings still anchor how most shareholders frame the business. Roche currently trades on a P/E of 24.5x, which is above the Pharmaceuticals sector average of 21.6x yet sits well below the peer group on about 44.8x. That mix points to a premium against the wider industry but a discount against the tighter peer set investors often compare it with.
On this framework, the fair multiple that would fit Roche's own profile in terms of margins, size and risk comes out higher than where the shares trade. This suggests that the stock may look undervalued on an earnings basis. Because the recent Tecentriq approval in stage III dMMR colon cancer gives the pipeline more visibility in a specific use case, this kind of P/E discount to peers may appear unusual to anyone who believes that this development significantly strengthens the long term franchise. Explore the numbers behind Roche Holding's P/E valuation.
The Roche Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Roche Holding's valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would be needed for the shares to be worth materially more or less than today. Each one links its number to a clear view on how Roche Holding's growth profile, margins and risk picture might evolve so you can see how that view stacks up as fresh information comes through.
Roche Holding draws two very different readings from the community, with one camp focusing on the late stage pipeline and the other concerned that the market already prices in a lot of good news.
Bull case: 11% undervalued
"A broad wave of late stage pharma assets, including up to 19 medicines that Roche aims to launch by the end of the decade, alongside 10 NMEs recently moved into Phase III, points to a richer mix of higher value products that can support group sales and core EPS over time..."
Discover why this Narrative puts Roche Holding at 11% undervalued.
Bear case: 7% overvalued
"Transition risk due to biosimilar erosion of legacy blockbusters (Avastin, Herceptin, Rituxan)..."
Explore why this Narrative puts Roche Holding at 7% overvalued.
One more angle on Roche Holding that could change your view
Price tags and pipelines only tell part of the story for Roche Holding, because our broader checks have also highlighted areas of concern that deserve your attention before you form a firm opinion. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com