


Missed ABN AMRO Bank's Run? What Holders Had To Believe
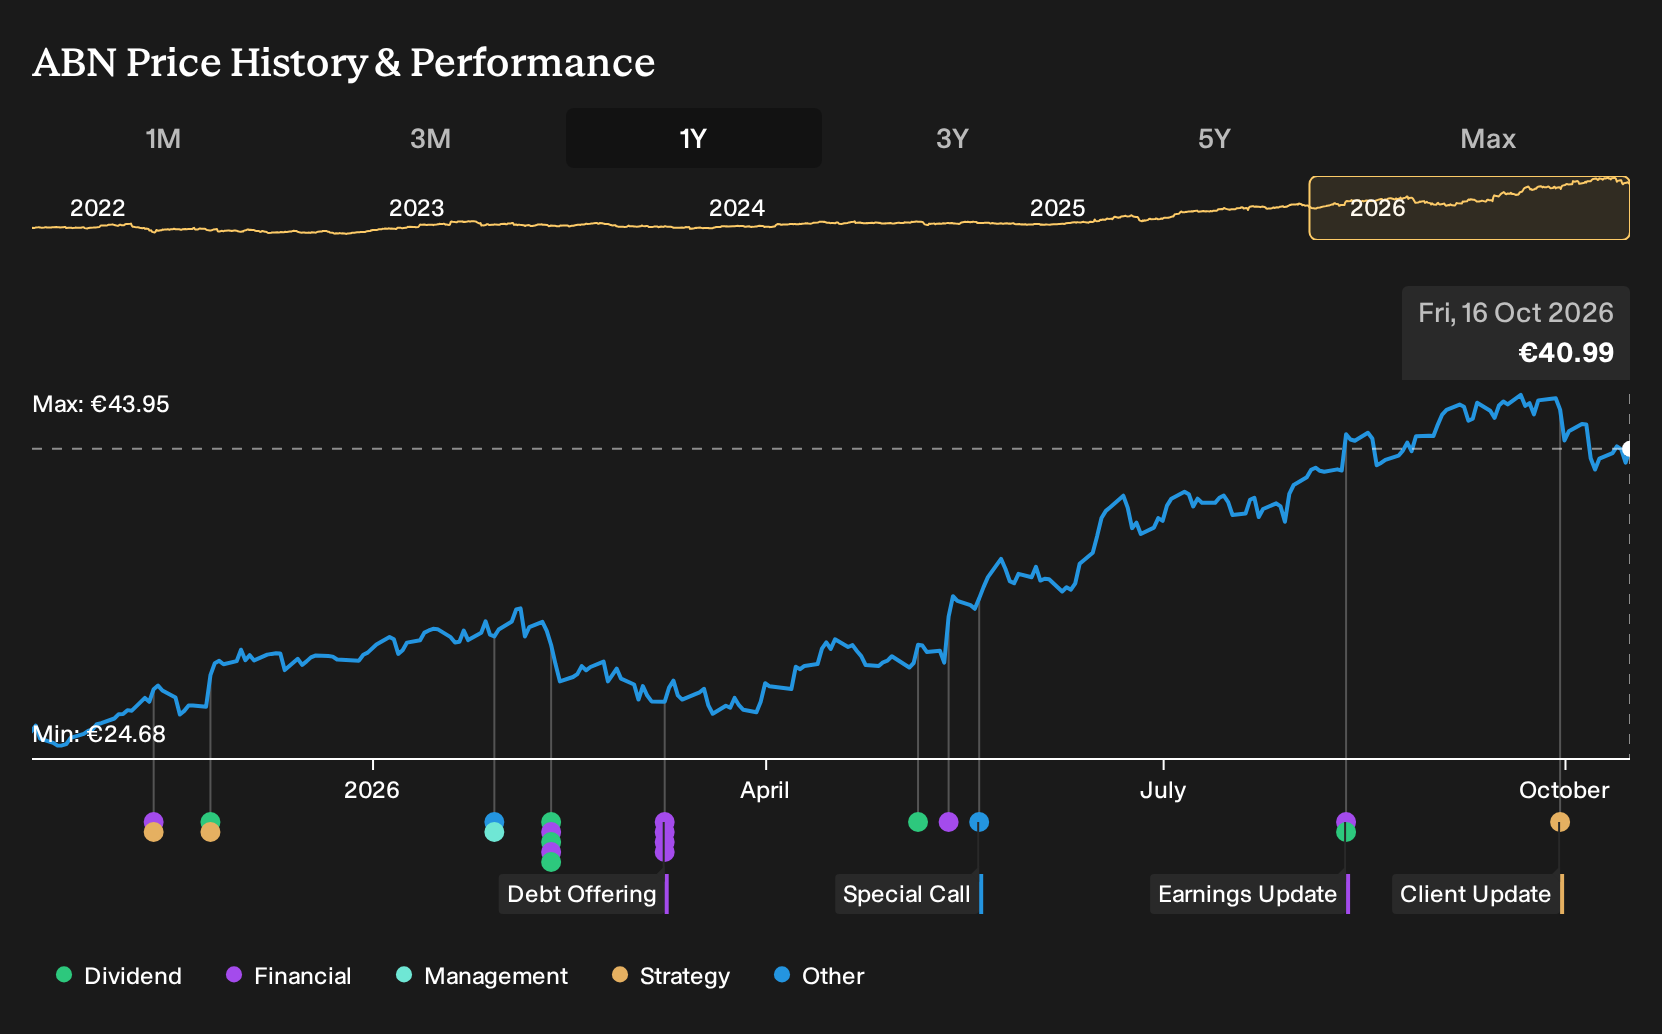
If you had focused only on headlines about ABN AMRO Bank joining euro stablecoin pilots and rolling out BUUT Pay for under‑16s, this past year might look like a straightforward digital success story. For ABN AMRO Bank shareholders, the return over the past year was 72.1%, including dividends. If you were weighing a purchase back on 16 October 2025, what exactly did you need to believe about those early fintech and ESG moves to hold through everything that followed?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind ABN AMRO Bank. Zero in on 193 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On ABN AMRO Bank
The shares cost €25.78 at the start of the period. Anyone looking at ABN AMRO Bank then had to choose between two very different but reasonable stories about where this bank might go next.
On the bullish side, the Fair Value sat at €29, or 12% above the start price, assuming deposit growth, cost discipline and digital projects like BUUT and automation would support earnings and margin improvement.
The bearish view put Fair Value at €17.3, or 33% below the start price, warning that fintech competition, tighter ESG demands and heavy Dutch housing exposure could compress net margins and cap profitability.
What The Results Changed For The ABN AMRO Bank Story
ABN AMRO Bank closing the €875 million NIBC deal and reporting Q2 2026 net income of €781 million on €2,400 million of revenue, with net margin rising to 32.5%, leaned toward the bullish case that argued cost control and digital projects could support higher profitability. The €8.5 million AML fine and ongoing compliance work pushed back toward the cautious view. Overall, the evidence cut both ways.
The useful takeaway is clear. When a bank pitch leans on efficiency and digital progress, track net margin and reported cost guidance against that story. Then treat any buyback or capital return promises as a separate claim to test rather than folding them into the earnings line.
What ABN AMRO Bank's Price Now Asks You To Believe
Today ABN AMRO Bank trades at €40.99, with this Narrative’s Fair Value framed below that level. The argument turns on whether strong capital, AI projects and cost programs can offset pressure from compliance spending and tighter mortgage margins.
To justify today’s price, you would need to assume ABN AMRO Bank keeps regulatory issues contained so higher AML and KYC costs do not erode the targeted efficiency gains.
"Although ABN AMRO Bank is rolling out around 50 AI use cases with higher than planned software development efficiency gains and dedicated tools for KYC and AML analysts, the recent fine for serious and structural AML control failures suggests compliance processes may still lag regulatory expectations, which could require additional investment and weigh on net margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 43% below our estimate - builds advanced networking and AI hardware for hyperscaler programs ramping to higher data speeds.
- Company 2 - 45% below our estimate - sells power and liquid cooling systems supporting expanding AI-focused data center infrastructure.
- Company 3 - 44% below our estimate - opens new flagship stores and online channels to extend a design-led lifestyle brand.
That is three of the list. See all 203 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com