


Is Auckland International Airport (NZSE:AIA) Fully Valued Following Its September Traffic Decline?
Auckland International Airport (NZSE:AIA) has put fresh traffic data on the table, with September passenger movements declining 4% year on year, despite expectations of higher capacity heading into the summer period.
The recent traffic update comes at a soft patch for the stock. Auckland International Airport’s share price has fallen 3.9% over the past 90 days to NZ$8.17. Over a longer horizon, the 1 year total shareholder return sits at 3.6% and the 3 year total shareholder return at 13.4%, indicating that short term momentum has faded while long term holders have still seen positive outcomes.
Compare Auckland International Airport’s softer traffic trend with other companies that currently screen well for resilience by scanning our hand picked 233 resilient stocks with low risk scores alongside your watchlist.
Auckland International Airport’s shares have eased back despite solid long term returns, which puts you at a crossroads. Should you lean into today’s softer price or hold off and wait for a clearer valuation-based entry point later?
Most Popular Narrative: 31.8% Overvalued
The most followed narrative puts Auckland International Airport’s fair value at NZ$6.20, well below the recent NZ$8.17 share price, which frames today’s pullback as a price issue rather than a business quality question.
WATCH, accumulate below ~NZ$5.75 (≈ A$5.30). The binding constraint is price, not durability: a top-decile monopoly moat, a fortress balance sheet and a competent jockey, let down for the buyer only by a ~22–24× EBITDAFI tag that compresses the owner's return to ~9–10% and erases the margin of safety. The specific signal that confirms the thesis is a drawdown into the NZ$5.50–6.00 zone (recession, a regulatory scare, or a pandemic echo). At that point, an irreplaceable asset finally pays a 12–15% return.
See why 1 investors see Auckland International Airport as 32% overvalued.
Result: Fair Value of NZ$6.20 (OVERVALUED)
Still, two pressure points could upend that 31.8% overvaluation view: a regulatory clamp on allowed returns and a fresh pandemic style shock to Auckland International Airport’s traffic.
Find out about the key risks to this Auckland International Airport narrative.
Another Take On Auckland International Airport’s Value
The user narrative pins Auckland International Airport at NZ$6.20 and calls the stock overvalued. Our DCF model lands in a very different place. It suggests AIA is trading well below an estimated future cash flow value of NZ$35.60, which points to a wide upside gap instead of a pricing problem.
Both lenses cannot be right at the same time. Which risk are you more comfortable holding: paying up for an elite asset, or trusting a long dated cash flow model that leans heavily on projections?
Look into how the SWS DCF model arrives at its fair value.
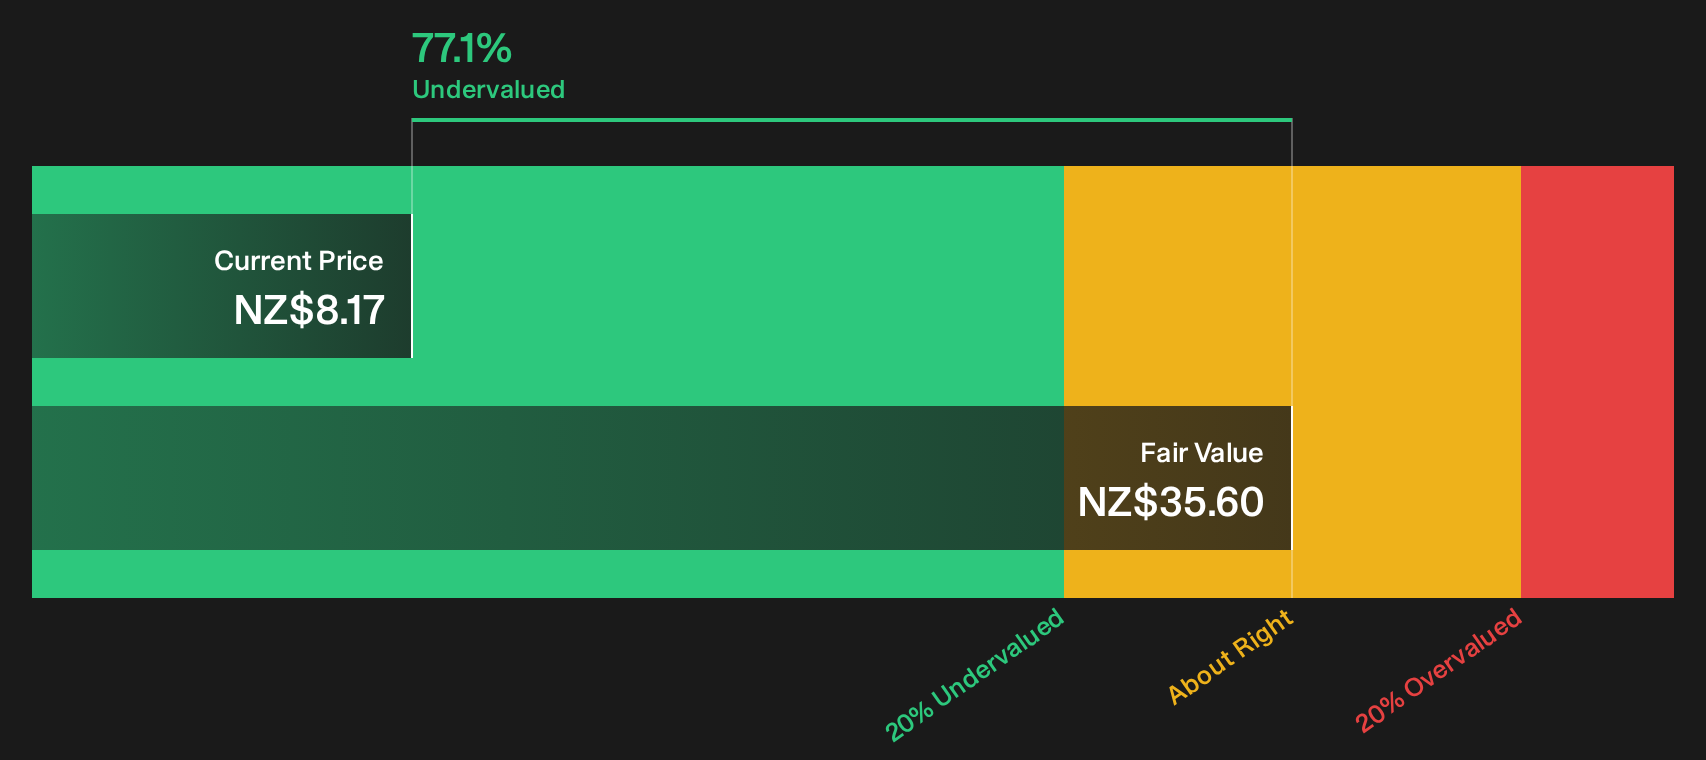
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Auckland International Airport for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between Auckland International Airport’s narratives feels sharp, treat that as a prompt to move quickly, review the underlying data yourself and weigh up the 2 key rewards.
Looking for more investment ideas beyond Auckland International Airport?
If Auckland International Airport has sharpened your focus on quality and price, do not stop here. Broader idea hunting often uncovers opportunities you did not expect.
Use the Simply Wall St screener to quickly shortlist fresh ideas that match the kind of risk and reward profile you want.
- Target deep value opportunities by checking companies that currently appear mispriced on quality and cash flow using the 193 high quality undervalued stocks.
- Strengthen your income stream by scanning for resilient payers with higher yields through the 212 dividend fortresses.
- Protect the downside of your portfolio by filtering for balance sheets that look robust with the list of solid balance sheet and fundamentals (203 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com