


UMH Properties (UMH) Draws Activist Scrutiny, Is The Discount Still Real?
Erez Asset Management’s new presentation on UMH Properties (UMH), tied to recent social media commentary, has pulled fresh attention to the manufactured housing REIT and its current market valuation.
UMH Properties’ recent 1-day share price return of 1.26% to US$15.22 and a 7-day share price gain of 0.79% comes against a 90-day share price decline of 3% and a year-to-date share price drop of 4.28%. At the same time, the 1-year total shareholder return of 13.56% and 3-year total shareholder return of 27.38% point to momentum that has built over time and is now being reassessed as Erez Asset Management’s presentation and the early October shareholder call refocus attention on the REIT’s valuation and risk profile.
Spot opportunities that echo the scrutiny around UMH Properties by scanning our hand-picked 20 high quality undiscovered gems with similar under-the-radar potential.UMH Properties runs a sizeable manufactured housing platform, yet the recent share pullback and activist spotlight leave a sharper question on the table: Is this a solid REIT at a stretched price or still a discount story?
Most Popular Narrative: 22% Undervalued
UMH Properties closed at $15.22, while the most followed narrative pegs fair value at $19.43. The current price sits well below that anchor and keeps the activist debate tightly focused on whether the discount is justified.
The ongoing U.S. housing affordability crisis and the persistent shortage of conventional single-family and multifamily homes continue to drive high demand for quality, affordable manufactured housing, supporting strong occupancy rates and long-term rent growth, benefitting top-line revenue.
UMH's active expansion into energy-rich, high-growth regions (e.g., Marcellus and Utica Shale) and high-demand markets in the Midwest, Northeast, and Southeast is generating above-industry property appreciation and consistently strong occupancy gains, translating into higher rental income and asset value accretion.
See why 9 investors see UMH Properties as 22% undervalued.
Result: Fair Value of $19.43 (UNDERVALUED)
Still, that story can unravel quickly if UMH Properties relies too heavily on new debt to fund growth or if acquisition deal flow continues to stall.
Find out about the key risks to this UMH Properties narrative.
Another View On UMH Properties: High P/E, Different Story
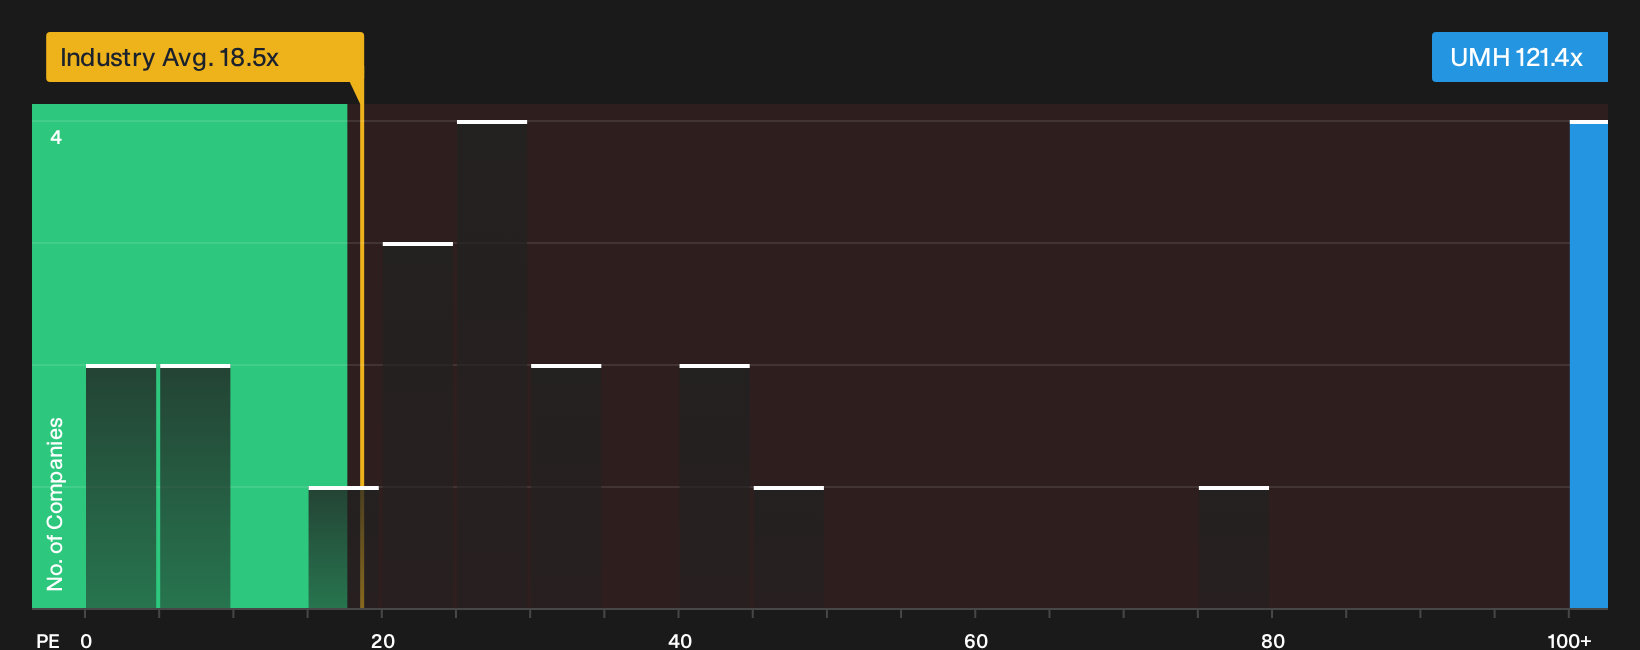
UMH Properties screens as undervalued on a cash flow basis, yet the current P/E ratio of 121.4x tells a very different story. The fair ratio for the stock sits at 35.9x, while the Global Residential REITs peer group trades near 18.7x. That gap points to rich expectations baked into the share price, so which signal do you trust more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around UMH Properties can look confusing at first, so move quickly, review the key numbers, and weigh both the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond UMH Properties?
Use this window of research on UMH Properties to refresh your wider watchlist, compare alternatives, and pressure-test your next moves with high quality, data-driven ideas.
- Target potential mispricings and widen your opportunity set with our hand picked 33 high quality undervalued stocks that pairs solid fundamentals with attractive valuations.
- Strengthen portfolio resilience by reviewing the 32 resilient stocks with low risk scores and focus on businesses with steadier risk profiles and more defensive characteristics.
- Hunt for off-the-radar potential by scanning the 20 high quality undiscovered gems before these ideas move onto everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com