


Price Target Cut Might Change The Case For Investing In Cullen Frost Bankers Stock (CFR)
- Cullen/Frost Bankers recently faced pressure on core fee income, with weaker non interest revenue raising questions about the balance between interest driven and fee based earnings.
- The bank’s recent pattern of earnings surprises and a positive Earnings Expected Surprise Prediction now sit alongside concerns about the resilience of its fee streams.
- The focus turns to how Cullen/Frost Bankers’ investment narrative absorbs weaker core fee income as we assess what this could mean.
Compare how Cullen/Frost Bankers stacks up against other regional financials facing similar fee income pressure by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Cullen/Frost Bankers Investment Narrative Recap
To own Cullen/Frost Bankers, you need to be comfortable with a Texas focused, relationship heavy bank model that relies on steady loan and deposit growth, plus fee income from wealth and other services. The recent pullback tied to weaker core fee income and higher Treasury yields points directly to the near term issue. The key short term swing factor is whether management can keep noninterest revenue from becoming a drag while protecting loan spreads.
The biggest current risk is that fee softness overlaps with pressure in Texas commercial real estate, energy linked borrowers, or more aggressive pricing from rivals, which could squeeze both credit costs and net interest margin. If fee trends stabilize or only prove modestly weaker than expected, the recent news may matter more for sentiment than for the underlying branch expansion, mortgage platform build out, and ongoing customer acquisition story.
The most relevant data point in this context is Cullen/Frost Bankers’ recent pattern of earnings surprises, with an average beat of 7.22% over the last two quarters and a positive Earnings Expected Surprise Prediction of 0.12%. That history indicates that management has recently been able to run the franchise with enough discipline to come in ahead of forecasts, even as it spends on branch growth and technology.
For you, the link to the latest fee income concern is straightforward. Upcoming results expected on 29 October 2026 will test whether the bank can still deliver relative to those earnings expectations while noninterest revenue faces pressure and Texas competition remains intense. Execution on credit quality, deposit costs, and operating expenses now matters even more if fee lines take longer to recover, because it leaves less room for error elsewhere in the business.
Cullen/Frost Bankers’ current analyst narrative points to revenue of US$2.6b and earnings of US$716.4m by 2029, based on forecasts that assume revenue grows at 5.1% per year and profits rise by about US$47m from US$669.4m today.
Uncover how Cullen/Frost Bankers' fair value indicates a 13% potential upside to its current price. This could narrow quickly as sentiment shifts around Cullen/Frost Bankers.
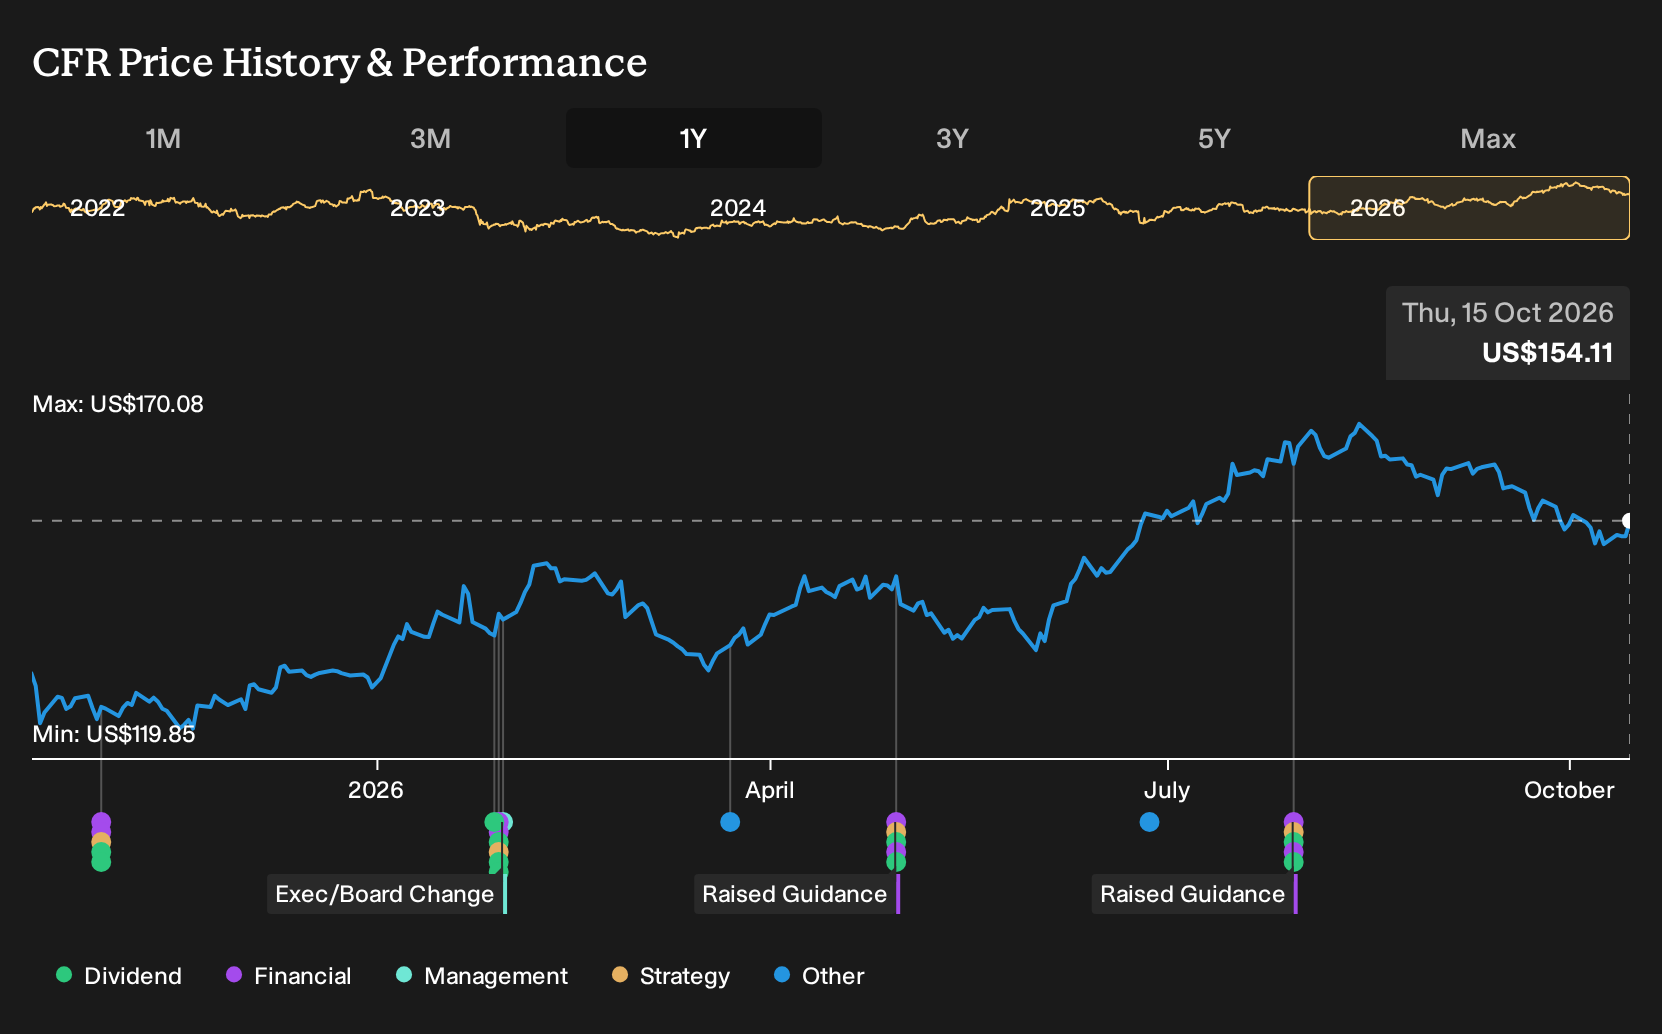
Exploring Other Perspectives
Fair value estimates for Cullen/Frost Bankers from the Simply Wall St Community span roughly US$175 to US$257 across 2 individual assessments, so retail views already stretch from cautious to optimistic. When you set these pre news opinions against the recent fee income concerns and rate cut worries, you get plenty of room for disagreement. Explore those alternative viewpoints before you decide how today’s earnings mix and Texas exposure fit your own thesis.
Explore another Cullen/Frost Bankers fair value estimate, including one that suggests it could be worth just $174.86.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cullen/Frost Bankers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cullen/Frost Bankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cullen/Frost Bankers' overall financial health at a glance.
Looking For More Ideas Beyond Cullen/Frost Bankers?
If this update on Cullen/Frost Bankers sharpened your view on bank risk and reward, apply the same lens across a wider watchlist using the Simply Wall St Screener. You can quickly surface stocks that fit your preferred mix of quality, balance sheet strength, and return profile instead of sorting through tickers one by one.
- For investors who want potential mispriced opportunities with solid fundamentals, start with 20 high quality undiscovered gems that sit off most radar screens yet still clear key quality checks.
- If you care most about resilience and want fewer balance sheet surprises, focus on companies in the 32 resilient stocks with low risk scores that score well on financial strength and business stability.
- Income focused investors can anchor their watchlist around 7 dividend fortresses that combine higher yields with fundamentals that support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com