


Hai Long Turbines Go Live Might Change The Case For Investing In Northland Power Stock
- Northland Power reported that all 73 turbines at the 1.0 GW Hai Long offshore wind project in the Taiwan Strait are now installed and generating power, with timing and construction costs aligned with original plans and supported by a 30 year offtake agreement.
- The Hai Long milestone materially cuts construction risk for one of Northland Power’s largest assets and increases visibility on long term contracted cash generation at a time when funding pressures and execution on big projects have been key concerns for investors.
- We will now examine how Northland Power's investment narrative is affected by Hai Long reaching full turbine installation and power generation.
Scan for other renewable players with contracted revenues and grid assets by jumping into our hand picked list of 41 power grid technology and infrastructure stocks alongside Northland Power's latest offshore wind progress.
Northland Power Investment Narrative Recap
For you to be comfortable owning Northland Power, you need to buy into a simple idea. Large offshore wind and storage projects with long contracts can, over time, support steadier cash generation than the construction phase suggests. Hai Long reaching full turbine installation, with costs aligned to plan, supports that view because it reduces one of the biggest execution swing factors.
The short term hinge point is whether Northland Power can translate Hai Long, Baltic Power and Polish storage into predictable operating cash flow without needing fresh equity. That risk has been flagged before. Progress at Hai Long lowers construction uncertainty, but funding pressure and the potential for future delays or overruns on other projects remain front of mind.
The Baltic Power update earlier this month ties directly into the same thesis. All 76 turbines are now in place, more than one third are already feeding power to Poland’s grid, and the project benefits from a 25 year contract for difference, which is designed to provide revenue certainty once fully online.
For an investor watching Northland Power, Baltic Power and Hai Long now move together as a paired catalyst. Each step through commissioning shifts more of the portfolio from construction to contracted operations, which can help earnings resilience. The flip side is that any setback across this cluster of builds would quickly reopen questions around leverage, dividend coverage and future capital needs.
Northland Power's current story hinges on analyst forecasts that revenue reaches about CA$2.8b and earnings reach CA$433.7m by 2029. That path assumes yearly revenue growth of 3.4% and an earnings swing of roughly CA$582m from today’s loss of CA$148.2m to the 2029 consensus figure.
Uncover why Northland Power's fair value indicates a 21% potential upside to its current price before investors fully price in Hai Long and Baltic Power.
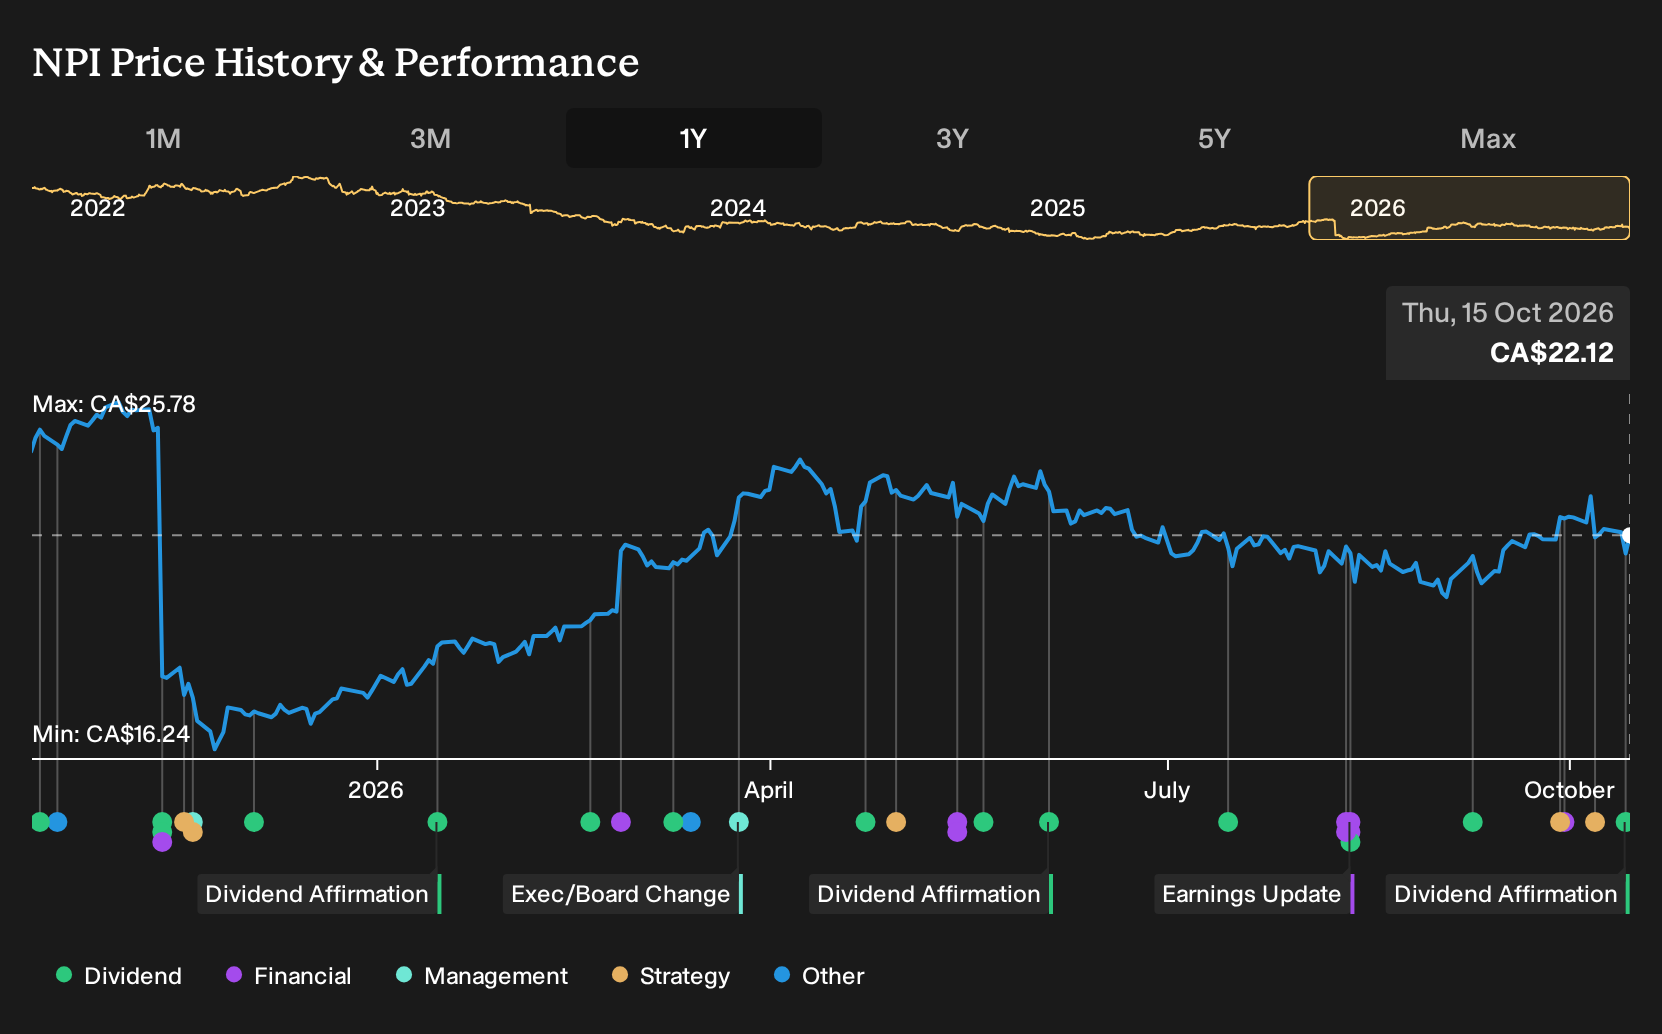
Exploring Other Perspectives
For Northland Power, the alternate narrative zooms in on funding risk rather than project execution. Some of the most cautious analysts were already focused on debt load and potential equity needs, even as consensus assumed revenue of about CA$2.8b and earnings of roughly CA$433.7m by 2029. Those higher and lower cases came before the Hai Long and Baltic Power turbine milestones, so opinions may shift. You can compare these contrasting estimates yourself and decide which storyline feels closer to your own view.
Explore 2 other Northland Power fair value estimates, including one that suggests there may be as much as 32% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Northland Power research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northland Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northland Power's overall financial health at a glance.
Looking For More Investment Ideas Beyond Northland Power?
If the Northland Power story has you thinking about what else might fit your portfolio, the Simply Wall St Screener can help you line up other stocks with fundamentals that match your own checklist, whether you care more about value, income, balance sheet strength, or something entirely different.
- For investors who care about quality at a reasonable price, start with a focused group of 6 high quality undervalued stocks that currently screen well on both fundamentals and valuation.
- If income resilience matters to you, zero in on a curated set of 3 dividend fortresses that pair higher yields with a record of paying shareholders.
- When capital preservation sits near the top of your priorities, filter for stability first and examine a 8 resilient stocks with low risk scores that scores well on balance sheet strength and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com