


SK Hynix (KOSE:A000660) Stock Looks Below Fair Value After Recent Pullback
SK hynix has delivered very strong multi year returns, yet a recent pullback has put fresh focus on whether the current share price lines up with the earnings that support it. For anyone looking at the chipmaker today, the question is whether the stock's recent swings reflect a change in the underlying profit story or just shifting sentiment around the semiconductor cycle.
- Over the past 5 years, SK hynix has produced a gain of more than 10x, which puts a lot of past success on the table as you weigh what its current valuation implies for future earnings power.
- Recent pressure on South Korean chip stocks, tied to worries about AI infrastructure spending, Chinese competition and heavy capital investment needs, can influence how reliably SK hynix converts demand for high end memory into durable profitability.
- Your read on SK hynix is one view; the desks covering it have another. See what analysts think SK hynix's shares could be worth.
The stock's next move may depend on whether SK hynix's current earnings and their trajectory can justify where the shares trade today.
If you want to pressure test SK hynix's valuation debate against a wider set of AI-linked hardware suppliers, compare it with 55 AI infrastructure stocks.
Is SK hynix a Bargain on Earnings?
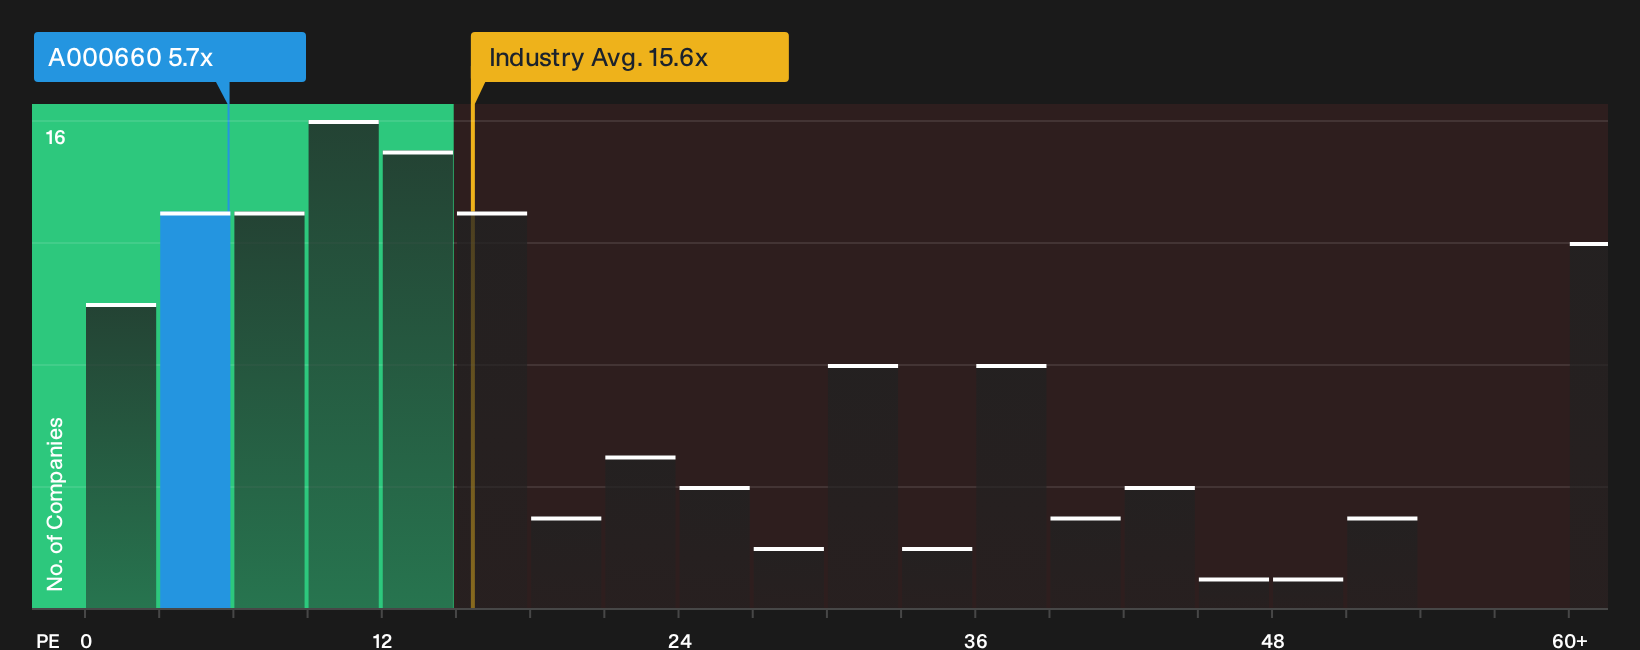
The P/E ratio suits SK hynix because earnings remain a central yardstick for how the market prices memory chip makers. On this measure, the stock trades at about 5.7x earnings, which is far below both the semiconductor industry average of roughly 15.6x and a peer group closer to 12.2x.
Because Dell and other AI hardware suppliers have been under pressure on worries about the depth of enterprise AI spending, SK hynix changing hands at such a discount to both its sector and peers suggests investors are demanding a wide margin of safety around the AI memory story. The fair value model, which builds in SK hynix specific growth, margins, size and risk, points to a materially higher multiple than the one applied today, so the current P/E screens as undervalued on this framework. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SK hynix take the valuation puzzle a step further by spelling out which future paths for SK hynix's growth, margins and earnings would need to play out for the share price to reasonably move higher or lower from here, using the Community page as the hub for those scenarios. Where a single ratio or model gives one number, these narratives unpack the future that number relies on so you can watch in real time whether the story that underpins it still holds.
One of the top community narratives on SK hynix: 60% undervalued
"Close partnerships with large AI and GPU customers, including multiyear HBM co development and supply work with NVIDIA and around 10 long term agreements..."
Discover why this Narrative puts SK hynix at 60% undervalued.
One more SK hynix puzzle the valuation alone cannot answer
Price multiples tell you what the market is willing to pay today, but a very different lens comes from where professional analysts think SK hynix could be a few years from now. Explore where analysts expect SK hynix to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com