


How Investors May Respond To United Bankshares Stock On Florida Expansion
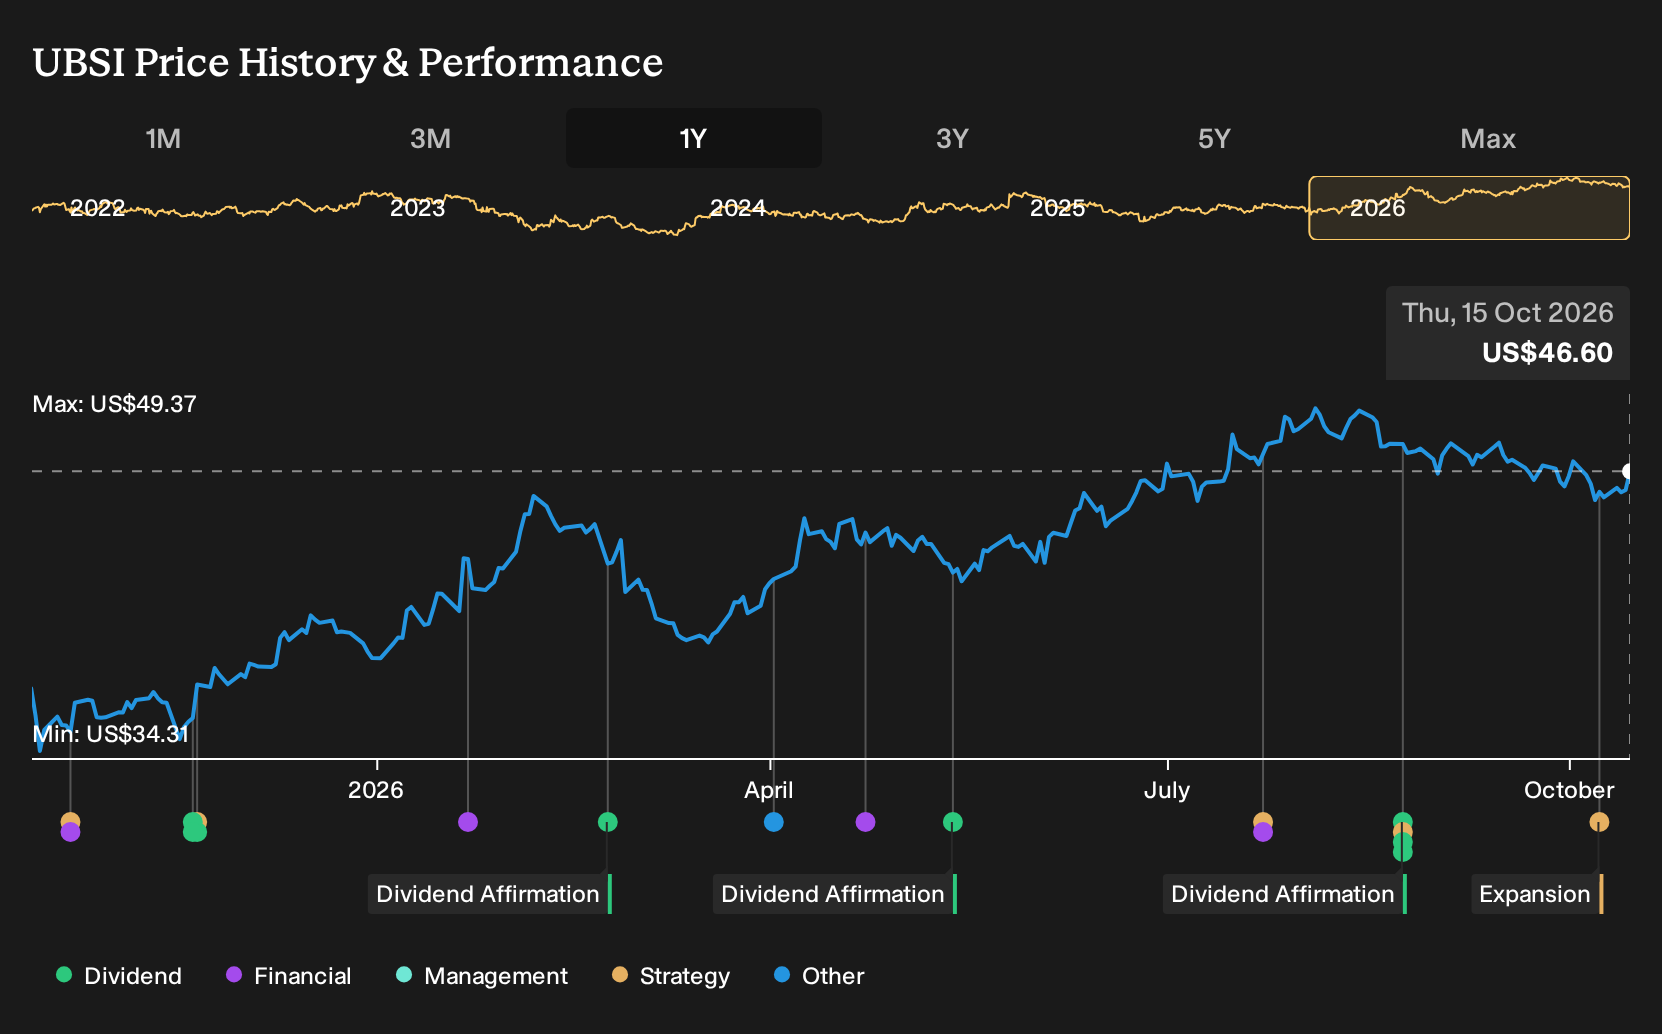
- United Bankshares announced an expansion into Florida in October 2026, planning a new full-service office on Palm Beach Island that combines commercial banking, private banking, wealth management, treasury management, and lending services, subject to regulatory approval.
- This move brings United Bankshares into a concentrated wealth and banking hub where local leadership and specialized talent are central to its plan to build a long-term presence.
- The focus now turns to how United Bankshares’ investment narrative could shift as it targets Palm Beach as a new integrated banking hub.
Scan how United Bankshares’ Florida move compares with other regionally focused banks by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results) that may benefit from similar expansion themes.
What Is United Bankshares' Investment Narrative?
To own United Bankshares, you need to buy into a fairly simple idea. This is a regional bank aiming to compound steady community banking earnings, lean on fee businesses like wealth and trust, and keep funding needs manageable rather than chasing rapid expansion. The Palm Beach move fits that script. Management is trying to tap a high wealth market with one integrated office instead of a heavy branch build out, which keeps capital intensity relatively contained while still testing a new profit pool.
In the near term, the operational story still hinges on execution in the existing Mid Atlantic and Southeast footprint, loan demand, and credit quality more than on one Florida office. Earnings expectations for the September 2026 quarter have been nudged higher, which indicates that sentiment is watching profitability and spreads closely. The Florida build out adds hiring, technology, and regulatory costs, so if revenue ramps slowly or pricing power in that market proves softer than hoped, the trade off between growth and returns for United Bankshares could start to look less comfortable.
That said, there is a less obvious pressure point in the United Bankshares story that could matter a lot if...
There's only one way to know the right time to buy, sell or hold United Bankshares. Head to Simply Wall St's company report for the latest analysis of United Bankshares's Fair Value.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community currently cluster between about US$50 and US$66 per share for United Bankshares, which shows how far apart private investors can land. That spread does not yet factor in the Palm Beach expansion, so you are seeing pre Florida opinions that may shift as the story evolves. Readers should treat these as starting points and compare several community viewpoints before forming any conclusion.
Explore another United Bankshares fair value estimate, including one that suggests as much as 42% upside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Bankshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for United Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Bankshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Bankshares?
If the United Bankshares story has you thinking about how regional banks fit into a broader portfolio, it can help to compare it with other businesses that share some of the same themes but differ on risk, yield, or balance sheet strength.
Use the Simply Wall St Screener to line up potential alternatives and see which profiles resonate most with your approach:
- Target stability first and see which businesses screen well on balance sheet strength and fundamentals via the list of solid balance sheet and fundamentals (25 results).
- If you want income to do more of the heavy lifting, scan for stocks that focus on dependable payouts using the 7 dividend fortresses.
- For investors hunting for less crowded ideas with solid foundations, the 20 high quality undiscovered gems can surface opportunities that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com